

Ornstein–Uhlenbeck Half-Life: Mean Reversion in Trading
Learn how the Ornstein–Uhlenbeck model defines mean-reversion half-life, how to calculate it from a discrete AR(1), and why it is not a forecast of trade duration.
In this guideHalf-life summarizes the decay of an expected deviation
Short summary
An Ornstein–Uhlenbeck (OU) model describes a variable whose conditional expectation moves back toward a long-run mean. Its half-life is the time for the expected distance from that mean to shrink by half. It summarizes one estimated dynamic; it does not tell you when a noisy path will cross a trading exit or whether a spread will keep the same behavior.
Half-life summarizes the decay of an expected deviation
Suppose a spread is above its estimated long-run mean. A mean-reverting model says the expected spread tends to move back toward that mean over time. The half-life answers a narrow question: under the fitted model, how long until the expected deviation is half as large? If the initial deviation is 100 basis points, a four-period half-life means the model's conditional expected deviation is about 50 basis points after four periods.
That statement concerns an expectation across possible paths. A realized spread can rise first, cross the mean quickly, or stay away from it for much longer. Half-life also depends on the observation unit: a value estimated from daily data is measured in days, while one estimated from hourly data is measured in hours. Always state the sampling interval and the model used to estimate the speed.
The continuous-time OU equation gives the formula
A one-factor OU process can be written as
\[ dX_t = \kappa(\mu-X_t)\,dt + \sigma\,dW_t, \]
where \(\mu\) is the long-run mean, \(\kappa>0\) is the speed of mean reversion, \(\sigma\) controls instantaneous random variation, and \(W_t\) is Brownian motion. The drift points toward \(\mu\): above the mean its conditional direction is downward, and below it the direction is upward.
The conditional expected deviation follows
\[ \mathbb{E}[X_{t+\tau}-\mu\mid X_t] = e^{-\kappa\tau}(X_t-\mu). \]
Set the multiplier to one half, \(e^{-\kappa h}=1/2\), and solve for elapsed time:
\[ h_{1/2}=\frac{\ln 2}{\kappa}. \]
The half-life does not include \(\sigma\). Volatility affects how widely individual paths move around the conditional expectation, while \(\kappa\) sets the expected rate of decay in this model. Uhlenbeck and Ornstein's analysis of Brownian motion supplies the classical stochastic-process foundation; Vasicek later used an OU-type process to model the short interest rate.
A discrete AR(1) produces the same decay under specific conditions
With equally spaced observations separated by \(\Delta\), an exact sample of the OU process has the form
\[ X_{t+\Delta}-\mu = \phi(X_t-\mu)+\eta_{t+\Delta}, \qquad \phi=e^{-\kappa\Delta}. \]
For the scalar OU model with \(\kappa>0\), \(0<\phi<1\). The discrete half-life in observations is
\[ h_{1/2}=\frac{\ln(1/2)}{\ln(\phi)}, \]
and the elapsed time is this value multiplied by \(\Delta\). If the estimated AR(1) coefficient is zero or negative, or is at least one, this simple positive-speed OU conversion does not apply. A different dynamic model may be needed instead of forcing an OU interpretation.
The same equation can be estimated in change form, \(\Delta X_t=a+bX_{t-1}+\epsilon_t\). For a stationary AR(1) that also satisfies \(0<1+b<1\), set \(\phi=1+b\), \(\kappa=-\ln(\phi)/\Delta\), and the implied long-run mean is \(-a/b\) when \(b\ne0\). Keep the sampling interval in the conversion; changing from daily to weekly data changes the coefficient's time scale.
The clock is defined by \(\Delta\). For a daily equity series, one observation step usually means one trading session, not 24 calendar hours, so a four-observation half-life should not automatically be described as four calendar days across a weekend or market holiday. If bars have irregular durations, such as event- or volume-based sampling, the constant-interval conversion may not apply. State the asset, sampling schedule, and whether the reported unit is an observation, trading session, or elapsed time.
A hypothetical example shows how the number is read
Suppose a daily spread model estimates \(\phi=0.84\) from equally spaced daily observations. This is a hypothetical teaching value, not a live estimate. Its per-day mean-reversion rate is \(\kappa=-\ln(0.84)\approx0.1744\), so
\[ h_{1/2}=\frac{\ln(0.5)}{\ln(0.84)}\approx3.98\text{ trading days}. \]
After four days, the expected gap is \(0.84^4\approx0.498\) times its starting size. A 100-basis-point deviation therefore has a model-implied conditional expectation of about 49.8 basis points after four observations, before accounting for estimation uncertainty or changes in the process.
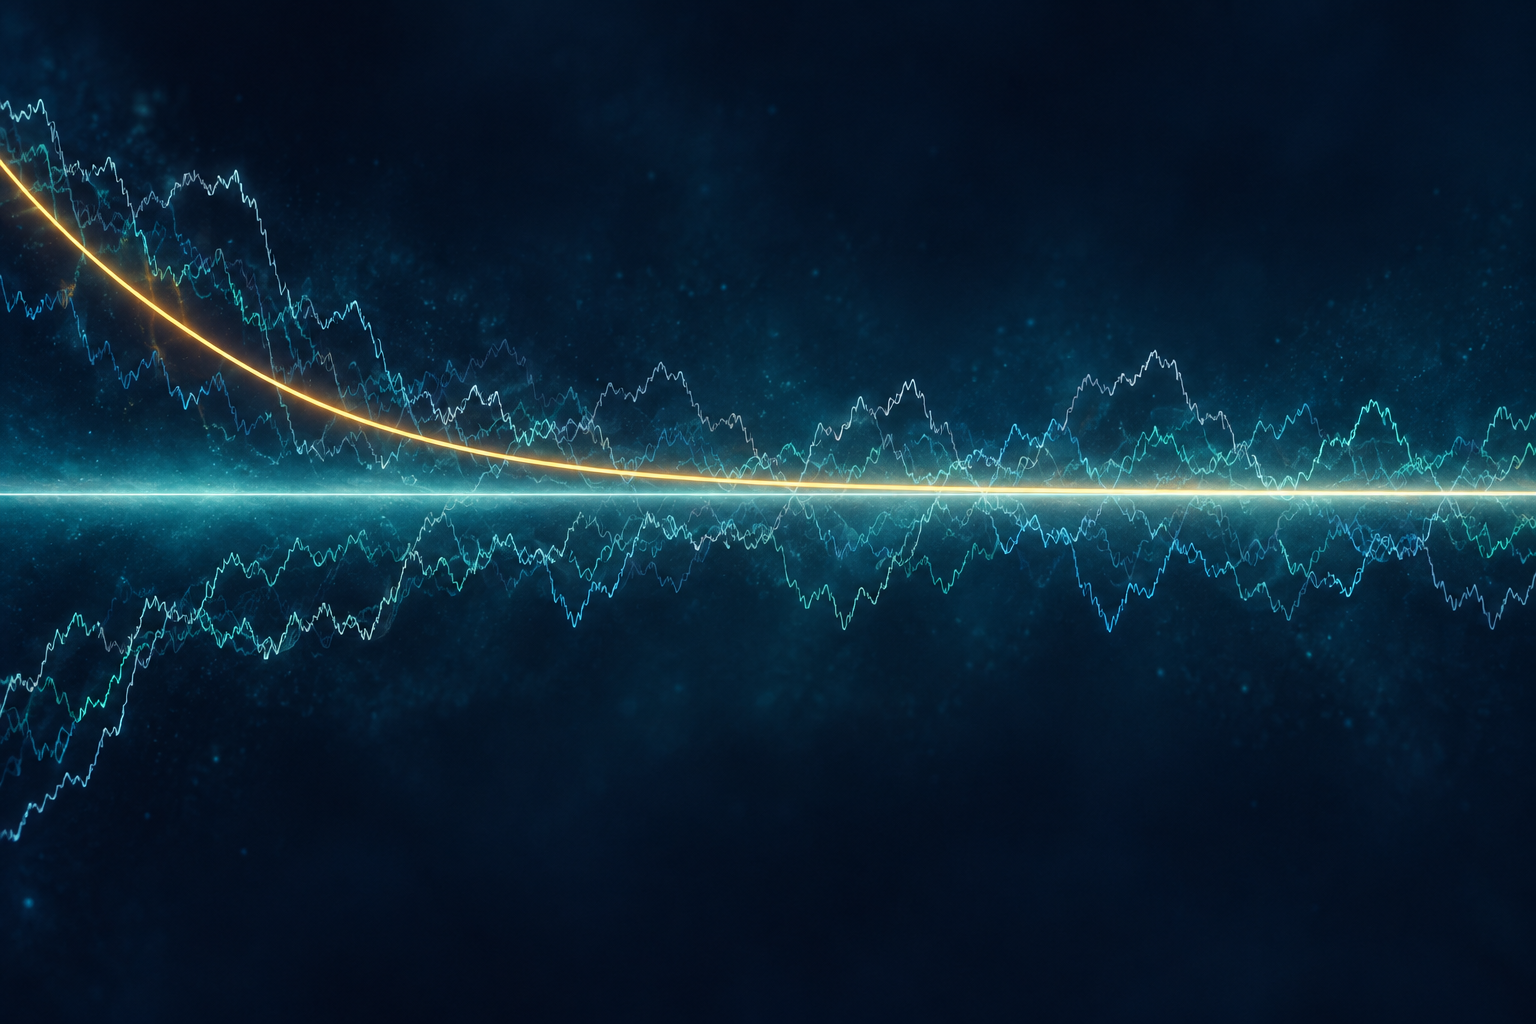
The figure below separates the smoothly decaying conditional mean from sample paths that continue to fluctuate around it. It is a conceptual illustration, not a price history or a claim that every spread follows the modeled mean.
Estimation choices determine what the half-life describes
Start by defining \(X_t\). A cointegrating residual, a price difference, a log-price spread, a volatility-adjusted signal, and a yield spread are different series. Their units and dynamics differ. A cointegration result may support a stationary linear combination under its assumptions, but it does not establish that the residual is a constant-parameter OU process.
Choose the sampling frequency, formation window, mean specification, and lag structure before estimating the decay. A plain AR(1) can hide serial correlation, changing volatility, jumps, intraday market microstructure, or regime shifts. Check residual behavior and parameter stability, and report if the estimate is conditional on a particular sample. The empirical comparison by Chan, Karolyi, Longstaff, and Sanders illustrates why evidence for mean reversion can be weak and model-dependent even for short rates.
For a trading spread, estimate parameters using data available at each formation date. Re-estimating a spread or its mean with future observations creates look-ahead bias. If the relationship is recalibrated through time, describe the update schedule and evaluate the full procedure on later data rather than treating the fitted coefficient as known.
Uncertainty can make a short half-life look precise when it is not
The transformation from \(\phi\) to half-life is nonlinear. As \(\phi\) approaches one from below, \(\ln(\phi)\) approaches zero and the implied half-life grows rapidly. A small change in the estimated coefficient can therefore produce a large change in the reported time. For example, the hypothetical estimates \(\phi=0.80\), \(0.84\), and \(0.88\) imply roughly 3.11, 3.98, and 5.42 observations per half-life.
Report uncertainty for the speed or transformed half-life, using an inferential method that fits the estimator and sample. If a confidence interval for \(\phi\) reaches or crosses one, a finite positive stationary OU half-life may not be supported by that interval. Do not report only a point estimate, and do not select the fastest-looking series from a large search without accounting for selection. Estimation error near a unit root can dominate the apparent precision of a single half-life number.
For scale, suppose a hypothetical 95% interval for the sampled coefficient is \([0.78,0.92]\). Within the stationary OU range, the transformed half-life increases with \(\phi\), so the interval maps to about 2.79–8.31 observations, even though the point estimate \(0.84\) gives 3.98. This interval is an illustration, not an empirical result. If the coefficient interval touches one, its half-life upper bound can become unbounded; values at or above one are outside this stationary conversion. Do not trim those values away to manufacture a finite interval. The uncertainty method should also reflect serial dependence and any estimated spread construction, and a search across many pairs or windows should account for the selection step.
Half-life is different from a crossing time or holding period
Half-life tracks the conditional expected size of a deviation. A crossing time asks when a random path first reaches a level such as the estimated mean or an exit threshold. The first-passage distribution depends on both drift and volatility and can be widely spread. William Bertram's optimal statistical-arbitrage analysis treats trade length and return through first-passage calculations, a separate object from the exponential half-life formula.
A trading system still needs explicit entry and exit rules, position sizing, risk limits, and a response to a broken relation. A spread can move farther from its mean before returning, and may not return during the relevant horizon. The expected decay calculation gives no stop level, no probability of reaching a profit target before a stop, and no estimate of returns after fees.
Trading use requires a stable spread and realistic costs
For a pairs trade, the object being modeled is usually a constructed spread, not either asset alone. Its hedge ratio, currency, corporate-action adjustments, financing, borrow availability, and rebalancing policy all affect the realized position. Test whether the spread's long-run relation remains plausible in chronological validation windows; a fast fitted half-life cannot repair a structural break.
Include bid–ask spread, market impact, fees, funding or borrow costs, and the time needed to execute both legs. These costs accrue along the realized path, not merely over the expected half-life. Selection across many pairs, lookback windows, and sampling frequencies can also make a lucky short estimate appear more reliable than it is. Chan and coauthors' empirical results for interest-rate models are a reminder that a familiar mean-reverting form does not guarantee strong evidence in a particular dataset.
The OU framework can organize a hypothesis about a spread's expected dynamics. Whether a trading rule works is a separate empirical question that depends on stability, uncertainty, execution, and out-of-sample results.
Report the model and time units with every estimate
State the series definition, price or return convention, sampling interval, sample window, estimated mean, speed parameter, volatility parameter, and whether the OU equation is continuous-time or inferred from a discrete AR model. Give the coefficient estimate and uncertainty, explain how the half-life was transformed, and show sensitivity to a reasonable alternative window or sampling interval.
For a trading application, also describe how the spread was formed, how parameters are updated, what information is available at each decision, and how transaction costs and failed convergence are handled. Present half-life as a model-implied summary of expected decay, with its uncertainty and units. Do not use it as a stand-alone entry, exit, or profitability claim.
Uhlenbeck and Ornstein's 1930 Brownian-motion paper develops the underlying mean-reverting stochastic process. Vasicek's term-structure model90016-2) uses an OU-type short-rate process. Chan, Karolyi, Longstaff, and Sanders compare continuous-time short-rate specifications and report that evidence and fit depend on model choice. Bertram derives optimal statistical-arbitrage results using first-passage times, illustrating that trade duration is a separate quantity. Related guides explain cointegration and correlation in pairs trading, unit roots and mean reversion, and the Engle–Granger cointegration test.
Common questions
Q1Is a four-day half-life a four-day trading horizon?
No. It describes decay in the model's conditional expected deviation. A realized path's exit time depends on volatility, thresholds, and the trading rule.
Q2Does cointegration imply that a spread follows an OU process?
No. Cointegration concerns a stationary linear combination under specified assumptions. OU dynamics add a particular continuous-time mean-reverting model that must be checked separately.
Q3What if my AR(1) coefficient is at least one?
The simple stationary OU conversion does not produce a finite positive half-life there. Revisit the model and uncertainty rather than forcing the formula onto a nonstationary estimate.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What does the OU half-life describe?
Choose an answer to see the explanation
Options glossary
The existence of a stationary linear combination among nonstationary series, implying a shared long-run equilibrium restriction under a specified model.
Read the deeper guideMean reversionA model-dependent tendency for a variable to move back toward a fixed or changing reference; it does not automatically imply stationarity or tradability.
Read the deeper guide