

Risk Parity Explained: Equal Risk Contribution Portfolios
Learn how risk parity budgets portfolio volatility across assets, calculate component risk contributions, and see how equal risk contribution differs from equal weighting and volatility targeting.
In this guideRisk parity balances contributions to portfolio risk
Short summary
Risk parity allocates a chosen risk budget across portfolio components. In the common equal risk contribution (ERC) version, each component is assigned the same share of estimated portfolio volatility, so equal dollars or equal asset weights are not the target. The result depends on the covariance estimate and on what counts as a component; it does not forecast returns, set the portfolio’s total risk by itself, or guarantee diversification when correlations change.
Risk parity balances contributions to portfolio risk
A portfolio can divide capital evenly while concentrating most of its volatility in one or two assets. A 10% move in a volatile asset matters more than the same-sized position in a quiet asset, and co-movement changes how much each position adds to the portfolio’s total risk. Risk parity changes the allocation question from “How much capital goes to each holding?” to “How much of the selected portfolio risk should each component contribute?”
The phrase risk parity covers a family of risk-budgeting methods. A risk budget is a target share \((b_i)\) for component \(i\), with budgets summing to one. Equal risk contribution is the special case \(b_i=1/N\) for \(N\) components. Other budgets can assign different shares to asset classes or factors. Maillard, Roncalli, and Teïletche analyze equally weighted risk contribution portfolios as an alternative to equal-capital and minimum-variance allocations (their 2010 paper).
In the standard formulation, “risk” means the portfolio’s estimated return volatility. That choice is explicit, not universal. An ERC portfolio based on volatility is not the same thing as one that equalizes expected shortfall, drawdown, liquidity risk, or risk-factor exposure. State both the risk measure and the components being budgeted before calling a portfolio risk parity.
Risk parity also does not mean that the portfolio has no risk or that all holdings have the same weight. It is a rule for distributing a chosen risk measure across components, conditional on estimated inputs and constraints. It says nothing on its own about whether the portfolio’s expected return compensates for that risk.
Volatility and covariance determine each component’s risk share
Let \(w\) be the vector of portfolio weights and \(\Sigma\) the covariance matrix of returns over a common time horizon. Under volatility-based risk parity, estimated portfolio volatility is:
\[ \sigma_p=\sqrt{w^{\top}\Sigma w} \]
The marginal contribution to risk (MRC) for asset \(i\) measures how portfolio volatility changes with a small increase in that asset’s weight:
\[ \mathrm{MRC}_i=\frac{\partial \sigma_p}{\partial w_i}=\frac{(\Sigma w)_i}{\sigma_p} \]
The component risk contribution (RC) multiplies that marginal effect by the asset’s weight:
\[ \mathrm{RC}_i=w_i\,\mathrm{MRC}_i=\frac{w_i(\Sigma w)_i}{\sigma_p} \]
For this degree-one homogeneous risk measure, Euler’s decomposition gives \(\sum_i \mathrm{RC}_i=\sigma_p\). A component’s signed risk share is therefore \(\mathrm{RC}_i/\sigma_p\), and the shares sum to one. Equal risk contribution targets \(\mathrm{RC}_i=b_i\sigma_p\) with \(b_i=1/N\) for every component. When contributions are nonnegative, each is an ordinary share of portfolio volatility. A strongly diversifying position can have a negative contribution even with a positive long-only weight; short positions can do the same. In that case the contribution is an offset to other components, not a percentage share that can be read in isolation.
The covariance term is important. \((\Sigma w)\) describes how asset (i) co-moves with the entire weighted portfolio, not just its own stand-alone variance. Two assets with the same volatility can have different contributions because one diversifies the rest of the portfolio more. Looking only at each asset’s historical volatility discards this interaction. For a separate rule that scales the total exposure over time, see the guide to volatility targeting.
A three-asset example contrasts equal dollars and equal risk
Consider three hypothetical assets with annualized volatilities of 10%, 20%, and 30%. Assume their returns are uncorrelated, so the covariance matrix is diagonal. These are invented inputs; they are not estimates for real securities. Keeping the measurement horizon the same for each asset makes the arithmetic comparable.
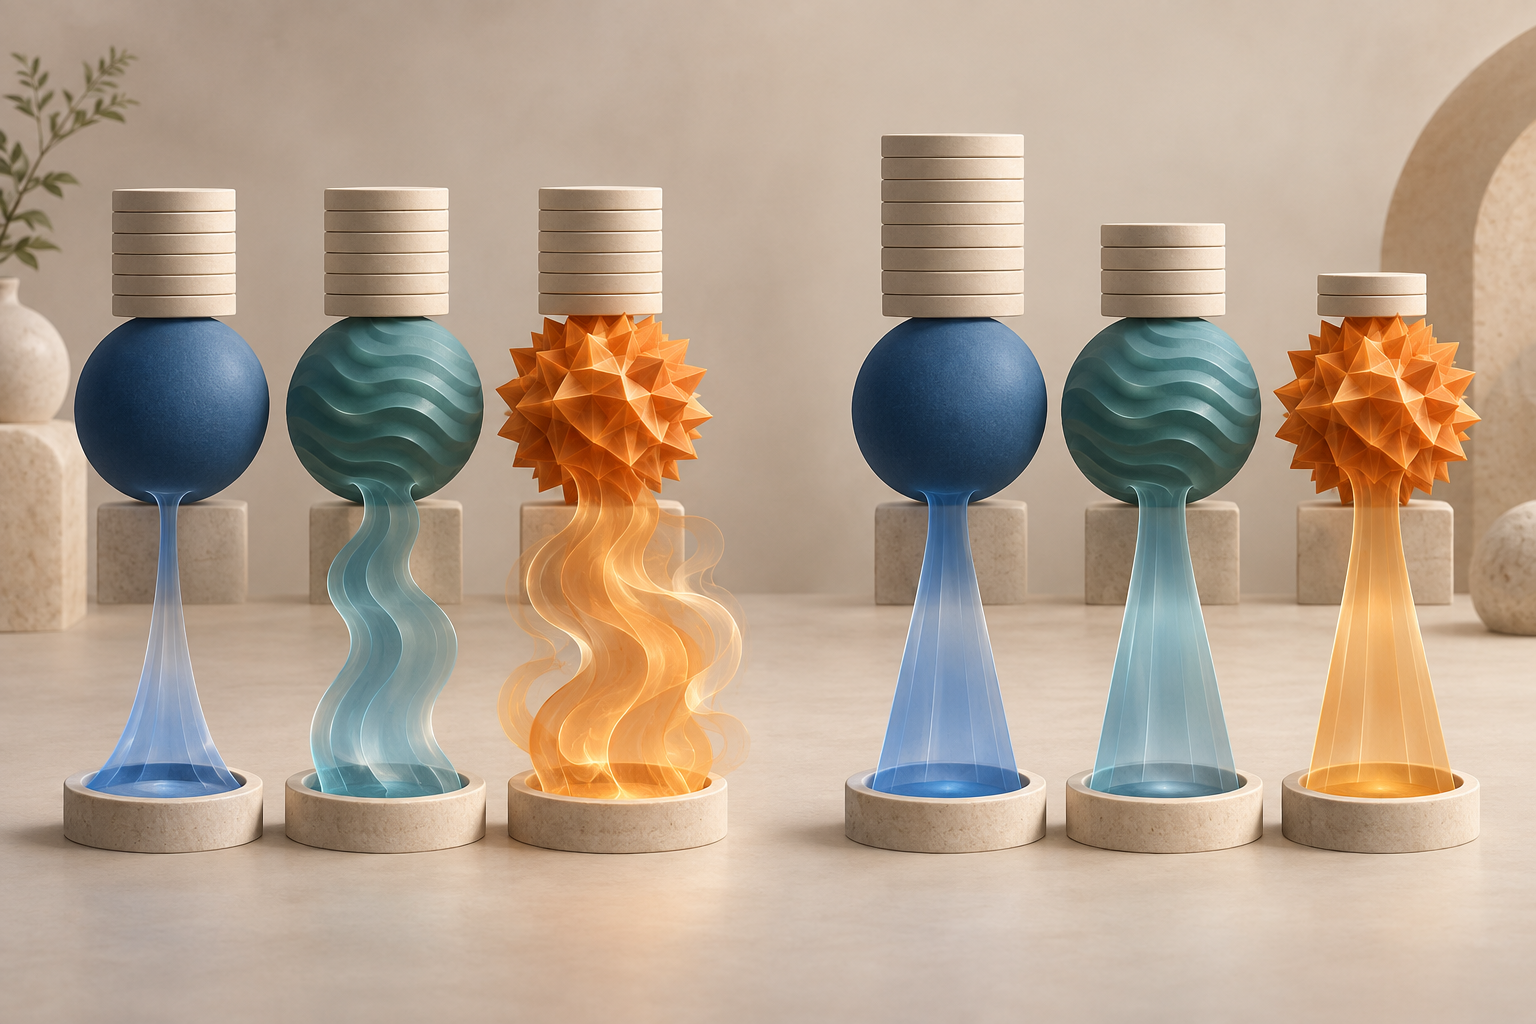
An equal-weight allocation assigns one third of capital to each asset. Its portfolio variance is \((0.01+0.04+0.09)/9\approx0.01556\), so estimated volatility is about 12.47%. Under the uncorrelated assumption, each asset’s share of portfolio variance—and therefore its share of volatility contribution—is proportional to \(w_i^2\sigma_i^2\). The resulting risk shares are \(1/14\approx7.14\%\), \(4/14\approx28.57\%\), and \(9/14\approx64.29\%\). Equal dollars leave the highest-volatility asset responsible for nearly two thirds of estimated portfolio risk.
For uncorrelated assets, setting \((w_i\sigma_i)\) to the same value makes their squared contributions equal. Normalizing the inverse-volatility weights gives:
\[ w_i=\frac{1/\sigma_i}{\sum_{j=1}^{3}1/\sigma_j} \qquad\Longrightarrow\qquad (w_1,w_2,w_3)=\left(\frac{6}{11},\frac{3}{11},\frac{2}{11}\right) \]
The capital weights are about 54.55%, 27.27%, and 18.18%, while each asset contributes one third of the estimated portfolio volatility. The ERC portfolio’s volatility is about 9.45% under these assumptions. The lower-volatility asset receives the largest capital weight, yet it does not dominate the portfolio’s risk contribution.
<!-- Illustration placement: after this section; text-free conceptual comparison of equal capital slices with uneven risk streams versus unequal capital slices with balanced risk streams across three abstract asset groups. No labels, axes, or values. -->
That inverse-volatility shortcut is not a general solution for an arbitrary covariance matrix. In this example there are no cross-asset covariances, so each asset contributes its own weighted variance. With correlations, the marginal risk is \(((\Sigma w)_i/\sigma_p)\), and the ERC weights must respond to the full matrix. In two-asset cases and some highly symmetric covariance structures, the normalized inverse-volatility rule also has a closed form; for a general multi-asset portfolio, it does not.
Correlation and the definition of a component change the answer
Suppose two assets have the same stand-alone volatility. If they are highly correlated with each other while a third asset is less correlated with both, the first pair may behave like one concentrated source of risk. Equal capital weights treat them as separate holdings, but covariance-aware ERC sees the combined exposure through \((\Sigma w)\). The exact risk budgets can therefore require weights that differ from both equal weighting and inverse stand-alone volatility.
The unit of allocation matters just as much. Equal budgets across three broad asset classes are different from equal budgets across every ETF or futures contract held inside them. If one class is represented by ten highly related securities and another by a single instrument, assigning one budget per security gives the first class ten times as many slices. A component might instead be an asset, an asset class, a portfolio sleeve, or a systematic factor. Roncalli and Weisang distinguish risk parity across assets from allocations across common and residual risk factors (their risk-factor paper); the factor-model guide introduces factor exposures.
Choosing a risk measure can alter the result too. Volatility treats positive and negative deviations symmetrically, even though an investor may care more about losses. Expected-shortfall-based risk budgets use a tail-loss measure and depend on a different set of distribution and scenario assumptions. A portfolio that is balanced by recent standard deviation can still be concentrated in a joint crash scenario that the covariance estimate rarely observed. “Balanced risk” should always be qualified by the risk measure, horizon, components, and data used. The VaR and expected-shortfall guide explains how those tail measures differ.
Estimate risk budgets from the full covariance model
For a selected risk measure (R(w)) that is differentiable and homogeneous of degree one in portfolio weights, the general component contribution is \((\mathrm{RC}_i=w_i\,\partial R/\partial w_i)\). A risk-budgeting portfolio seeks \((\mathrm{RC}_i=b_iR(w))\), where \((b_i>0)\) and \((\sum_i b_i=1)\). Setting every \((b_i=1/N)\) yields ERC. A manager may instead use unequal budgets when the economic mandate deliberately gives some components more or less risk.
In volatility-based ERC, the optimizer uses estimated variances and correlations to solve this system of nonlinear relationships. The covariance estimate might use a fixed historical window, a weighted estimator, or a structured model. The chosen lookback and update frequency matter: a short window reacts faster but can make weights jump, while a long window is smoother but may lag a structural change. If many assets are estimated from a short history, sample correlations can be noisy, so some implementations regularize or shrink the covariance matrix. These are modeling choices rather than features guaranteed by the phrase “risk parity.”
The estimate must also match the actual instruments. Use consistent return intervals, currencies, corporate-action treatment, and price conventions. A futures portfolio requires a conversion from contracts to comparable notional or risk exposures; a portfolio containing hedged and unhedged foreign assets needs an explicit currency-risk treatment. Stale marks and mismatched trading calendars can distort measured covariance even if the optimization is solved correctly.
Constraints change what can be achieved. Long-only rules, maximum weights, leverage limits, liquidity caps, minimum trade sizes, and financing availability can prevent exact target contributions. If constraints bind, report the achieved risk shares rather than calling the numerical target the portfolio’s actual allocation. Rebalance thresholds and trade costs also matter: a mathematically exact update at every estimate can create turnover without a reliable improvement in the covariance input.
Risk parity differs from equal weighting and volatility targeting
Equal weighting chooses capital weights such as \((w_i=1/N)\); its risk shares can be very uneven. ERC chooses relative weights to target risk shares, so those weights are often unequal. Minimum-variance allocation instead minimizes \((w^{\top}\Sigma w)\) subject to its stated constraints. It need not equalize component risk and can concentrate weights if the estimated covariance matrix favors a small subset. Markowitz’s original portfolio-selection framework makes expected return and covariance central to efficient portfolio choice (Markowitz, 1952); basic risk budgeting targets a different object and does not require an expected-return vector.
Volatility targeting answers another question: how much total exposure should the portfolio carry at a particular time? A common design scales a base allocation by \(g_t=\sigma^*/\hat\sigma_{p,t}\), where \(\sigma^*\) is the chosen target and \(\hat\sigma_{p,t}\) is estimated current volatility in the same units and horizon. If applied as a common positive multiplier, this changes total risk while preserving the portfolio’s component risk shares. Risk parity sets those relative component shares; volatility targeting scales exposure through time. The two rules can be combined. The time-varying exposure question is studied separately in work on volatility-managed portfolios by Moreira and Muir; later work also evaluates the performance of volatility-managed strategies (Cederburg and coauthors). These are not the same allocation rule as ERC.
Risk parity also differs from allocations based on forecasts of expected return. The [Kelly criterion guide](/learn/kelly-criterion-position-sizing-trading-explained) focuses on sizing from estimated return and risk for a specified objective; ERC allocates budgets using the chosen risk model without ranking assets by expected return. Neither method removes estimation uncertainty, and a weight rule is not an endorsement of a particular asset.
Risk parity does not remove leverage or model risk
ERC tells the portfolio how its chosen risk measure is divided, not what return each component is expected to earn or what total volatility the investor should accept. An allocation that gives low-volatility assets more capital can still have a lower total volatility than a policy target. Scaling it up may require leverage, derivatives, or financing; that can introduce collateral, basis, liquidity, counterparty, and funding risks that are absent from a simple covariance calculation. Risk parity does not always require leverage, but the portfolio-level exposure decision must be considered separately.
Estimated risk shares are conditional on the data window and model. Correlations can rise under stress, volatility estimates can lag abrupt moves, and a past covariance matrix cannot describe every future joint loss. Equal ex-ante shares are not a promise of equal realized losses during every period. Check contributions through time, stress the covariance assumptions, and examine the portfolio under scenarios that are absent or rare in the estimation sample.
Risk parity is also not an automatic return enhancer. Because the basic method omits expected returns, it can allocate heavily to assets with low estimated risk but unattractive forward returns. Asness, Frazzini, and Pedersen discuss leverage aversion as a possible economic rationale for risk parity and provide evidence within their study’s scope (their 2012 paper); that argument is not a universal explanation or a guarantee of future outperformance. Compare any proposed portfolio against a relevant benchmark using a fixed, out-of-sample evaluation design and realistic net costs.
Report the risk budget and the assumptions behind it
A reproducible risk-parity description states the components, risk measure, target budgets, covariance estimator, lookback, return horizon, rebalance timing, currency conventions, and constraints. Show both portfolio capital weights and component risk shares; one does not imply the other. If the constraint prevents the intended shares, state the achieved values and the binding limits.
For a trading implementation, also report leverage, collateral or financing, turnover, execution assumptions, and costs. Measure estimated and realized risk separately, because an ex-ante risk budget is a model output while ex-post return paths are observed outcomes. Keep the total volatility target separate from the relative risk budget, and do not infer expected profit from balanced contributions.
Risk parity can be a useful way to make concentration in estimated portfolio risk visible and to define a transparent allocation rule. Its usefulness still depends on the chosen components, risk measure, covariance estimates, and implementation. It does not make unlike assets equally safe, remove drawdowns, identify the best return forecast, or guarantee a resilient portfolio when the underlying relationships change.
Common questions
Q1Is risk parity the same as equal weighting?
No. Equal weighting divides capital evenly. Equal risk contribution aims to divide a specified risk measure evenly, so the asset weights usually differ when assets have different volatilities or correlations.
Q2Does every risk-parity portfolio use inverse-volatility weights?
No. Inverse-volatility weights solve ERC in uncorrelated and some special symmetric cases. A general covariance-aware portfolio needs weights that account for all pairwise covariances.
Q3Does risk parity guarantee a target portfolio volatility?
No. Basic ERC controls relative contributions to the selected risk measure. A separate scaling or leverage rule is needed to target total volatility, and that rule introduces its own constraints and costs.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What does equal risk contribution target in a portfolio of N components?
Choose an answer to see the explanation
Options glossary
A model decomposing asset returns into exposure to a small set of common factors and an asset-specific residual.
Read the deeper guideExpected ShortfallThe average loss from a chosen VaR quantile through the worst tail under a precise convention; it measures severity beyond the threshold rather than only its location.
Read the deeper guideAssignmentThe process that requires an option writer to fulfill the contract after an exercise notice is allocated; it can create or remove an underlying position.
Read the deeper guide