

Volatility Targeting: How Volatility Scaling Changes Position Size
Learn how volatility targeting scales exposure, how to choose and lag a volatility estimate, and why leverage caps, correlations, and trading costs still matter.
In this guideVolatility targeting changes exposure, not the return signal
Short summary
Volatility targeting changes the size of an existing exposure using an estimated risk measure. A basic multiplier is target volatility divided by forecast volatility, but the estimate, portfolio covariance, leverage limit, execution lag, and costs determine what risk the strategy actually takes
Volatility targeting changes exposure, not the return signal
Volatility targeting, volatility scaling, and volatility management describe rules that adjust portfolio exposure as a risk estimate changes.
A directional signal might say to hold a long position; a scaling rule might reduce that position when forecast volatility rises.
A positive scalar preserves the sign of the base position, but can change its gross and net exposure. That distinction matters.
A low-volatility estimate does not itself say an asset is cheap, likely to rise, or more profitable.
The overlay answers “how much exposure under this risk rule?” It does not answer “which asset should I own?” or prove that the underlying strategy has an edge.
Researchers have studied volatility-managed versions of factor portfolios and momentum strategies.
Moreira and Muir report results for several factors and currency carry; Barroso and Santa-Clara study risk management of momentum; Daniel and Moskowitz describe momentum crashes around market stress and sharp rebounds.
These are sample-specific findings, not a promise that live performance will improve.
Examples include Moreira and Muir, Barroso and Santa-Clara, and Daniel and Moskowitz.
The target-to-forecast ratio is a baseline, not a guarantee
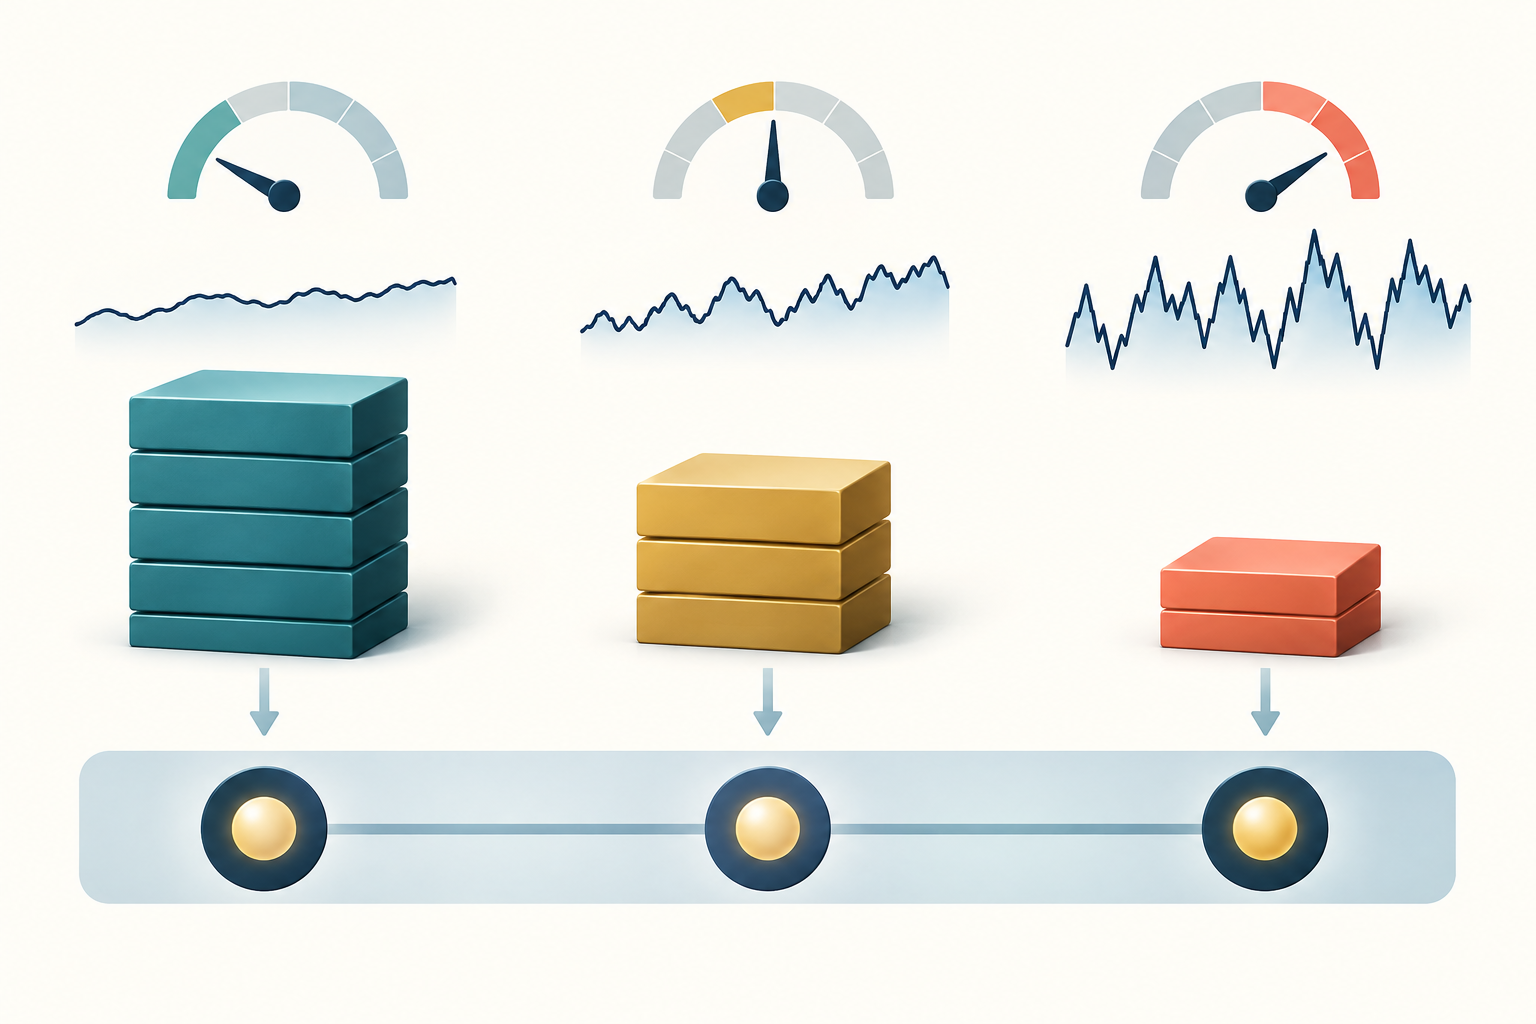
For a single exposure whose return scales approximately linearly with its weight, a starting rule is raw scale = target volatility ÷ forecast volatility.
In a hypothetical example, an unscaled strategy has a 20% annualized volatility forecast and a 10% target, so the raw multiplier is 0.5.
With a reference notional of $100,000, the scaled notional is $50,000 before other portfolio adjustments.
The ratio only makes sense when numerator and denominator use the same portfolio, return definition, horizon, and annualization convention.
A 10% annualized target cannot be divided by a daily standard deviation displayed as a decimal without first putting the measures in compatible units. If forecasts use standard deviation, do not silently substitute variance.
Moreira and Muir’s published factor portfolios instead scale monthly returns by the inverse of the prior month’s realized variance, with a normalization constant.
That design is not the same as dividing a target standard deviation by a forecast standard deviation. In a hypothetical quiet regime, a forecast of 5% against the same 10% target gives a raw multiplier of 2.
If a policy caps the multiplier at 1.25, the notional becomes $125,000, not $200,000. Under the simplifying assumption that risk scales linearly, the corresponding forecast is only 6.25%.
A cap can therefore make the target unattainable; it is a constraint, not a mistake in the arithmetic.
Choose the volatility estimator for the decision horizon
A rolling standard deviation is easy to explain, but its window creates a trade-off: a short window reacts quickly and is noisy, while a long window is steadier and slower after a regime change.
An exponentially weighted estimate gives recent observations more weight. A GARCH forecast models conditional variance recursively.
Intraday realized volatility can capture within-session variation but also faces sampling, stale-price, and microstructure-noise choices. No estimator is best for every asset, sampling frequency, or holding period.
Write down whether the return is simple or logarithmic, which timestamps define a period, how missing sessions and overnight moves are handled, whether the mean is removed, and how periodic variance becomes an annualized standard deviation.
For daily data, multiplying daily volatility by √252 is a common approximation under assumptions about the return process; it is not a universal conversion for every market or calendar.
Look at forecast errors as well as the smoothness of the exposure path. A model can appear stable because it reacts too slowly, or look responsive because it overfits noise.
Compare reasonable estimation windows and forecast models in a walk-forward evaluation, using only information available when each estimate and position would have been formed.
The realized-volatility calculation guide explains how return and sampling conventions change the risk estimate being scaled.
Lag the estimate so the rule could have traded
At rebalance time t, use only observations that were actually available before the order could be sent.
If a daily return includes the closing price at t, a strategy that computes volatility from that close cannot also assume it traded at that same close unless the order timing and price formation make that feasible.
A practical convention is to calculate after the close and apply the resulting scale to the next eligible session. This timing detail prevents look-ahead bias.
Applying the completed month’s realized variance to positions held during that same month gives the rule information it would not yet have had.
A backtest should specify the signal timestamp, volatility-data cutoff, order time, fill assumption, and holding period.
When inputs arrive asynchronously across assets, use a common information cutoff or document the stale observations. Rebalancing need not occur every time a new estimate is available.
A monthly rebalance, a threshold band, or a smoothed exposure can reduce turnover, but also means actual exposure departs from the instantaneous target.
State that implementation choice and test it rather than treating the latest forecast as a frictionless order.
Portfolio volatility depends on covariance, not separate asset readings
For a vector of asset weights w and a covariance matrix Σ estimated over a matching horizon, portfolio variance is wᵀΣw; portfolio volatility is its square root. The covariance terms matter.
Two assets can each retain the same standalone volatility while their correlation rises, increasing the risk of holding both together.
Scaling each asset independently to its own target does not generally target total portfolio volatility.
Conversely, scaling a whole portfolio return series with one multiplier preserves the portfolio’s current mix, but only to the extent that the portfolio forecast is adequate.
Concentration, changing correlations, factor overlap, and derivatives’ nonlinear exposure can make a single standard-deviation forecast incomplete. Estimate risk at the level where the risk limit applies.
If the mandate is a portfolio-volatility range, forecast the combined portfolio and stress correlations or covariance regimes.
If the mandate is per-strategy risk, say how correlated positions share the account budget. Futures position sizing separates a trade stop budget from account exposure.
Floors, caps, and leverage constraints shape the rule
The raw ratio can become very large when estimated volatility is near zero. A volatility floor avoids division by a tiny number, while a maximum leverage cap limits notional exposure.
Some strategies also impose a minimum scale or a drawdown, margin, or liquidity-based ceiling.
A fully specified rule might be scale = min(max_scale, target ÷ max(forecast, floor)), with any minimum exposure documented separately. Each guardrail changes risk behavior.
A floor dampens exposure increases in unusually calm estimates; a cap prevents the rule from reaching its target in low-volatility states; a minimum exposure prevents the overlay from fully exiting when forecast volatility spikes.
Define units and whether the cap applies to gross notional, leverage, margin, or a risk-weighted exposure—these quantities are not interchangeable.
Scaling down after a volatility shock may require selling into a falling or illiquid market. Scaling up after a calm spell may add exposure just before a shock.
The estimate is backward-looking even when it is used as a forecast.
The GARCH and volatility-clustering guide explains why model persistence can make estimates slow to recognize breaks; it does not remove jump or regime risk.
Costs and constraints can consume the benefit
Changing exposure creates turnover. Estimate commissions, bid-ask spread, market impact, slippage, financing or borrow, futures roll costs, and—where relevant—perpetual funding and collateral costs.
A smoother scale or rebalance band may reduce trading, but it may also delay risk reduction. Compare net results under plausible cost assumptions, not just a frictionless series.
Leverage availability can change exactly when the rule asks for more exposure.
Broker or exchange margin, position limits, borrow availability, liquidity, and internal risk limits can block a theoretically calculated notional.
A volatility cap is not a guarantee against liquidation or a large loss; a gap can exceed the forecast and an exit price can differ materially from the signal price.
Measure performance with consistent benchmarks: the same base signal without scaling, a fixed-risk alternative, and, where appropriate, cash.
Report gross and net returns, exposure, turnover, leverage, forecast errors, drawdowns, and tail losses. Moreira and Muir’s results are one reason to study volatility timing.
Cederburg et al. compare 103 equity strategies and find no systematic outperformance from volatility management in direct comparisons. For reasonable real-time, out-of-sample combinations, they report generally lower certainty-equivalent returns and Sharpe ratios, with exceptions (study).
These findings motivate careful out-of-sample evaluation rather than a universal recommendation.
A research checklist separates forecast quality from strategy claims
Before calling an overlay a risk improvement, specify the base signal, risk estimator, forecast horizon, update schedule, timing lag, unit conversion, covariance treatment, floor, cap, and execution assumptions.
Freeze the choices before evaluating the final test period. If you tune these decisions repeatedly on the same sample, the best result may reflect selection rather than a robust rule.
Check the forecast itself with an appropriate loss measure and calibration plot, but also examine the exposure path. A low average forecast error does not guarantee that the most consequential spikes were forecast in time.
Inspect stress periods, price gaps, missing observations, and assets whose correlations can jump. Evaluate the same periods with the actual cap and cost model.
Finally, separate three claims: the forecast estimates risk; the overlay changes exposure according to a policy; and the resulting portfolio performed a certain way in a specified sample.
Evidence for the first does not prove the second will meet its target, and a favorable historical result for the third does not establish future profits.
Document all three so a reader can reproduce where risk changed and why.
Common questions
Q1Does volatility targeting keep realized volatility exactly at the target?
No. It scales exposure using an estimated volatility. Forecast error, jumps, changing correlations, delays, caps, costs, and imperfect fills can all make realized volatility differ from the target.
Q2Is volatility targeting the same as using inverse variance?
Not necessarily. A target-volatility ratio commonly uses target volatility divided by forecast standard deviation. Some empirical portfolio rules scale returns by a constant over estimated variance. Those are different functions and should not be described as interchangeable.
Q3Does a lower volatility forecast mean the strategy is more profitable?
No. It means the risk estimate is lower under a particular model and horizon. Profitability depends on expected returns, implementation, costs, and future outcomes; a volatility estimate alone does not identify an attractive trade.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
A strategy has a 20% volatility forecast and a 10% target. What does the basic ratio imply before constraints?
Choose an answer to see the explanation
Options glossary
Volatility calculated from price changes that occurred under a stated return, sampling-window, and annualization rule; different conventions can produce different values.
Read the deeper guideGARCHA time-series model that updates conditional variance from past squared shocks and prior variance; it models volatility persistence, not return direction.
Read the deeper guide