

Municipal Bond Insurance: What It Covers and What It Doesn't
Learn what U.S. municipal bond insurance may cover, how insurer and issuer credit differ, and why the guarantee does not protect market price or liquidity.
In this guideInsurance is a secondary payment source
Short summary
Municipal bond insurance is a contract-based backup for specified scheduled payments. It may support covered principal or interest if the primary obligor does not pay, but it does not guarantee the insurer's solvency, the bond's resale price, or coverage beyond the policy terms.
Insurance is a secondary payment source
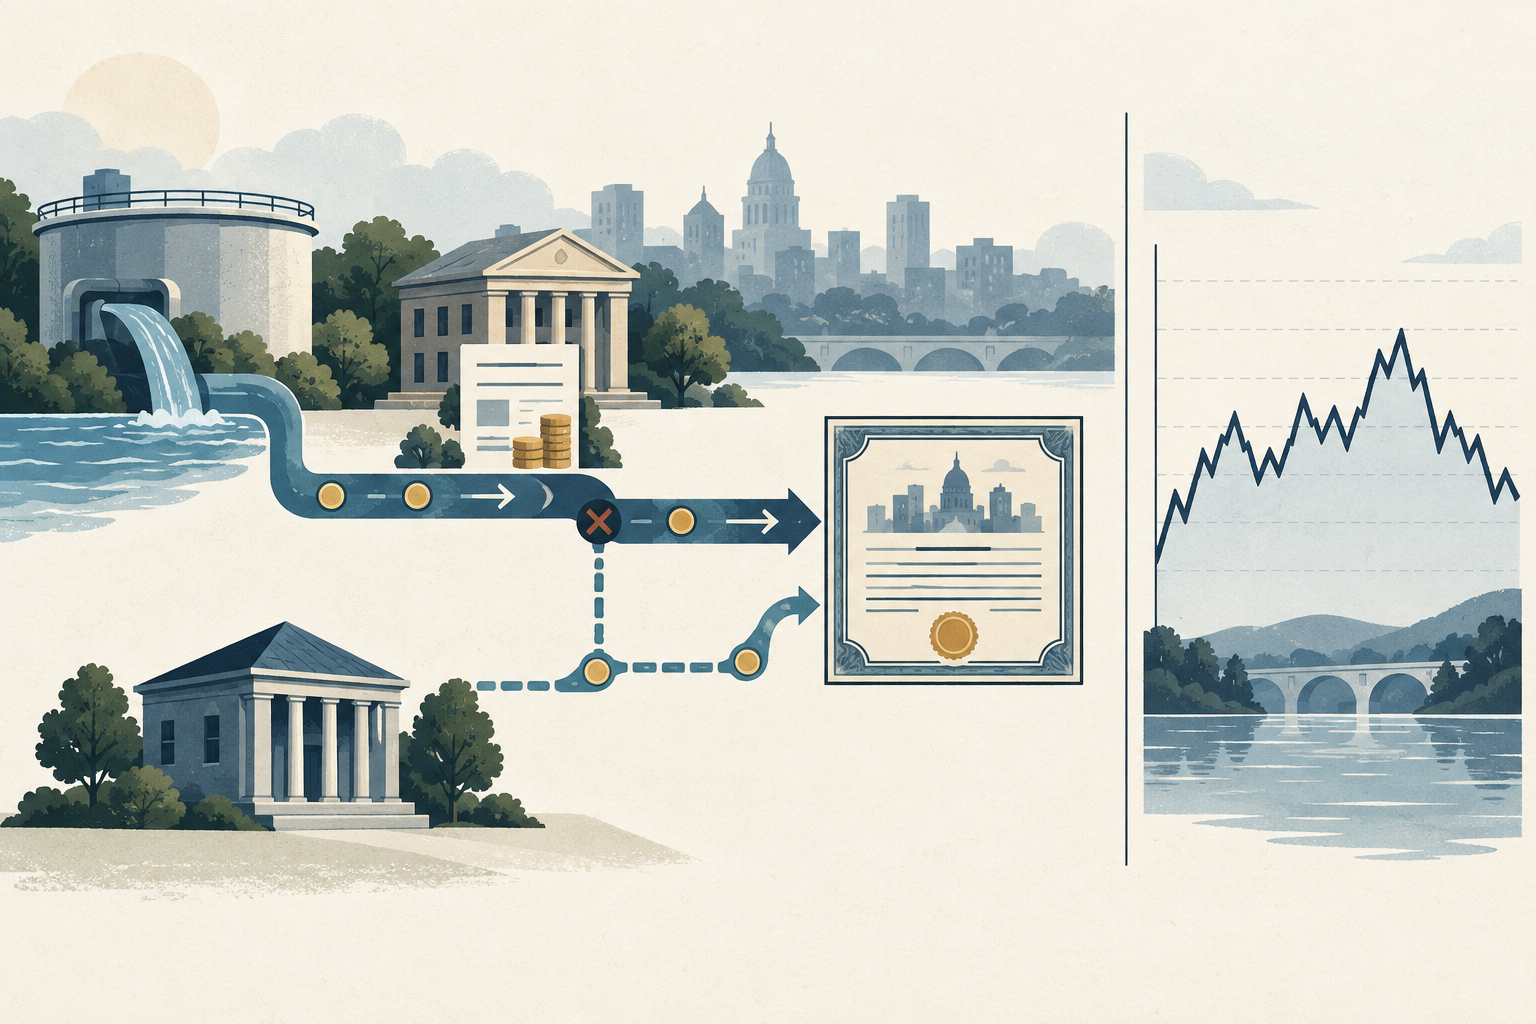
For a U.S. municipal bond, insurance is a contract with a third-party insurer that may add a secondary source for covered principal and interest. The issuer or conduit borrower remains responsible for the primary debt; the insurer's promise is separate and extends only as far as its policy says. The MSRB describes bond insurance as one form of credit enhancement that backstops a bond's primary repayment pledge.
“Secondary” describes the role in the payment structure, not a promise that the insurer will step in before every missed transfer has been verified. A bond may route money through a trustee or paying agent, and its policy may require notice, documentation, and a defined claim process. The investor should identify who can submit a claim and what counts as a covered failure. A delay in the payment chain, a dispute about an amount, and a failure by the insurer are different events.
The MSRB repayment guide treats credit enhancement as a secondary source; a 2009 MSRB–FINRA investor notice also discusses insurer strength and bond risk.
Trace a missed scheduled payment
Assume a bond has $10 million face value, a 4% annual coupon and semiannual interest. Its scheduled coupon is $10,000,000 × 0.04 ÷ 2 = $200,000. If the issuer misses the date, a policy covering scheduled interest may require the insurer to provide the covered payment under its claim and timing terms. The insurer does not automatically buy the bond or cancel the issuer's obligation.
The coupon arithmetic does not say when an insurer must pay or whether a claim is automatic. Principal coverage may apply at maturity or to specified scheduled redemptions, while interest coverage may follow separate due dates. A policy can address how missed payments are handled and whether the insurer later takes over related rights. Read the policy and indenture together: one states the insurer’s promise, while the other describes the bond obligation and payment machinery.
New-issue and secondary insurance start at different times
New-issue insurance is arranged for a bond at issuance, and its premium forms part of the issuer's financing economics. Secondary-market insurance is obtained after issuance and generally applies to an eligible bond for its remaining term. Confirm which CUSIPs and maturities are covered, who arranged the policy, and whether the coverage continues when the bond is resold; policy wording and eligibility rules vary.
Insurance usually cannot be assessed from the series name alone. An issue may contain maturities with different insurance status, and a secondary policy may have its own eligibility and effective-date rules. Confirm whether the policy attaches to the bond and remains with later holders, or whether it is a separate arrangement with limitations. Also compare the covered remaining term with the time the investor expects to hold the bond; the two periods need not match.
Read the policy, not the label
Read the policy attached to the offering rather than relying on an “insured” label. Check the covered securities, scheduled principal and interest, due dates, claim notice and payment process, and treatment of calls, sinking-fund redemptions, acceleration, tenders and paying-agent failures. One BAM policy in an EMMA official statement covers specified scheduled principal and interest under its terms and says it does not guarantee market price or liquidity. That issue-specific example is not a universal policy template.
Look for definitions as well as the coverage summary. “Principal” can be affected by call schedules and sinking-fund redemptions; “interest” can have a stated schedule and day-count basis. Tender features, accelerated maturity, court orders, voidable transfers, and procedural failures may receive special treatment. Do not infer that a feature is insured because it appears in the official statement. The attached policy controls the insurer’s specific obligation, subject to its terms and governing law.
Compare insurer credit with underlying credit
An insured bond can have an insured rating that reflects the insurer's strength and a separate underlying rating for the issuer or obligor; not every deal has both. Read each rating's date and scope, the insurer's current financial strength, and the issuer's ability to pay without insurance. The MSRB cautions that an enhancer's financial strength can change or weaken over time, so an old rating at issuance is not a current credit check.
The underlying rating answers a different question from the insured rating: how the issuer or obligor is viewed without relying on the enhancement. A bond can have no published underlying rating, so absence of one should prompt review of the issuer’s finances rather than an automatic conclusion about credit quality. The MSRB’s current repayment overview notes that insured bonds may carry two ratings. Compare rating dates and watch for changes at either the insurer or obligor level.
Price and liquidity remain separate risks
Coverage of scheduled payments does not freeze a market quote. Interest rates, trading liquidity, call provisions, issuer credit and insurer credit can all affect the price a buyer will offer before maturity. Insurance is a credit-risk backstop for payments specified in the contract, not a put at par, a ready buyer, or protection against every loss. A downgrade may move the bond's market price even if scheduled payments remain insured.
For example, a bond may continue to make its scheduled coupon while its market price declines because comparable yields have risen or trading demand has weakened. Insurance can support covered payments without offsetting those valuation changes. The 2024 SEC-filed fund disclosure distinguishes payment protection from price protection and notes that insurer deterioration may affect insured-bond values. A buyer who may need to sell early should study recent trades and dealer quotations, not just payment coverage.
The MSRB secondary-market guide explains that quotes and transaction prices reflect market conditions. A 2024 SEC-filed fund prospectus is one disclosure example; its language is not a universal policy.
Check the exact issue on EMMA
Start with the exact CUSIP and official statement on EMMA. Verify the insurer's legal name, insured maturities, attached policy, underlying rating and the latest rating changes; then read continuing disclosures and material-event notices. A bond that was insured when issued still needs current review because both the primary obligor's finances and the insurer's capacity can change. Do not infer that every maturity in a series has identical coverage.
EMMA can help locate the official statement and later disclosures, but each document has a date and scope. Match the CUSIP in the trade confirmation to the CUSIP in the disclosure; a similar issuer name or series label is not enough. Find the insurer named in the policy, current ratings, material-event notices, and any amendments. If the policy is not in the public packet, ask the broker or issuer how to obtain it before treating “insured” as verified.
For a document example, this EMMA official statement for one BAM-insured issue is specific to that issue; its policy wording should not be generalized to other bonds.
Compare issuer cost and investor risk
For the issuer, suppose a $10 million issue has a $75,000 insurance premium and insurance hypothetically lowers its coupon by 0.15 percentage point. At unchanged $10 million par, gross coupon savings are $10,000,000 × 0.0015 = $15,000 a year, or five simple years before discounting, amortization, calls and fees. This hypothetical describes issuer financing, not investor return or proof that insurance is worthwhile. Buyers should compare price, yield to worst, call terms, liquidity, tax status, underlying credit and insurer credit together.
A five-year simple payback is not the same as a present-value break-even. If the issue is called or refinanced earlier, future coupon savings may stop before the premium is recovered. If principal amortizes, the annual savings would generally shrink with the balance rather than remain $15,000. A full issuer comparison would model scheduled debt service, premium timing, fees, call dates, and the alternatives available without insurance. For the investor, the issuer’s savings do not by themselves imply a better yield or safer resale price. Related guides cover [](/learn/municipal-general-obligation-vs-revenue-bonds-pledge-repayment-risk-explained), [](/learn/municipal-bond-tax-equivalent-yield-amt-explained), and [](/learn/callable-bond-yield-to-worst-yield-to-call-explained).
Common questions
Q1Does municipal bond insurance guarantee the bond's market price?
No. It may cover specified principal and interest under the policy, but market price and liquidity can change with rates, credit, calls and trading conditions.
Q2Does an insured rating mean the issuer is financially strong?
Not necessarily. The rating may reflect the insurer's strength. Review the underlying rating and the issuer or obligor's finances as well.
Q3Are all insured municipal bonds covered in the same way?
No. The insured securities, payments, claim triggers and exclusions are defined by each policy and offering documents.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What does municipal bond insurance principally add?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide