

GO Bonds vs. Revenue Bonds: What Actually Backs Repayment?
Compare U.S. municipal GO and revenue bonds by pledge, obligor, lien priority, appropriation, and the repayment terms in the official statement.
In this guideWhat a general-obligation pledge means
Short summary
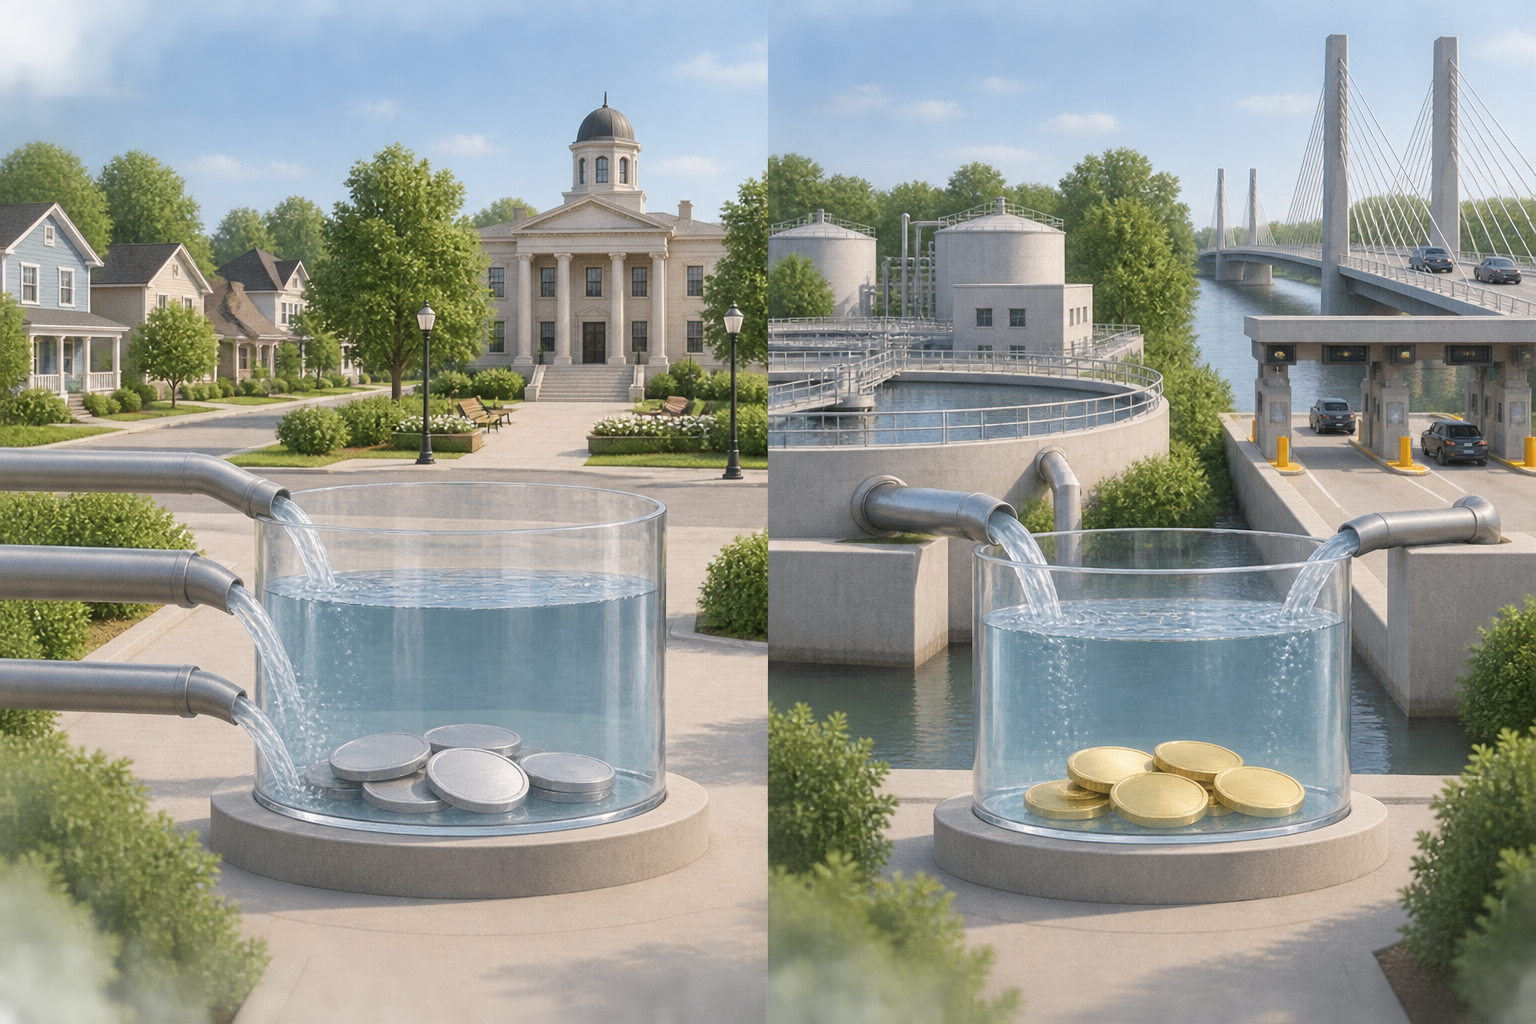
“General obligation” and “revenue” describe broad repayment structures for U.S. municipal bonds. A general-obligation (GO) bond commonly relies on a government issuer’s broader credit and legally available revenues, while a revenue bond relies on a source specifically pledged to debt service. The labels do not tell you every detail: the legal obligor, exact pledge, lien and payment priority, appropriation terms, guarantees, and applicable state or local law matter. Neither label makes a bond categorically safe, and a coverage ratio alone cannot predict default.
What a general-obligation pledge means
A GO bond is generally issued by a state or local government and backed by its “full faith and credit” and taxing power, subject to the pledge actually made and the issuer’s legal authority. The payment source can include general funds, property taxes, income taxes, or appropriations, depending on the issuer and governing law. Some local GO bonds rely primarily or solely on ad valorem property taxes; state GO debt may depend on legislative appropriations. Read the terms for the particular issue rather than assuming every GO bond uses the same tax or revenue stream. The MSRB’s repayment overview notes that the source and priority of payment can vary by issuer and state or local law.
“Full faith and credit” is not another name for a mortgage on every public asset, a promise that taxes can be increased without limit, or a federal guarantee. A GO label does not establish that the issuer has unlimited taxing authority. Tax limits, voter-approval rules, debt limits, budget processes, and remedies can depend on the state constitution, statute, charter, and offering documents. The SEC’s municipal credit-risk bulletin cautions investors to look beyond the GO shorthand and read the official statement to see which entity must pay and what authority supports the pledge.
The practical question is not simply “Is this a GO?” Ask which government entity promises payment, which revenues are legally available, whether a dedicated tax is involved, and what a holder can do if required payments are missed. A GO bond can have a strong, diversified revenue base, but it can also face fiscal stress, legal limits, weak finances, or competing obligations. The category alone does not settle credit quality.
What revenue bonds pledge
A revenue bond is generally payable from one or more identified revenue sources, without pledging the full faith and credit of a taxing government. The source might be charges from a water or sewer system, tolls, airport or port activity, lease payments, grants, or a specified excise or other tax. “Revenue” therefore does not always mean that users pay a fee directly to the project; a dedicated tax can also be pledged. The bond documents determine what enters the pledged fund and what can be used for debt service.
The pledge can be narrow. It may cover only a named facility, a whole utility system, a particular tax stream, or payments under another agreement. It may also exclude other issuer revenues. The MSRB explains that bondholders generally cannot compel the issuer to use taxes or appropriations that were not pledged to a revenue bond. If the pledged source is insufficient, the investor cannot assume that a city will voluntarily fill the gap from its general fund.
That limitation is not the same as saying every revenue bond is nonrecourse or that the underlying asset automatically transfers to bondholders after nonpayment. Recourse depends on the legal structure and documents. A project’s equipment, land, receivables, and operating cash may be treated differently. Read the pledge, any lien, covenants, remedies, and any separate guarantee instead of inferring them from “revenue bond.” The SEC likewise describes revenue bonds as varied structures whose specific revenue and recourse should be confirmed in the offering disclosure in its municipal-bond investor bulletin.
Separate the issuer, obligor, and pledged source
Three questions often get collapsed into one. The issuer is the governmental entity named in the securities offering. The obligor is the entity legally responsible for making the scheduled payments under the transaction documents. The pledged source is the revenue, tax, appropriation, or other payment stream that the documents make available for those payments. In a simple city GO issue, the city may be both issuer and obligor. In a conduit issue, the issuer and ultimate borrower can be different entities.
Consider a public authority that issues bonds to finance a nonprofit hospital. The hospital may agree to make loan payments to the authority or trustee, and those payments may be pledged to bondholders. The authority can be the bond issuer while the hospital is the underlying obligor. Unless the bond terms provide another pledge or guarantee, the authority may not have to pay from its own general resources if the hospital fails to pay. The SEC’s credit-risk bulletin specifically advises investors to identify the issuer or other obligor and understand which revenues are pledged.
A trustee that receives and distributes cash is not automatically the credit obligor. Nor does a government’s name on the front page by itself show that its taxpayers back the debt. Look in the official statement and related loan, trust, and indenture documents for the borrower, obligated person, guarantors, and source of payments. If there are several obligors, determine whether liability is joint, several, limited to a specific payment, or conditional on another event.
A hypothetical water-system bond shows what coverage can tell you
Assume, purely for illustration, that a municipality’s water utility issues a revenue bond with annual debt service of $3.6 million. Suppose the indenture-defined net revenues pledged to debt service are $5.4 million after the expenses and adjustments specified by those documents. A simple coverage calculation is:
$5.4 million ÷ $3.6 million = 1.50×
In this hypothetical, the defined pledged revenues are 1.5 times that year’s debt service. If they instead fell to $3.0 million, the same arithmetic would be $3.0 million ÷ $3.6 million = 0.83×. That signals that the assumed revenue amount would not cover the assumed debt service for that period without another permitted source, reserve, or action. It does not, by itself, establish a payment default, a covenant breach, or what remedy follows.
The example omits actual bond terms, timing, reserves, rate-setting powers, senior expenses, other debt, and future changes in demand or operating costs. “Net revenue” can have a contract-specific definition. Some documents require certain operating costs to be paid before calculating funds available for debt service; others define deposits and transfers differently. A coverage covenant may use historical results, forecast revenues, a particular fiscal period, or adjustments specified in the indenture. Always use the issue’s stated formula rather than treating one ratio as a universal threshold.
Coverage is one piece of evidence about cash flow relative to scheduled debt service. It does not measure every risk, prove the issuer can or will raise rates, account for all future capital needs, or predict whether the borrower will default. The SEC’s guidance also points readers to the underlying obligor’s financial statements, economic conditions, other liabilities, project assumptions, and statutory limits—not a single metric.
Lien priority and covenants change where cash goes
Even when two bonds pledge the same system’s revenue, they may not have the same claim on it. A senior lien may have priority over a subordinate lien under the documents. A flow-of-funds covenant might specify which operating expenses, debt-service deposits, reserve replenishments, or other transfers occur first. These are contractual priorities within a defined financing structure; they are not a universal ranking that can be inferred from the project name.
Ask whether the bond is secured by gross revenues, net revenues, a particular tax, a lease payment, or a loan repayment, and identify permitted deductions before debt service. Find out whether other bonds share the pledge equally, rank ahead of it, or are junior to it. A “first lien” label is only as useful as the definition of the collateral or revenue pool and the documents that establish priority. A senior lien can still be exposed to weak revenues, legal disputes, operational problems, or claims not covered by its lien.
The MSRB’s investor questions guide encourages investors to ask both where repayment comes from and which obligations have payment priority. It also flags whether payment depends on an annual appropriation. These questions matter for GO and revenue bonds alike: identify the source first, then follow the legal path that applies the cash to debt service.
Special taxes, double-barreled pledges, and appropriation terms
Some structures sit between a simple GO-versus-project-revenue comparison. A special-tax bond may pledge a dedicated sales, excise, or other specified tax. That source may be broader than one facility’s user charges but narrower than all general revenues. Its resilience depends on the tax base, collection and enforcement provisions, statutory limits, and the bond documents.
A double-barreled bond combines a defined revenue pledge with a GO pledge from a government that has taxing power. The second pledge can provide another legal source of payment, but its scope, priority, and remedies still depend on applicable law and the issue terms. Do not assume that every named “double-barreled” bond gives a holder the same powers or eliminates fiscal risk. The MSRB describes this structure as having both a revenue and GO pledge.
A bond subject to annual appropriation depends on a legislative body appropriating funds for payment in each relevant period. That feature is different from an unconditional, continuing pledge of all legally available resources. The consequences of a non-appropriation—including whether it is a default, termination, or other event—depend on the documents and governing law. Likewise, a moral-obligation provision may ask a legislature to consider support without legally requiring it to appropriate funds. The MSRB distinguishes that nonbinding mechanism from a GO pledge. Treat these terms as specific legal features, not as informal synonyms for a government guarantee.
Conduit financing and tax status answer different questions
In a conduit financing, a state or local issuer sells bonds to fund a loan or project for a separate borrower, such as a nonprofit hospital, college, housing entity, or business. The borrower’s payments may be the only pledged source. The government issuer may serve an administrative or public-purpose role without guaranteeing the borrower’s debt. Some conduit issues are nonrecourse; others may include limited or third-party support. The actual answer comes from the documents, not the issuer’s public name or the facility’s public benefit.
Credit enhancement adds another possible layer. Bond insurance, a bank letter of credit, a state program, or a parent guarantee may provide a secondary payment source, but the terms and provider’s credit matter. A guarantee is not automatically a pledge of every guarantor asset, and an enhancement does not erase weaknesses in the primary obligor. Check whether the support covers principal, interest, tender obligations, or only specified events, and whether it is current and enforceable.
Tax treatment is a separate axis. A municipal bond can be tax-exempt, taxable, or subject to the alternative minimum tax for a taxpayer who owes AMT. Those labels concern how interest is treated for tax purposes; they do not say whether payment comes from taxes, a utility system, a conduit borrower, or a combination. The MSRB’s taxable-municipal-bond guide explicitly separates tax status from the bond’s features and risks. Check the issue’s tax disclosure and the applicable U.S. federal, state, and local rules separately from its repayment structure.
Read the official statement before comparing bond labels
Start with the official statement, commonly available through the MSRB’s EMMA system. Confirm the issuer, obligor or obligated person, and any conduit borrower or guarantor. Then find the exact source of repayment, the breadth of the pledge, any lien, its priority, and the permitted flow of funds. Look for annual appropriation conditions, tax or voter limits, rate-setting authority, reserves, covenants, and remedies. The SEC notes that an official statement gives issue terms, credit information, and risk factors; the MSRB’s seven-question guide points to the same document for repayment source and payment priority.
Next, examine whether the pledged source is financially capable of meeting debt service under realistic conditions. For a revenue bond, that can mean studying historical collections, customer concentration, operating costs, capital spending, rate changes, and competing claims. For a GO bond, review the issuer’s financial condition, legally available revenues, debt burden, tax base, and constraints on raising or reallocating funds. A rating or a coverage ratio can be useful context, but neither substitutes for the documents and underlying financial analysis.
Finally, keep credit structure separate from other bond features. Federal tax status, maturity, call provisions, market price, liquidity, and the investor’s own jurisdiction can affect a bond without changing its core repayment pledge. For related mechanics, see the municipal tax-equivalent-yield guide, the clean-price and dirty-price guide, and the individual bonds versus bond funds guide. This article explains general U.S. concepts; it is not legal, tax, or investment advice about a specific issue.
Common questions
Q1Are general-obligation bonds always safer than revenue bonds?
No. The labels describe broad repayment structures, not a universal safety ranking. A GO bond depends on its issuer’s actual legal pledge, resources, and constraints. A revenue bond depends on its pledged source, obligor, lien, covenants, and recourse. Review the issue documents and financial information.
Q2Does a revenue bond have to be repaid only from fees charged by the project?
No. Pledged revenues may include system or project receipts, grants, lease or loan payments, or specified taxes. The bond documents define the source and whether any other payment support exists.
Q3Does a 1.50× debt-service coverage ratio mean a bond cannot default?
No. It is a calculation based on a defined period and revenue measure. Future cash flow, covenant definitions, reserves, other claims, legal constraints, operating conditions, and payment remedies also matter. A ratio alone is not a default forecast.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What is the most useful first question when a municipal bond is labeled a revenue bond?
Choose an answer to see the explanation