

Municipal Bond Tax-Equivalent Yield: Formula, AMT, and Risk
Compare U.S. municipal and taxable bond yields with a tax-equivalent yield, and see where state taxes, AMT, calls, and credit risk change the comparison.
In this guideWhat tax-equivalent yield answers
Short summary
Tax-equivalent yield (TEY) estimates the pre-tax yield a taxable bond would need to match the after-federal-tax interest from a qualifying tax-exempt municipal bond. In the simplified federal-only case, TEY = tax-exempt yield ÷ (1 − marginal federal tax rate). It is a comparison threshold, not a forecast or a risk-adjusted return. The result depends on the bond’s actual tax status, the investor’s tax situation, the yield measure used, and state and local rules.
What tax-equivalent yield answers
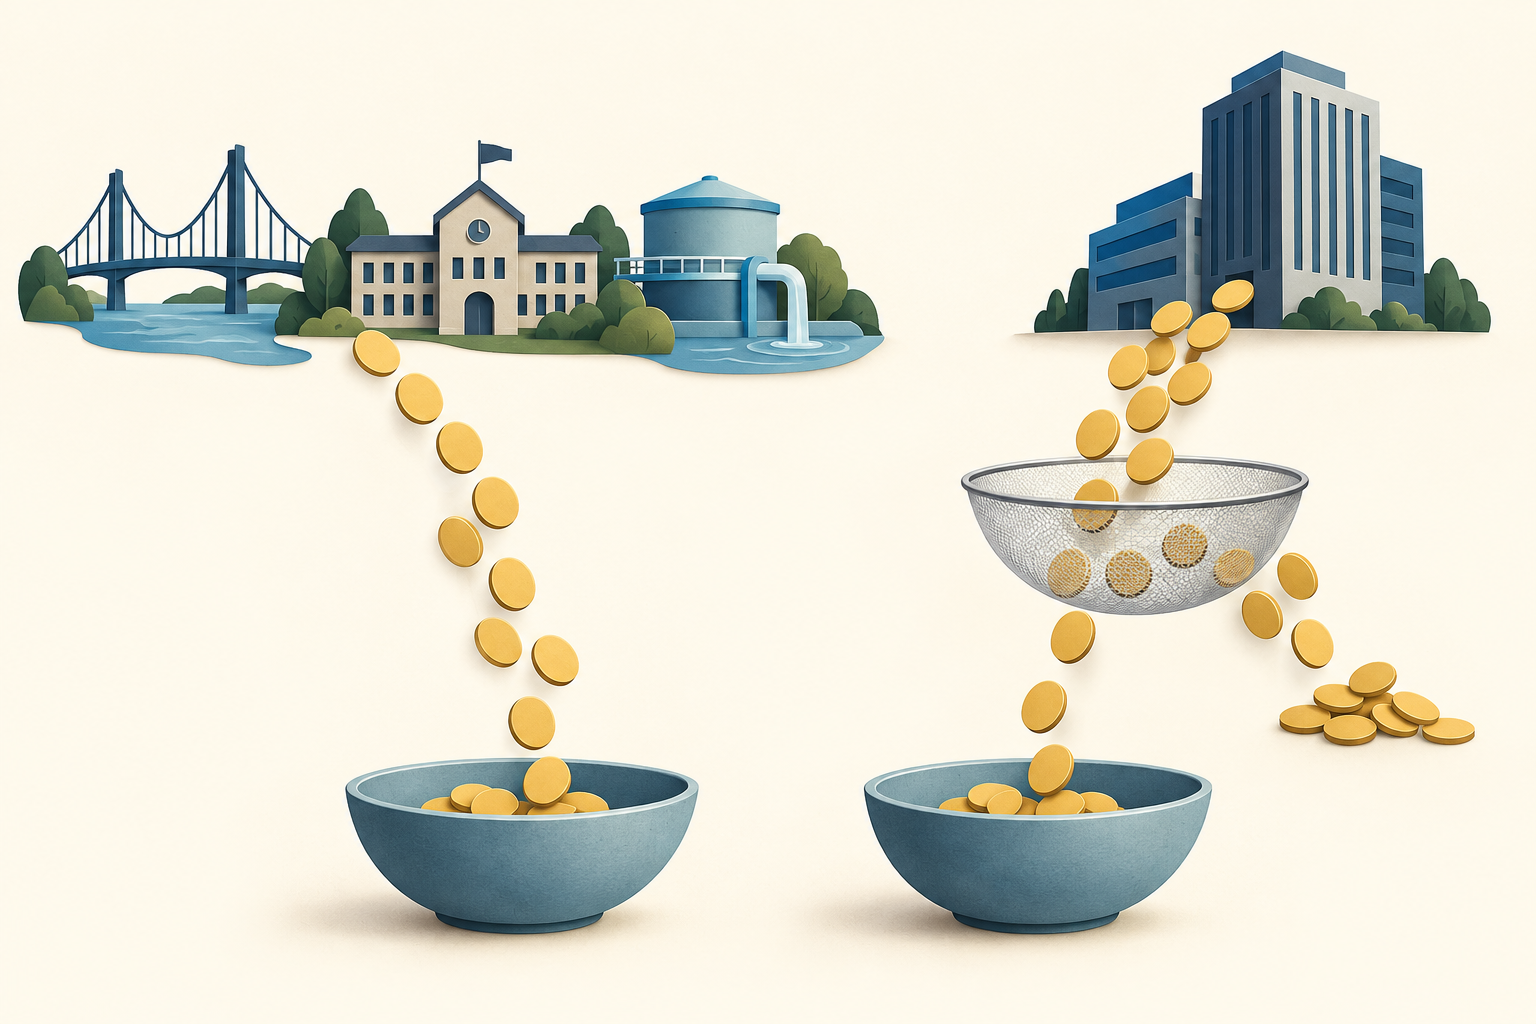
A municipal bond is debt issued by a state or local government or an entity acting for one. A qualifying issue can pay interest that is generally excluded from federal gross income, while a taxable bond’s interest is included. Because the tax treatment differs, a lower nominal municipal yield can still leave an investor with similar after-tax interest. TEY converts the exempt yield into a taxable-yield comparison under stated assumptions.
The calculation answers a narrow question: what taxable yield would leave the same amount of interest after the assumed tax? It does not rank bonds by expected total return, credit quality, price stability, liquidity, or suitability. A 4% TEY does not mean the municipal bond pays 4%, nor does it mean the bond is as safe as a Treasury. The bond still has its own coupon, price, call terms, and repayment source.
Verify the bond’s federal tax status first
“Municipal” describes the issuer or financing structure; it does not by itself tell you how every payment is taxed. The IRS Publication 550 says interest on state and local obligations is generally not taxable, but it also describes taxable obligations and exceptions. The MSRB’s tax-status guide separates federally tax-exempt, federally taxable, and AMT-subject issues. Check the official statement and tax-status disclosure for the exact bond.
A bond can be exempt from regular federal income tax but still have interest relevant to the alternative minimum tax for some taxpayers. A taxable municipal issue may owe regular federal tax while receiving different state treatment. State and local treatment can depend on where the investor lives, where the bond is issued, and local law. General-obligation and revenue bonds also have different repayment sources; the tax label says nothing about whether the issuer can pay.
Calculate a federal-only taxable-equivalent yield
For a simplified comparison in a taxable account, let m be the municipal bond’s tax-exempt yield and t the marginal federal tax rate applied to comparable taxable interest. The taxable bond keeps approximately y × (1 − t) after that federal tax. Setting it equal to m gives: TEY = m ÷ (1 − t). This uses a marginal rate, not the investor’s average tax rate.
Suppose a municipal bond has a hypothetical 3.00% yield and the assumed marginal federal rate is 24%. With no state or local tax effect and no AMT, TEY = 3.00% ÷ (1 − 0.24) = 3.00% ÷ 0.76 = 3.947%, or about 3.95%. The break-even taxable yield is therefore about 3.95% under those assumptions. A comparable taxable yield of 4.10% leaves about 4.10% × 0.76 = 3.116% after federal tax; 3.80% leaves about 2.888%. Those arithmetic comparisons exclude price changes, costs, state taxes, AMT, and differences in risk.
The MSRB’s illustrative example uses a 3.00% exempt yield and a 37% federal bracket to show a 4.76% taxable equivalent. The bracket is part of that example, not a recommended rate for a reader. Substitute a rate that actually applies to the relevant income and tax year, and verify the bond’s exemption first. Changing only the assumed rate moves the threshold: 3.00% ÷ 0.78 is about 3.85% at 22%, while 3.00% ÷ 0.68 is about 4.41% at 32%. These are sensitivity illustrations, not statements of current brackets or a complete tax calculation. The formula compares interest taxation; it does not calculate deductions, other income, or AMT. The marginal rate is the rate on the next dollar of ordinary taxable income, not total tax divided by total income. If added interest crosses a bracket threshold, part of it may face a different rate; a one-rate TEY then becomes a simplification. Use a fuller tax calculation when the income spans rate bands or other tax rules apply.
Compare the same kind of yield on both bonds
A coupon is the contractual interest rate applied to face value; it is not the bond’s current market yield. A bond’s yield to maturity (YTM) reflects its price and scheduled cash flows under assumptions about payment and reinvestment. For a callable municipal bond, yield to call (YTC) uses a call date and call price. FINRA explains that yield to worst (YTW) compares applicable YTM and YTC outcomes and is still an estimate, not realized total return.
Use a consistent yield basis on the municipal and taxable alternatives. If the municipal bond can be called in five years, comparing its coupon with a noncallable corporate bond’s YTM can hide important differences. A $1,000-par bond with a 4% coupon pays $40 a year; at a $1,050 purchase price, its simple current yield is $40 ÷ $1,050, or about 3.81%. That ratio ignores principal repayment and call timing, so it is not YTM or YTW. Use the same settlement date, market-price convention, call assumptions, and tax treatment where possible. Even then, TEY does not adjust for different credit, liquidity, duration, or option risk. A higher calculated threshold cannot make two unlike bonds economically identical. TEY also is not an investor’s realized after-tax annual return. Yield quotes summarize assumed cash flows; an investor’s result depends on coupon dates, reinvestment, purchase and sale prices, holding period, taxes, and costs. A return calculation needs those actual cash flows rather than the TEY formula alone.
State taxes and account type can change the relevant rate
The worked example deliberately ignores state and local taxes. Some states exempt interest on bonds issued within the investor’s home state; other states tax some or all out-of-state municipal interest, and the rules vary. A taxable alternative may also receive different state treatment. Do not automatically add a federal bracket and a state bracket: the effective tax cost depends on the applicable law, deductions, and the investor’s circumstances. Recalculate using the tax treatment that actually applies to each bond. For example, a resident might receive a state exemption on an in-state issue but owe state tax on an out-of-state issue. A national municipal fund can hold both, so its name alone does not establish the state tax result. Use the fund’s annual state-allocation information and the investor’s own filing rules.
The account matters too. In a taxable account, exempt interest may avoid current federal tax when it qualifies. In a tax-deferred account such as a traditional 401(k), taxable bond interest is generally not taxed in the year received, so the simple TEY formula does not capture the account’s later withdrawal treatment. The MSRB notes that investors should consider the account as well as the security. Compare the whole account-level treatment rather than assuming tax-exempt interest automatically wins.
AMT, reporting, and municipal bond funds
Some interest from specified private activity bonds may be an AMT preference item. The 2025 Instructions for Form 6251 describe specified private activity bond interest and exceptions; the issuer or fund reporting may show an AMT-related amount in Form 1099-INT box 9 or Form 1099-DIV box 13. That disclosure does not mean every investor owes AMT: whether AMT applies is a taxpayer-level calculation. The reported preference item enters a broader tentative-minimum-tax calculation with exemptions and other adjustments; box 9 alone does not show an AMT bill or change the bond’s regular-tax status. Use the applicable year’s form instructions and the issue documents.
Tax-exempt interest is still reportable. Publication 550 explains that it generally appears on Form 1040 line 2a; reporting it does not make it taxable. Form 1099-INT box 9 is included in box 8, and Form 1099-DIV box 13 is included in box 12; do not count the AMT amount twice when reading the statement. Also separate a bond’s interest from its sale proceeds. A sale can create a taxable capital gain or loss, and market discount on a tax-exempt bond is not automatically tax-exempt. For example, buying at $95 and later selling at $98 does not make the entire $3 increase tax-exempt interest; the tax character depends on the purchase history and applicable market-discount rules. Distinguish original-issue discount (OID) from market discount acquired in the secondary market. Publication 550 treats OID on qualifying tax-exempt state and local bonds as tax-exempt interest but states that market discount on a tax-exempt bond is not tax-exempt. The price increase alone is not enough to classify the tax result.
A municipal-bond fund adds another layer. Its exempt-interest dividends depend on the fund’s holdings and tax reporting; Investor.gov’s bond-fund guide cautions that not all fund income is necessarily exempt from federal or state tax. Review the fund’s tax supplement and distribution breakdown instead of applying one individual bond’s status to every fund payment. Tax character can vary with the fund’s holdings and distributions during the year. A fund name, stated objective, or last year’s state-allocation percentage does not certify this year’s payout. Use the fund’s tax supplement for the relevant year after the final distribution information is available.
Tax advantages do not remove bond risks
Municipal bond prices can fall when market yields rise. Issuers may call some bonds before maturity, changing the cash-flow path and reinvestment opportunity. Credit risk depends on the issuer or underlying revenue source: a general-obligation bond and a toll-road revenue bond do not rely on the same repayment mechanism. A high credit rating is not a guarantee against missed payments. Individual municipal issues may also trade infrequently, so a quoted price may not be an executable sale price. Investor.gov describes call, credit, interest-rate, inflation, and liquidity risks for municipal bonds.
Tax treatment can also differ across parts of the return. Qualifying interest may be federally exempt, while a sale gain, market discount, or some distributions can be taxable under separate rules. Taxes do not offset a price decline automatically. A TEY comparison is therefore one input alongside call schedule, maturity, yield-to-worst, credit disclosure, trading costs, and the investor’s cash-flow needs. Consider a $100-par bond bought for $105 and sold for $97 before maturity: the $8 price decline is already a loss before coupons and costs are counted. A tax-equivalent interest calculation cannot prevent or offset that market-price move. Selling can also create a separate tax result, so evaluate the actual cash flows and tax basis.
A practical comparison sequence
Start with the account and the tax year, then identify the exact security rather than relying on a “muni” label. Read the official statement for federal tax status, AMT disclosure, state and local treatment, call schedule, repayment source, and other material terms. For a fund, use its current tax supplement and holdings-related disclosures.
Next, select the same yield measure for both alternatives—often YTW when the bonds are callable—and record the settlement date and price basis. Apply the federal-only formula only if its assumptions fit. Add state and local effects only after checking their actual treatment, and do not use the simplified formula when AMT or account-level tax rules change the comparison.
Finally, compare what the formula leaves out: credit quality, duration, call risk, liquidity, bid–ask spread, costs, reinvestment assumptions, and the amount of principal that may be returned early. The Investor.gov municipal-bond overview discusses bond types and risks. The TEY calculation is a screening comparison, not an individualized tax conclusion or a bond recommendation.
For related yield measures, read the why corporate-bond yields can rise when Treasury yields fall and the SEC-yield versus distribution-yield guide.
Common questions
Q1Is all municipal-bond interest exempt from federal income tax?
No. Interest on qualifying municipal obligations is generally exempt, but some obligations are taxable and some specified private activity bond interest may be relevant to AMT. Check the issue’s tax disclosure and the rules for the applicable year.
Q2Does a 3.95% tax-equivalent yield mean the municipal bond pays 3.95%?
No. It is a hypothetical taxable-yield threshold calculated from the muni yield and an assumed tax rate. The bond pays according to its own coupon and cash flows; market price, call terms, and taxes can change the result.
Q3Can I owe tax when I sell a tax-exempt municipal bond?
Possibly. Tax-exempt treatment of qualifying interest does not automatically exempt a sale gain or market discount. The tax result depends on purchase price, sale price, holding period, and applicable rules.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
A qualifying municipal bond has a hypothetical 3.00% yield. With a 24% assumed marginal federal rate and no state-tax or AMT effect, what is its simple federal-only TEY?
Choose an answer to see the explanation
Options glossary
The portion of premium above intrinsic value, reflecting remaining time, expected uncertainty, rates, dividends, and supply and demand.
Read the deeper guideGammaAn estimate of how much delta may change for a small move in the underlying, all else equal; it often becomes more concentrated near expiration and near the money.
Read the deeper guide