

Seigniorage vs. Inflation Tax: How Money Creation Transfers Real Resources
Learn what seigniorage measures, how it differs from the inflation tax, and why money creation, central-bank profit, and government revenue are not interchangeable.
In this guideWhat does seigniorage mean?
Short summary
Seigniorage is the real resource value associated with issuing money, but economists use more than one definition. The “inflation tax” describes lost purchasing power on existing money balances as prices rise; it is not a bill sent to households, and it is not automatically the same as central-bank profit or government revenue.
What does seigniorage mean?
When a currency issuer creates a monetary liability and uses it to acquire an asset or pay for something, it can command real goods and services without first collecting an ordinary tax or borrowing with an interest-bearing bond. Economists call the resulting resource measure seigniorage. One common flow measure is the change in nominal money divided by a price index, written as S = ΔM / P. Here, M is a defined money stock and P is the price level used to convert nominal amounts into purchasing power. The measure depends on which liabilities count as money and how the period is timed. {source:imfFiscalAccountsSeigniorage}
New currency is not free real income merely because its face value is printed on a note. Issuing money creates a liability for the issuer. What matters is the purchasing power received in exchange, the return on assets acquired, the cost of issuing and maintaining the money, and the value of any interest paid on the liabilities. For a broader overview of the monetary aggregates behind these measures, see the guide to the monetary base, M1, and M2.
Why are there several measures of seigniorage?
The term is not uniquely defined across accounting and economic analysis. A resource-flow approach measures the real value of new money issued. A central-bank income approach may instead measure interest or other returns earned on assets funded by monetary liabilities, less interest costs and operating expenses. A narrower historical or coin-issuing definition can mean the difference between a coin’s face value and its production cost. Those quantities can move differently and should not be compared as though they were one standard statistic. {source:imfSeigniorageInflationTax} {source:ecbSeigniorageBroadDefinition}
The European Central Bank offers a concrete, euro-area-specific example: its explainer describes income earned on assets acquired or lending associated with banknote issuance. A more recent ECB paper also explains that some analyses use a broader definition covering reserves and other central-bank liabilities, with their remuneration and matched assets. These are examples of different measurement boundaries, not universal legal definitions for every country. {source:ecbSeigniorageExplainer} {source:ecbSeigniorageBroadDefinition}
How is the inflation tax different?
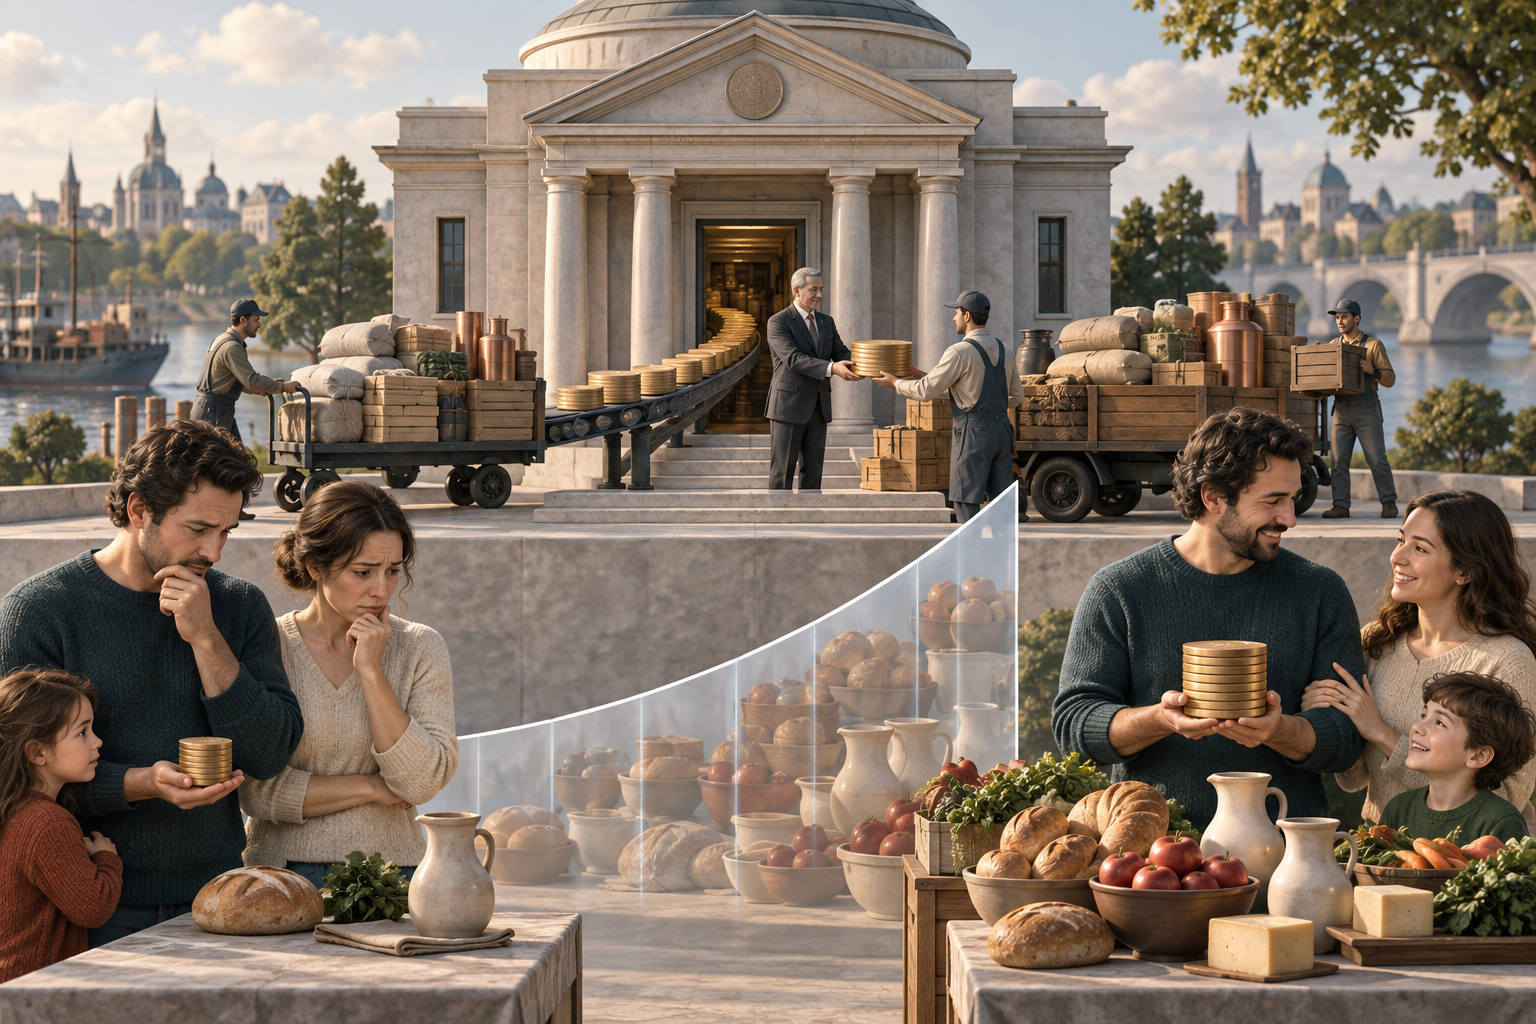
The inflation tax is the decline in the real purchasing power of money balances that people already hold when the price level rises. “Tax” is a metaphor for this implicit loss: a household does not receive a tax notice, and the loss does not map one-for-one to a government’s cash receipts. In a standard money-demand decomposition, seigniorage can include both growth in desired real money balances and an inflation-tax component. Some sources use the terms more loosely, so check the definition. {source:imfFiscalMonitorSeigniorage} {source:imfSeigniorageInflationTax}
If economic activity grows and people willingly hold more real money for transactions, the monetary base can expand without an equivalent loss of purchasing power. That increase in real balances is often called “pure seigniorage.” The inflation-tax component instead reflects inflation eroding the real value of existing balances. The two are related, but neither term means that all price increases are a tax collected by the treasury. {source:imfFiscalMonitorSeigniorage}
What does a simple example show?
Suppose the price index starts at 1.00 and the monetary base is 1,000 nominal units. Its real value is 1,000 units. If the price index rises by 10% to 1.10 while the nominal base stays at 1,000, the real balance falls to about 909.09. The existing balance has lost about 90.91 units of purchasing power. That is an illustration of inflation erosion, not a tax invoice.
In a deliberately simplified one-period example, suppose the issuer creates 100 additional nominal units, so the base becomes 1,100 at the new price index of 1.10. The extra money is worth about 90.91 in current purchasing power (100 / 1.10). That matches the erosion just calculated under these assumptions. The match is not a universal identity for observed data: it relies on the timing, money-demand, price-index, interest, and cost assumptions in this example. The calculation is hypothetical, not a country estimate. {source:imfFiscalAccountsSeigniorage} {source:imfFiscalMonitorSeigniorage}
The issuer obtains real resources only through the transactions made with the new liabilities. The 100-unit face value is not itself 100 units of real revenue at the higher price level, and an increase in money alone does not prove that the budget received spendable cash. {source:imfGfsm2014}
How do growth and money demand change the picture?
The amount of money people want to hold changes with real incomes, payment technology, banking access, interest rates, and confidence in the currency. If real money demand grows, a larger monetary base can be absorbed without the same inflation pressure. If holders try to reduce their local-currency balances as inflation rises, the base supporting an inflation tax can shrink. For that reason, seigniorage is not a fixed percentage of GDP or a stable revenue source that can be extrapolated from one year. {source:imfFiscalMonitorSeigniorage} {source:imfSeigniorageInflationTax}
The result also depends on whether the statistic uses currency, bank reserves, or a broader money stock. Interest paid on reserves or deposits changes the cost of monetary liabilities; in a broader net-income measure, that can reduce seigniorage. A quantity-based measure and a central-bank income measure may therefore give different answers for the same period. {source:ecbSeigniorageBroadDefinition}
Is seigniorage the same as central-bank profit or government revenue?
No. Central-bank profit can include asset income, interest expenses, valuation changes, provisions, and operating costs. Seigniorage may be only one part of the result, depending on the definition. Any transfer of central-bank earnings to a treasury follows the country’s law and accounting rules; it can be limited, delayed, or absent. The ECB’s banknote-related measure is one institutional arrangement, not a template for every central bank. {source:ecbSeigniorageExplainer} {source:ecbSeigniorageBroadDefinition}
Government statistics may also classify currency issuance differently from ordinary tax revenue. The IMF’s Government Finance Statistics Manual treats seigniorage profits from issuing currency as implicitly included in currency-and-deposit transactions rather than recording them as revenue in the described framework. This accounting choice is a reason to avoid adding a seigniorage estimate to a reported fiscal revenue total without checking definitions. {source:imfGfsm2014}
Does money creation automatically cause inflation?
No single increase in base money mechanically predicts a matching increase in consumer-price inflation. The relationship depends on demand for money, bank lending and deposits, interest paid on reserves, output and supply conditions, expectations, and the policy framework. A central bank can create reserves as part of its operating framework without that amount immediately becoming household spending. Persistent monetary financing that outruns demand for money can add inflation pressure, but seigniorage itself is not an inflation forecast. For the related question of fiscal constraints on monetary policy, see the guide to fiscal dominance. {source:imfFiscalMonitorSeigniorage} {source:ecbSeigniorageBroadDefinition}
How should you read a seigniorage estimate?
Before comparing figures, write down the measure: real change in a specified money stock, currency-issue profit, or net income on assets funded by monetary liabilities. Then check the price index and conversion date, whether reserves are included, how interest paid on money is treated, and whether issuance costs or valuation changes are deducted. Also check whether the source reports central-bank income, a fiscal transfer, or a broader resource measure. A statistic’s label alone does not make those quantities interchangeable. {source:imfFiscalAccountsSeigniorage} {source:imfGfsm2014} {source:ecbSeigniorageBroadDefinition}
A seigniorage figure does not replace the ordinary budget balance or public-debt stock. Read the guide to the budget deficit versus national debt for that distinction, and the guide to headline versus core inflation for how price indexes summarize changing prices. Neither a single seigniorage measure nor a single inflation rate tells you the full fiscal or monetary-policy story.
Common questions
Q1Is seigniorage always the same as the inflation tax?
No. The inflation tax usually refers to erosion of real money balances by inflation. Seigniorage can also include the real value of money growth that meets higher demand for real balances, and some sources define both terms differently.
Q2Does seigniorage always become government revenue?
No. The central bank may earn income from issuing money, but remittances to government depend on legal, accounting, and balance-sheet rules. Fiscal statistics may classify money issuance as a financial transaction rather than tax revenue.
Q3Does creating money always cause consumer-price inflation?
No. The effect depends on money demand, bank and central-bank balance sheets, interest paid on liabilities, output, expectations, and policy arrangements. A money-creation measure by itself is not an inflation forecast.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
The price index rises while a household’s nominal cash balance stays unchanged. What does the inflation-tax phrase describe in this example?
Choose an answer to see the explanation