

M1 vs. M2 vs. the Monetary Base: What Each Measure Counts
Compare U.S. M1, M2, and the monetary base, including the 2020 M1 reclassification, 2026 H.6 revisions, bank reserves, and stablecoins.
In this guideWhat do M1, M2, and the monetary base count?
Short summary
In the Federal Reserve’s U.S. H.6 statistics, M1 counts currency held outside bank vaults and several kinds of liquid deposits; M2 adds small time deposits and retail money-market-fund balances, after an IRA/Keogh deduction. The monetary base instead counts currency in circulation, including bank-vault cash, plus banks’ reserve balances at the Fed. They measure different balance-sheet boundaries, so one does not mechanically multiply into another.
What do M1, M2, and the monetary base count?
The Federal Reserve publishes monthly U.S. money-stock measures in its H.6 release. Under the current definition, M1 includes currency outside the Treasury, Federal Reserve Banks, and depository-institution vaults; adjusted demand deposits; and other liquid deposits. That last category includes savings deposits, including money-market deposit accounts, as well as NOW and ATS accounts, credit-union share drafts, and thrift-institution demand deposits.
M2 starts with M1, adds small-denomination time deposits (currently under $100,000) and retail money-market-fund balances, then subtracts IRA and Keogh balances held at depository institutions and money-market funds. The monetary base has a different perimeter: currency in circulation plus reserve balances that depository institutions hold in accounts at the Federal Reserve. H.6 provides the [current definitions and tables for these measures]({source:fedH6CurrentMoneyStockMeasures}).
The words “narrow,” “broad,” and “base” describe statistical groupings, not a ranking of economic importance. M1 and M2 are not counts of everyone’s wealth or all ways of paying. The monetary base is not the Fed’s total balance sheet. Each total depends on which institutions, accounts, and holders the definition includes.
A hypothetical example shows why the totals differ
Suppose one month’s invented figures are $300 billion of currency in circulation, of which $20 billion is bank-vault cash, and $500 billion of reserve balances. The monetary base is $300 billion + $500 billion = $800 billion. Public-held currency is only $280 billion because H.6’s base-currency component includes the $20 billion stored in bank vaults.
Now suppose the public has $1,520 billion in adjusted transaction and other liquid deposits. M1 is $280 billion + $1,520 billion = $1,800 billion. If small time deposits total $250 billion, retail money-market funds $400 billion, and the applicable IRA/Keogh deduction $50 billion, M2 is $1,800 billion + $250 billion + $400 billion − $50 billion = $2,400 billion.
Every amount here is invented to show the boundaries, not an observation or forecast. It assumes the same period and consistent definitions. The $280 billion of public currency overlaps conceptually with currency counted in the monetary base, but vault cash and reserve balances are not public M1 deposits. Do not add M1, M2, and the base together as if they were separate piles of money.
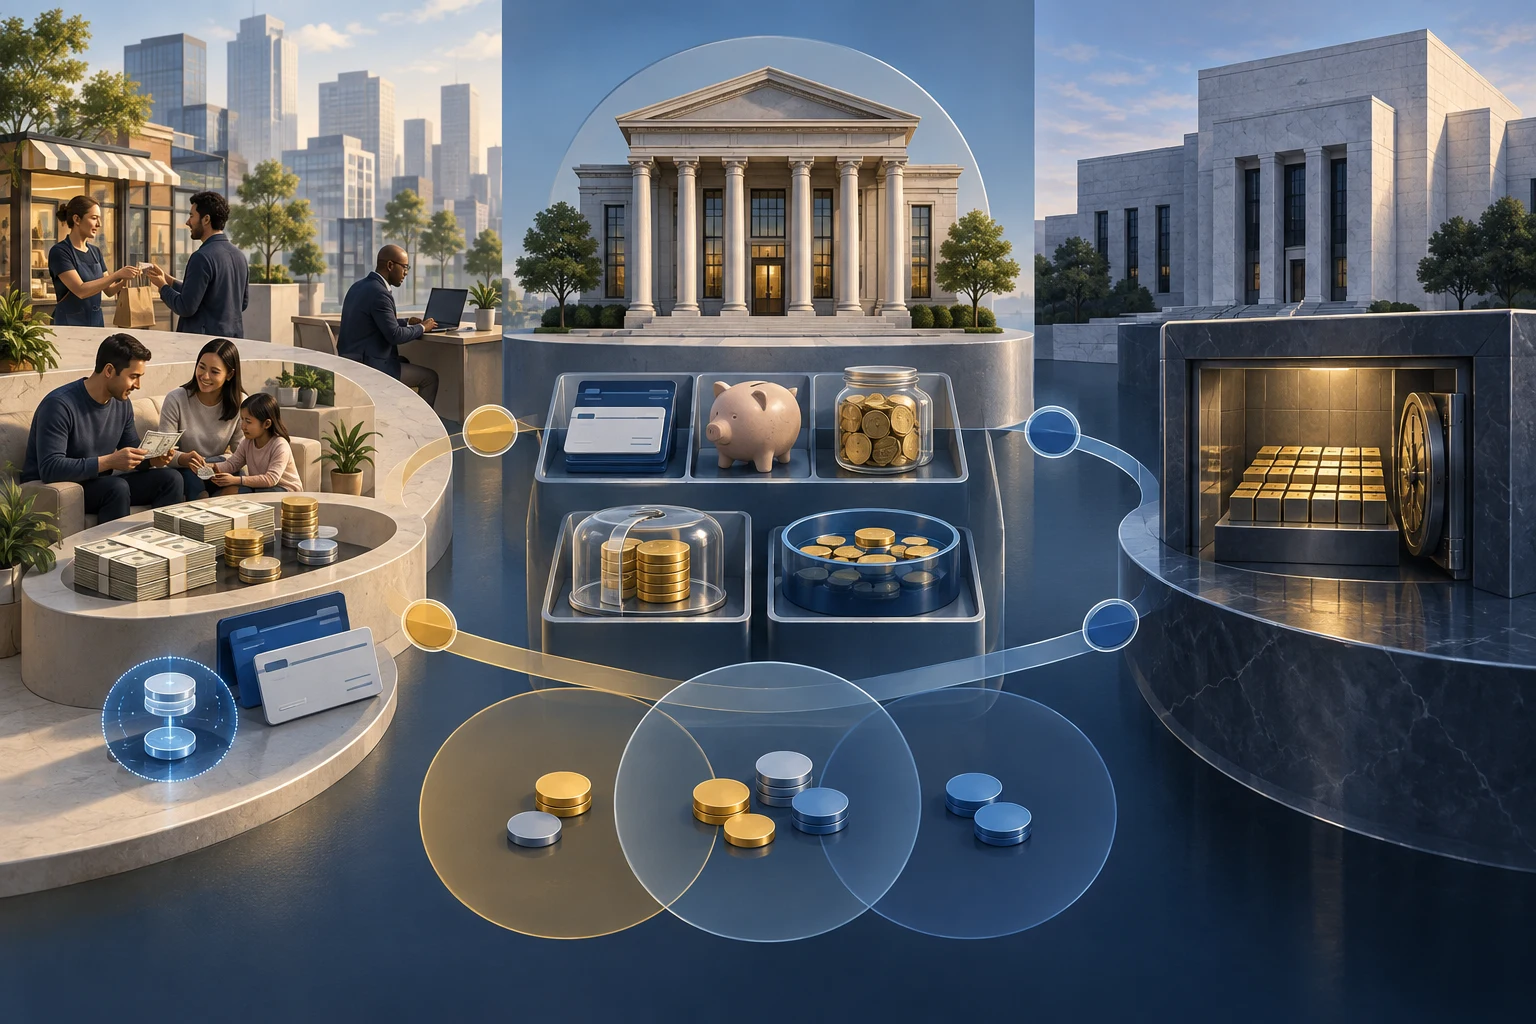
Why bank reserves are part of the base, not household M1
Reserve balances are assets of banks and liabilities of the Federal Reserve. A bank holds them in its Fed account to settle payments and manage liquidity; a household or business does not hold a reserve balance in its checking account. The Fed explains what reserve balances are and how it pays interest on them in its [IORB questions and answers]({source:fedIorbFaq}).
Currency also has two relevant boundaries. H.6 counts currency outside Treasury and Federal Reserve premises in the monetary base, which includes cash in depository-institution vaults. For M1, the currency component excludes bank-vault cash and captures currency held outside those institutions. This overlap means the base is not a category that can simply be added to M1, and the two totals do not have a fixed size relationship.
Nor is the monetary base a synonym for the Federal Reserve’s assets. The Fed can hold securities and other assets; H.6’s base counts currency and reserve balances on the liability side. When comparing a chart or news claim, check the series name and units rather than assuming every “Fed money” measure tracks the same thing.
The 2020 M1 jump was a reclassification
In April 2020, the Federal Reserve removed the six-per-month transfer limit on savings deposits. The definition change applies to the May 2020 observation, which the February 23, 2021 H.6 release added retroactively to the published history: savings deposits were included in M1 as other liquid deposits. The Fed’s technical Q&A describes an approximately $11.2 trillion statistical step-up in M1 from that change. M2 was not changed by the reclassification.
That jump does not mean $11.2 trillion of new money suddenly appeared in May. Much of the balance already existed in savings accounts; it moved into a broader M1 category because the classification changed. The distinction matters when a chart crosses May 2020: compare like definitions or use a revised series rather than reading the step as a sudden burst of lending or spending. The Fed’s [H.6 technical Q&As explain the 2020 change and its treatment]({source:fedH6TechnicalQAs}).
The change also helps explain why an older textbook shorthand—M1 equals cash plus checking accounts—does not describe the current U.S. series. The definition follows the published H.6 statistical framework, which can evolve over time. Always identify the country and data vintage before comparing a money-supply chart across decades.
M2’s 2026 IRA and Keogh calculation changed
M2’s components need a date and a methodological note too. Starting with the July 28, 2026 H.6 release, the Federal Reserve nets IRA and Keogh balances at the aggregate M2 level instead of subtracting them from the small-time-deposit and retail-money-market-fund components individually. The revised identity is M1 plus gross small time deposits plus gross retail money-market-fund balances, less total IRA/Keogh balances at depository institutions and money-market funds.
The nonseasonally adjusted total M2 was unchanged by that accounting presentation change. The displayed small-time-deposit and retail-MMF components rose because they were no longer netted separately; seasonally adjusted M2 received minor revisions. A reader can therefore see component series shift without a matching increase in the total. The latest [H.6 release and the technical Q&A]({source:fedH6CurrentMoneyStockMeasures}) show the current tables and explain the revision.
When tracking a component, note whether it is gross or net of retirement-account balances, seasonally adjusted or not, and which release vintage supplies the historical data. A component’s revised presentation is not by itself evidence that households newly deposited or withdrew the same amount.
Bank lending does not follow a fixed reserve multiplier
An often-repeated textbook story says a bank receives reserves, lends a fixed fraction, and thereby creates a predictable multiple of deposits. That is not a mechanical rule for the modern U.S. banking system. Reserves are settlement and liquidity assets; they are not a stock of funds that banks must lend out dollar for dollar to the public. A reserve balance can move between banks when customers make payments without changing the banking system’s aggregate reserve total.
When a bank makes a loan to a nonbank customer, it typically records a loan asset and credits the customer’s deposit liability at the same time. A deposit can also be created when a bank buys an asset from a nonbank. By contrast, a Federal Reserve purchase from a bank changes the bank’s asset mix and reserve balance but does not, by itself, create a new customer deposit. Subsequent spending, transfers to money-market funds, loan repayment, and payments abroad can change where deposits sit or reduce deposits in the U.S. banking system.
The Federal Reserve’s [deposit-growth research note]({source:fedBankDepositGrowthPandemic2022}) illustrates these accounting channels in its pandemic-period analysis; its historical estimates are not current measurements or a universal forecast. Bank lending depends on credit demand, borrower risk, capital, funding, regulation, profitability, and policy conditions. Reserve supply and interest paid on reserve balances matter to banks’ choices, but no constant “money multiplier” turns each reserve dollar into a set number of loans or M2 dollars.
Where tokenized deposits and stablecoins fit
Putting a bank deposit on a tokenized ledger does not automatically create a new monetary category. The Federal Reserve’s September 2026 staff note says tokenized deposits are already represented in traditional deposit measures; whether they fall in M1 or the portion of M2 outside M1 depends on the underlying deposit type. Tokenized money-market-fund shares are included in the retail-MMF component, not reported as a separate token category.
Payment stablecoins are not currently a separate component in the published H.6 aggregates. The staff note discusses possible future treatment: a stablecoin used mainly to store value might fit an M2 category outside M1, while one used widely for everyday payments might fit M1. Doing that well would require reliable issuance data, reporting standards, a decision about domestic versus foreign holders, and adjustments to avoid counting bank deposits or fund shares backing a token twice.
The September 4, 2026 [staff note on new forms of money and the U.S. aggregates]({source:fedNewFormsMoneyAggregates2026}) is independent research by its authors and explicitly is not part of Federal Reserve policy deliberations about the definitions. It describes measurement questions, not an adopted classification. For token pricing, redemption, and reserve risks, see the separate guide to stablecoin depegs and redemptions. The question here is how an official statistic classifies an instrument, not whether it will keep a peg.
How to read a money-supply chart
Start with the jurisdiction and series definition. This article uses U.S. H.6; other countries may use different account categories and labels. Then check the observation date, release date, unit, whether the line is seasonally adjusted, and whether later revisions changed its history. The Federal Reserve posts current M1 and M2 data monthly, while other base-related series may have their own frequency and release conventions.
Next, match the measure to the question. M1 and M2 describe selected liquid financial assets held by specified sectors. The monetary base describes currency and reserve balances. None is a direct measure of household net worth, total spending, the Fed’s assets, or the future rate of inflation. A rise in M2 alone does not establish that consumer prices will rise by a particular amount; velocity, output, credit conditions, expectations, and policy also matter.
Use a policy-rate guide when the question is how central-bank rates reach borrowing costs, such as the federal funds rate versus the prime rate. Use a price-index comparison when the question is how inflation itself is measured, such as CPI versus PCE and the GDP deflator. Keeping balance-sheet measures separate from prices and rates makes a chart easier to interpret without assigning it a causal story it cannot show on its own.
Common questions
Q1Is M0 the same thing as the monetary base?
Not always. “M0” is used differently across countries and textbooks. For U.S. data, use the Federal Reserve’s named H.6 monetary-base series and check its definition instead of assuming an informal label has one universal meaning.
Q2Do larger reserve balances automatically create more M2 or more bank loans?
No. A bank’s reserve balance supports settlement and liquidity, but there is no fixed mechanical multiplier that dictates how much it lends. Deposits can be created through bank lending, but lending also depends on customers, credit risk, capital, funding, and policy conditions.
Q3Are payment stablecoins included in today’s U.S. M1 or M2?
Current H.6 does not show payment stablecoins as a separate M1 or M2 component. The Fed staff note considers possible future classifications but is not policy. Some backing assets may already appear in deposits or money-market-fund data, so adding token supply without a double-counting adjustment would be misleading.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
Which item belongs to the monetary base but is not a public-held M1 deposit?
Choose an answer to see the explanation
Options glossary
Clear definitions of essential option terms, from calls, puts, and option chains to IV, Greeks, open interest, and max pain
Browse the options glossary