

Federal Funds Rate vs. Prime Rate: Who Sets Each and How Loans Use Them
Understand the FOMC's federal funds target, the bank-set prime rate, and how a variable loan APR can use an index plus a margin.
In this guideThese rates answer different questions
Short summary
The FOMC sets a target range for the federal funds rate, while the effective federal funds rate reflects overnight transactions and the prime rate is set by individual banks. Many banks adjust prime partly in response to the Fed's target, but a loan's APR changes only according to its own index, margin, and contract terms.
These rates answer different questions
The federal funds rate is an overnight rate in the market for loans between banks. The Federal Open Market Committee (FOMC) sets a target range to guide that market rate as part of U.S. monetary policy. The prime rate is a reference rate determined by individual banks and used in pricing some loans. The Federal Reserve summarizes the policy target in its [policy-rate overview]({source:fedPolicyRateOverview}) and explains [what prime is and whether the Fed sets it]({source:fedPrimeRateFaq}).
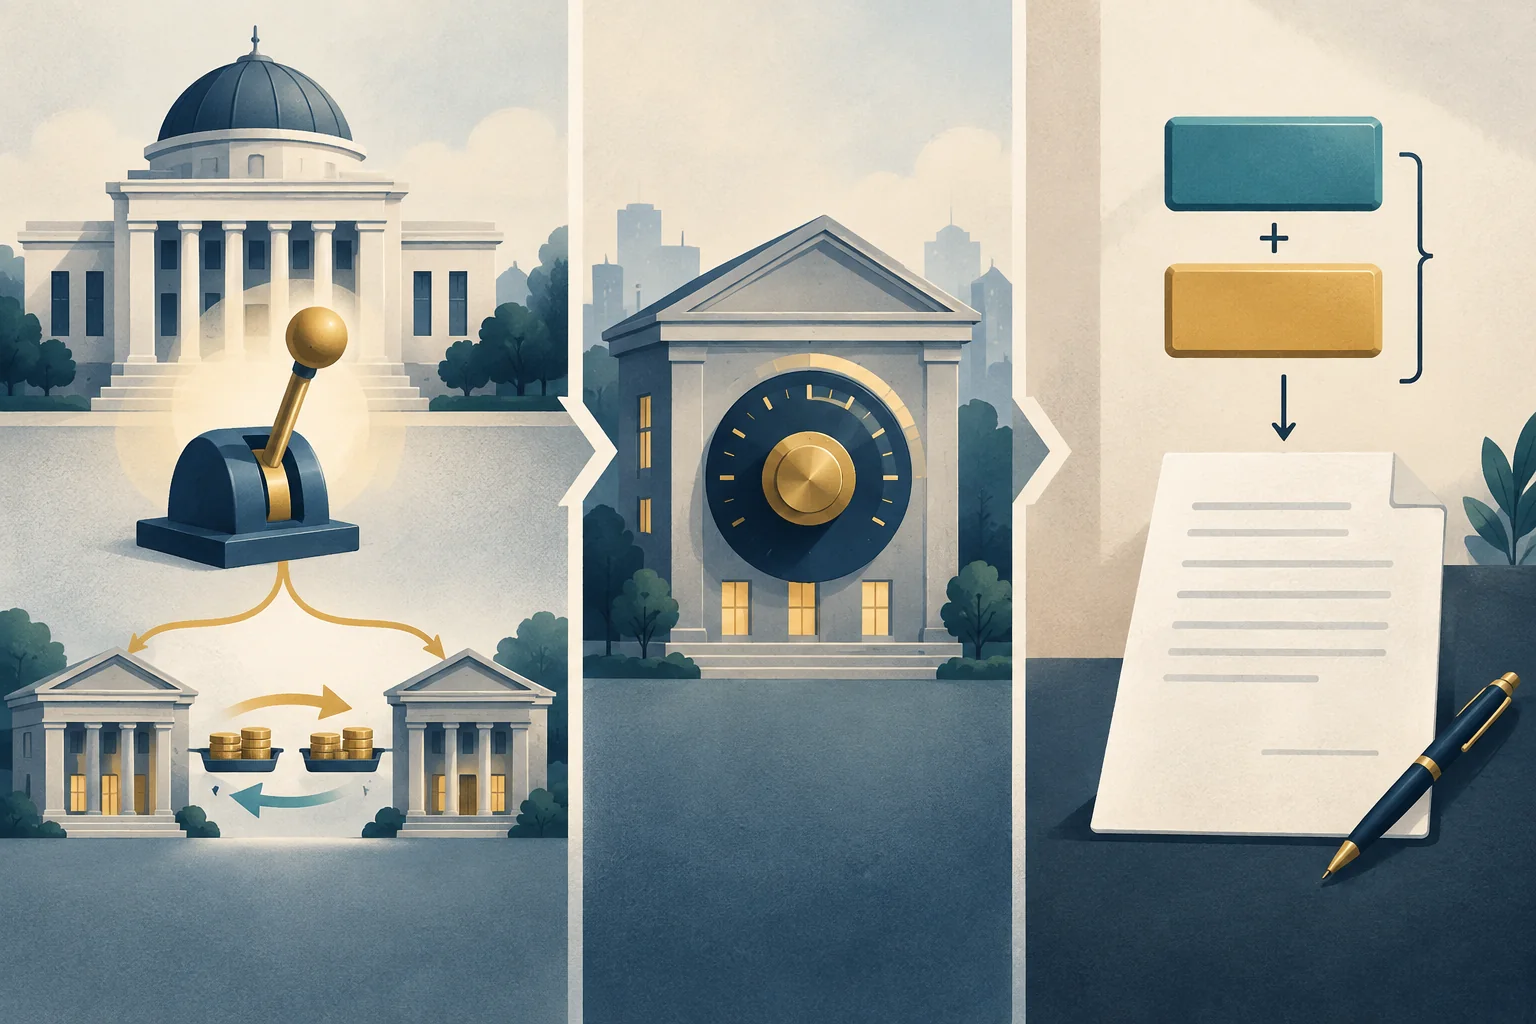
The key distinction is who sets or reports each number. The FOMC chooses a target range; the effective federal funds rate (EFFR) is calculated from observed overnight transactions; each bank decides its own prime rate. These rates are connected, but they are not three names for the same rate.
The FOMC target range is not the effective rate
The FOMC sets a target range for the federal funds rate rather than selecting the exact rate for every overnight transaction. The EFFR is a published measure of completed federal funds market transactions. The Federal Reserve's H.15 release describes the EFFR calculation as a volume-weighted median of transaction-level reports from depository institutions. It is an observed market rate, not the target range itself. See the current [H.15 methodology and rate series]({source:fedH15SelectedInterestRates}).
The Fed uses policy tools, including interest on reserve balances and the overnight reverse repurchase facility, to steer short-term market rates toward the target range. Its [policy-rate overview]({source:fedPolicyRateOverview}) describes those tools, and the [IORB FAQs]({source:fedIorbFaq}) explain how reserve interest helps implement FOMC decisions. A target range is the policy instruction; EFFR is a rate measured in the market.
This distinction also matters when reading market contracts: a 30-Day Fed Funds futures contract uses a month's average EFFR, not the FOMC's target range. See how 30-Day Fed Funds futures work.
Banks set the prime rate
There is no single prime rate directly set by the Federal Reserve. Individual banks determine their prime rates. The Fed has no direct role in setting them, though many banks choose to base their rates partly on the FOMC's federal funds target. The prime rate is commonly used as a reference for some credit-card and small-business loans, according to the Federal Reserve's [prime-rate FAQ]({source:fedPrimeRateFaq}).
The H.15 release publishes a bank prime loan series. Its footnote defines that observation as the rate posted by a majority of the top 25 insured U.S.-chartered commercial banks, ranked by assets in domestic offices, and notes that prime is one of several base rates used to price short-term business loans. That is a reported reference series; a loan agreement may name a particular published index. The [H.15 series]({source:fedH15SelectedInterestRates}) and the index named in an individual contract should not be assumed to be interchangeable without checking the contract.
The rates often move together, but they are not identical
Many banks use the federal funds target as one input when setting prime, which helps explain why the rates often move in the same general direction. Monetary policy also influences other short-term interest rates and financial conditions. The Federal Reserve describes this process in its explanation of [how monetary policy affects rates and economic decisions]({source:fedMonetaryPolicyTransmission}).
But the Fed does not dictate each bank's prime rate or require every bank to change it at the same moment. The target range, EFFR, and bank prime are set or measured through different processes. Their published values need not match, and a particular loan may use a different index or adjustment date. For a related guide to market-implied policy expectations, see CME FedWatch versus the FOMC dot plot.
A variable APR can use prime plus a margin
A variable-rate loan or credit card may calculate its annual percentage rate (APR) by adding a fixed margin to an index. For example, a card agreement might use a named prime-rate series plus a margin. The CFPB notes that a variable card APR can change with an index such as the prime rate and that the cardholder agreement explains how the APR changes. See its guide to [fixed versus variable APRs]({source:cfpbFixedVsVariableApr}).
Here is a purely hypothetical calculation. Suppose a contract says APR = prime index + 14.00 percentage points. If that named index is 6.00%, the formula gives a 20.00% APR. If the index later falls to 5.50%, the formula gives 19.50%, a decrease of 0.50 percentage point, assuming the contract applies the change and no floor or cap affects the result. These figures are examples only, not current rates or an estimate of any borrower's APR.
The margin belongs to the contract; it is not the amount by which the Fed changes its target. A loan could use another index, a different margin, or a different formula. Do not infer a personal borrowing rate from a Fed announcement or a published prime series alone.
The contract controls the reset and the final APR
An index move does not by itself tell you the exact day your APR changes. The cardholder agreement or loan documents specify the index, margin, calculation method, and when the lender applies a reset. Look for whether the rate is variable, how often it can adjust, and any stated minimum or maximum rate. The CFPB says the agreement sets out how a variable APR may change and explains circumstances in which a card issuer may increase a rate when its index rises in its guide to [credit-card rate changes]({source:cfpbVariableAprIndexChanges}).
That is why “the Fed cut rates” does not necessarily mean a borrower's APR fell that day. The contract may use a particular prime publication, apply changes on a schedule, or include a floor. A fixed APR does not fluctuate with an index in the same way, though the CFPB notes that fixed does not mean a rate can never change under any circumstance. Check the applicable contract instead of assuming that every loan responds one-for-one or immediately.
Policy changes can affect borrowing conditions beyond prime-linked loans
The Fed's target range influences short-term interest rates and financial conditions more broadly. Those changes can affect household and business borrowing decisions, but the rate on a specific product also depends on its own benchmark, contract, lender pricing, and other market conditions. The Federal Reserve's overview of [monetary-policy transmission]({source:fedMonetaryPolicyTransmission}) describes that broader chain without promising an identical change in every loan rate.
Longer-term market yields can also behave differently from an overnight policy target. A ten-year Treasury yield reflects market pricing over a longer horizon, so it can rise even around a Fed rate cut. See why long-term Treasury yields can rise after Fed rate cuts for that separate question.
Identify the rate that actually applies to a loan
When comparing a quoted rate with a Fed announcement, first identify what the number represents: the FOMC target range, the EFFR, a bank's prime rate, a named loan index, or the borrower's APR. Then check the contract's margin and reset terms. A familiar label such as “prime” does not reveal the final APR without those details.
For a variable-rate account, locate the named index and the section that explains the calculation and adjustment date. For a fixed-rate account, do not treat the federal funds target as a direct input unless the contract says otherwise. These checks distinguish a policy signal from a specific borrowing cost; they do not predict future rates or determine which loan is right for an individual.
Common questions
Q1Does the Federal Reserve set the prime rate?
No. Individual banks set prime. The Federal Reserve says it has no direct role, although many banks use the federal funds target as one factor when choosing their prime rates.
Q2Is EFFR the same as the FOMC's target range?
No. The FOMC sets the target range, while EFFR is calculated from overnight federal funds transactions. The Fed uses implementation tools to steer market rates toward the target range.
Q3Does a Fed rate cut immediately lower every variable APR?
No. A variable APR changes according to the index and reset rules in the contract. The agreement may specify a margin, a particular prime-rate publication, an adjustment schedule, and a floor or cap.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
Which statement correctly distinguishes the federal funds target from EFFR?
Choose an answer to see the explanation