

Crypto Perpetual Futures Explained: Funding, Price References, and Exposure
Learn how crypto perpetual futures create derivative exposure, how funding and price references work, and why venue rules control the details.
In this guideA perpetual position is exposure, not ownership of the coin
Short summary
A crypto perpetual future is a derivative position with no scheduled contract expiry. The trader holds exposure defined by a venue's contract, collateral, margin, and close-out rules rather than ownership of the referenced coins. Funding transfers and several distinct price references help describe the position, but their formulas and timing are product-specific.
A perpetual position is exposure, not ownership of the coin
Buying a spot asset and opening a perpetual position create different account records. A spot purchase can give the buyer a token balance subject to the wallet or custodian arrangement. A perpetual position is instead a contractual claim whose profit and loss responds to a reference price under the venue's terms. A displayed “BTC perpetual” position does not by itself establish that the trader owns BTC, can withdraw BTC, or can deliver BTC into the contract.
Perpetual contracts omit the scheduled expiry date used by dated futures. That removes a specific contract-end and roll decision; it does not make the position permanent or identical across venues. A venue can still change product availability, margin requirements, collateral treatment, price inputs, funding schedule, or close-out procedures under its governing rules. A user may also close a position voluntarily or have it reduced or liquidated under the account agreement.
Most crypto perpetuals use a linear payoff quoted in a stablecoin or another quote asset, but inverse and other structures exist. Contract size, multiplier, collateral currency, and profit-and-loss currency therefore need to be read from the selected instrument's current specification. Perpetual futures versus dated futures explains the expiry distinction; CME Bitcoin futures provides a contrasting listed, dated product.
Funding is a venue-defined transfer, not a universal interest rate
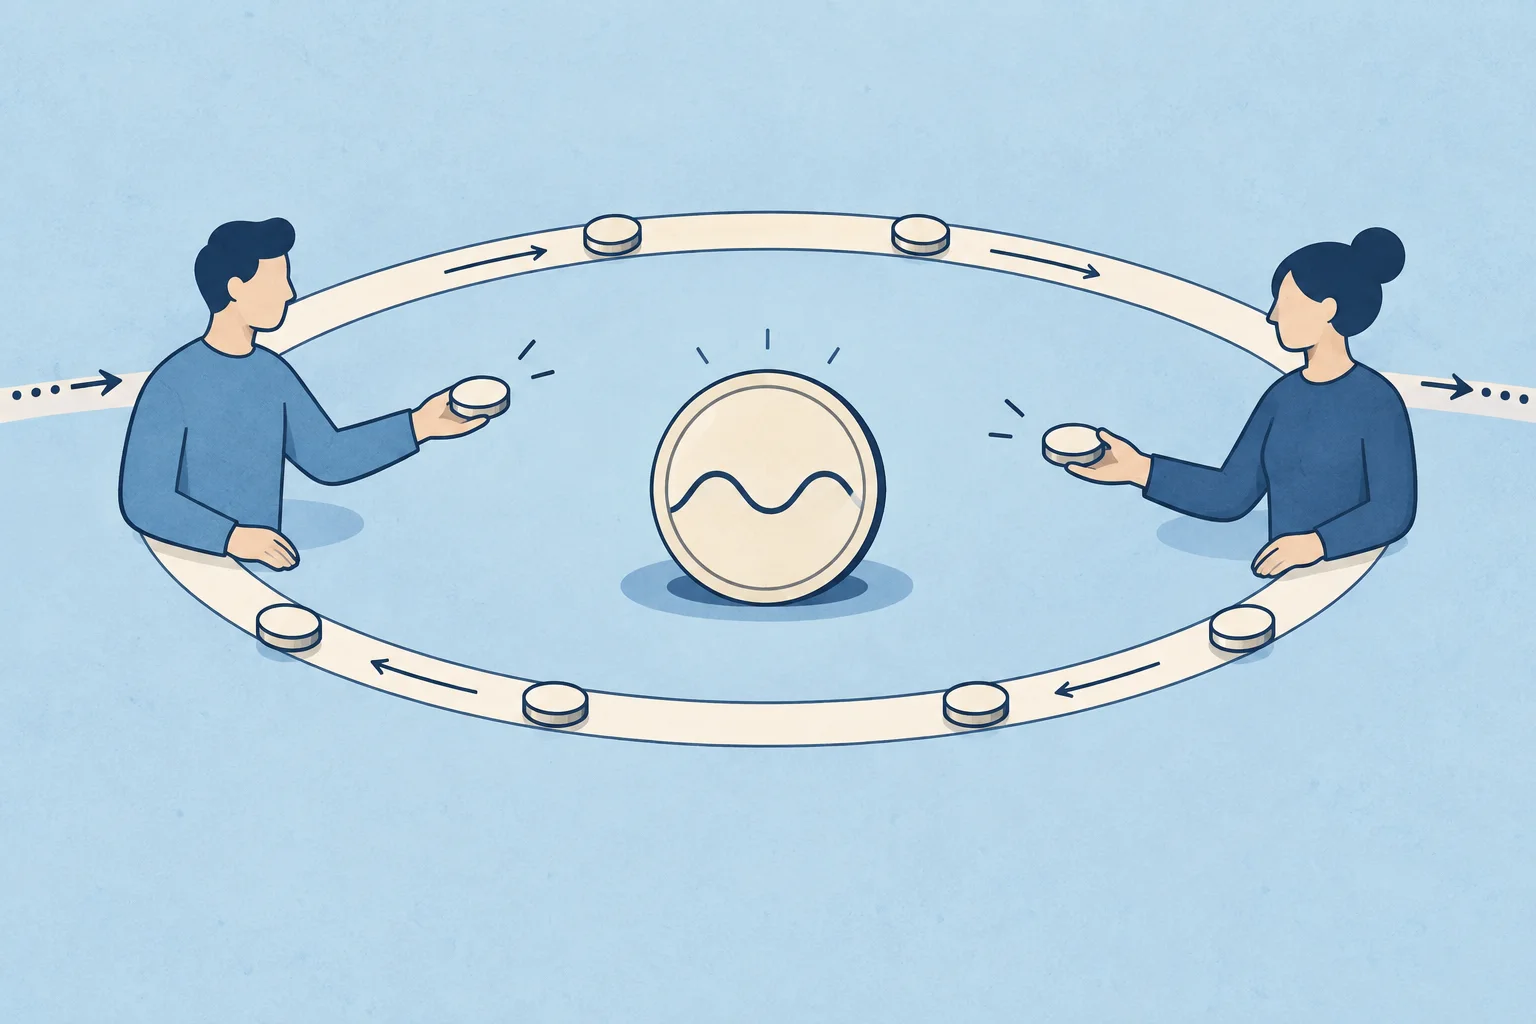
Without a final settlement date, a perpetual venue needs rules that connect its contract to an external spot or index reference. Many products use periodic funding transfers between long and short position holders. The design is intended to encourage the perpetual contract to trade near a chosen reference over time. It does not guarantee convergence at every instant or remove basis, liquidity, or counterparty risk.
The sign convention is not universal. A venue may set a positive funding rate to mean that longs pay shorts, while another product can define or display the field differently. The calculation may sample a premium over a window, include an interest component, apply a cap, and settle at a stated interval. A displayed annualized rate can be a projection from a recent observation; it is not a promised annual return or a fixed borrowing rate.
Hyperliquid documents an hourly funding payment and a formula based on a premium component and a clamped interest component. Its payment calculation uses the spot oracle price to convert position size to notional, while the mark price serves other purposes. These details describe that venue's documented contract rules, not every perpetual market. Coinbase's US perpetual-style product has its own specification and funding documents. Check the instrument, version, interval, sign, calculation inputs, and payment record before comparing two funding figures. The funding-rate guide works through the cash-flow distinction in more detail.
Last, mark, index, and oracle prices answer different questions
The last trade is the price of the most recent match on one order book. A mark price is a venue-defined reference used for valuation or risk controls. An index or oracle price may aggregate or otherwise derive a reference from spot markets. A venue can use different fields for displayed unrealized profit and loss, funding, stop triggers, margin, and liquidation. The words sound similar, but they are not interchangeable labels for one market price.
Hyperliquid's documentation, for example, says that its mark price combines inputs from external venues and its own order book and is used for margining and liquidations. Its oracle price is separately calculated from weighted spot-market prices and is used in its funding calculation. Another venue may use a different set of inputs, update interval, fallback behavior, or trigger field. A thin order book can therefore show a last trade that differs from a robust mark, while a mark can still move quickly as its inputs change.
When comparing a chart, a funding line, and an account's liquidation estimate, record the venue, contract, field name, quote currency, timestamp, and rule that uses the value. How CME Bitcoin futures quotes work shows the same discipline for dated futures fields. Never assume a price copied from a chart was the price used by a margin engine or was executable for the position's size.
Separate price profit and loss from funding and trading costs
For a simplified linear contract, price profit and loss can be represented as signed contract units multiplied by the change in the applicable valuation price. Suppose a hypothetical long position represents 0.20 BTC and the relevant mark moves from $50,000 to $49,000. Before fees, funding, and any venue-specific adjustments, the price component is 0.20 × ($49,000 − $50,000) = −$200. The example assumes a linear quote-currency payoff; it is not a Hyperliquid or Coinbase account calculation.
The account's total result can also include entry and exit fees, funding debits or credits, spread and slippage, collateral conversion, and other product adjustments. A positive funding credit does not cancel a larger adverse price move by definition. Nor is an unrealized mark-to-market amount the same thing as settled cash. The account statement and product rules determine when each component is posted and which price field is used.
A practical reconciliation keeps separate rows for position quantity, entry price, current valuation field and timestamp, realized and unrealized price P&L, funding payments, trading fees, collateral balance, and withdrawals or transfers. Combining these into one “return” number can hide which mechanism moved the account and whether that amount can be withdrawn.
The label “perpetual” does not tell you the contract's full risk
Two products can both be called perpetual futures while differing in collateral, quote asset, contract denomination, leverage tiers, funding caps, oracle construction, margin sharing, and liquidation sequence. A crypto asset used as collateral can also change in value at the same time as the derivative position, creating a second source of account-equity movement. Stablecoin collateral adds its own issuer, redemption, liquidity, and depeg risks.
No-expiry exposure still has an exit path. The venue may cancel orders, reduce a position, close it in the order book, transfer it to a backstop mechanism, or apply another process when margin falls below a threshold. Which sequence applies depends on the named product and current account rules. A perpetual contract also remains subject to venue availability, network or system outages, oracle disruptions, and market liquidity conditions.
Use a current contract page and account agreement as the primary records. Note the product code, collateral asset, linear or inverse payoff, multiplier, mark and oracle definitions, funding interval, initial and maintenance margin, fee schedule, and liquidation procedure. This guide explains mechanics; it does not recommend a venue, position, leverage level, or trade.
Common questions
Q1Does a perpetual contract have an expiry date?
It has no scheduled expiry like a dated futures contract. Venue rules can still close, reduce, or liquidate the position, and the trader can close it voluntarily.
Q2Does funding guarantee that a perpetual price equals spot?
No. Funding is a venue-defined mechanism intended to encourage a price relationship. It does not guarantee equality at every time or remove liquidity and basis risk.
Q3Is mark price the same as last price?
Not necessarily. Last price is the latest matched trade; mark price is a venue-defined reference used for purposes such as valuation or risk controls. Check the specific contract rules.
Q4Does a funding credit mean the position was profitable?
No. Funding is one cash-flow component. Price P&L, fees, collateral changes, and other costs can produce a different total result.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
Which statement describes a perpetual position?
Choose an answer to see the explanation
Options glossary
Clear definitions of essential option terms, from calls, puts, and option chains to IV, Greeks, open interest, and max pain
Browse the options glossary