

What Is a Fiscal Multiplier? Spending, Taxes, and GDP
Understand how a fiscal policy change can affect real GDP, why spending and tax multipliers vary, and what a multiplier estimate does not say.
In this guideWhat is a fiscal multiplier?
Short summary
A fiscal multiplier describes how an output measure changes after a government spending or tax-policy change. The ratio depends on what counts as the initial policy impulse, which output response is measured, and how long the response is allowed to unfold. It is an estimate relative to a counterfactual, not a fixed number that applies to every budget decision.
What is a fiscal multiplier?
A fiscal multiplier is a ratio between an economic outcome—often real gross domestic product (GDP)—and a change in fiscal policy such as government purchases, transfers, or taxes. In a simple spending example, the output multiplier can be written as:
Output multiplier = change in real GDP relative to a no-policy baseline ÷ fiscal spending change
The numerator and denominator need a common unit and a defined time horizon. Researchers may calculate the response at one quarter, at its peak, or cumulatively over several quarters or years. Estimates can also use the policy's budget cost, its direct effect on demand, or another measure as the denominator. That is why two papers can use the word “multiplier” for ratios that are not directly comparable.
The units matter as well. A dollar-for-dollar ratio of output to policy change is not automatically the same as a percentage response in GDP divided by a percentage change in spending. When a study scales the fiscal impulse as a share of GDP, its reported coefficient may not match a simple dollar example. Read the equation and the table notes before comparing coefficients.
The Congressional Budget Office (CBO) makes a useful distinction in its analysis of U.S. fiscal policy. It defines its demand multiplier as the total output change per dollar of direct effect on demand. Indirect effects can offset or amplify that initial effect; they are not the only output change counted in the ratio. CBO separately estimates how much a policy changes direct demand per dollar of budget cost, so a fiscal cost and the multiplier's denominator are not interchangeable. When reading another source, check its definition instead of assuming every paper uses the same terminology or denominator. The [CBO method overview]({source:cboFiscalPolicyEffects}) explains how direct and indirect effects enter its estimates.
For example, a program might have a $10 billion budget cost while an analysis estimates that $6 billion reaches demand directly during the period. Dividing an output response by $10 billion answers a cost-based question; dividing it by $6 billion answers a question about output per dollar of direct demand. Both ratios can be calculated, but they answer different questions and should not share a label without the definition.
A simple hypothetical example
Suppose a temporary public-works program creates an initial $10 billion increase in demand, measured in comparable real dollars. If real GDP ends up $12 billion above the no-policy baseline over the chosen four-quarter window, the illustrative output multiplier is $12 billion ÷ $10 billion = 1.2. The $12 billion is the total measured output response over that window, not an additional $12 billion in each quarter.
Here the numerator is defined as the cumulative output response across the four-quarter window. A paper that instead uses the output difference in the fourth quarter, or the largest response during the period, can report a different ratio for a similar policy. The time window alone is not enough; the source's rule for combining quarterly responses matters too.
This example is invented to show the arithmetic. It is not a measured estimate, a forecast, or a claim that every $10 billion program adds $12 billion to GDP. A study could use the program's budget cost rather than its initial demand effect, report a different horizon, or estimate a different counterfactual. Its multiplier could therefore differ even if the policy description sounds similar.
If the same $10 billion were a transfer payment, the first-round increase in demand might be smaller than $10 billion because recipients do not necessarily spend every extra dollar during the period. Some may save it, use it to repay debt, or spend it later. A calculation based on budget cost and one based on immediate demand would then have different denominators. Name the denominator before comparing the result.
Direct demand and follow-on effects
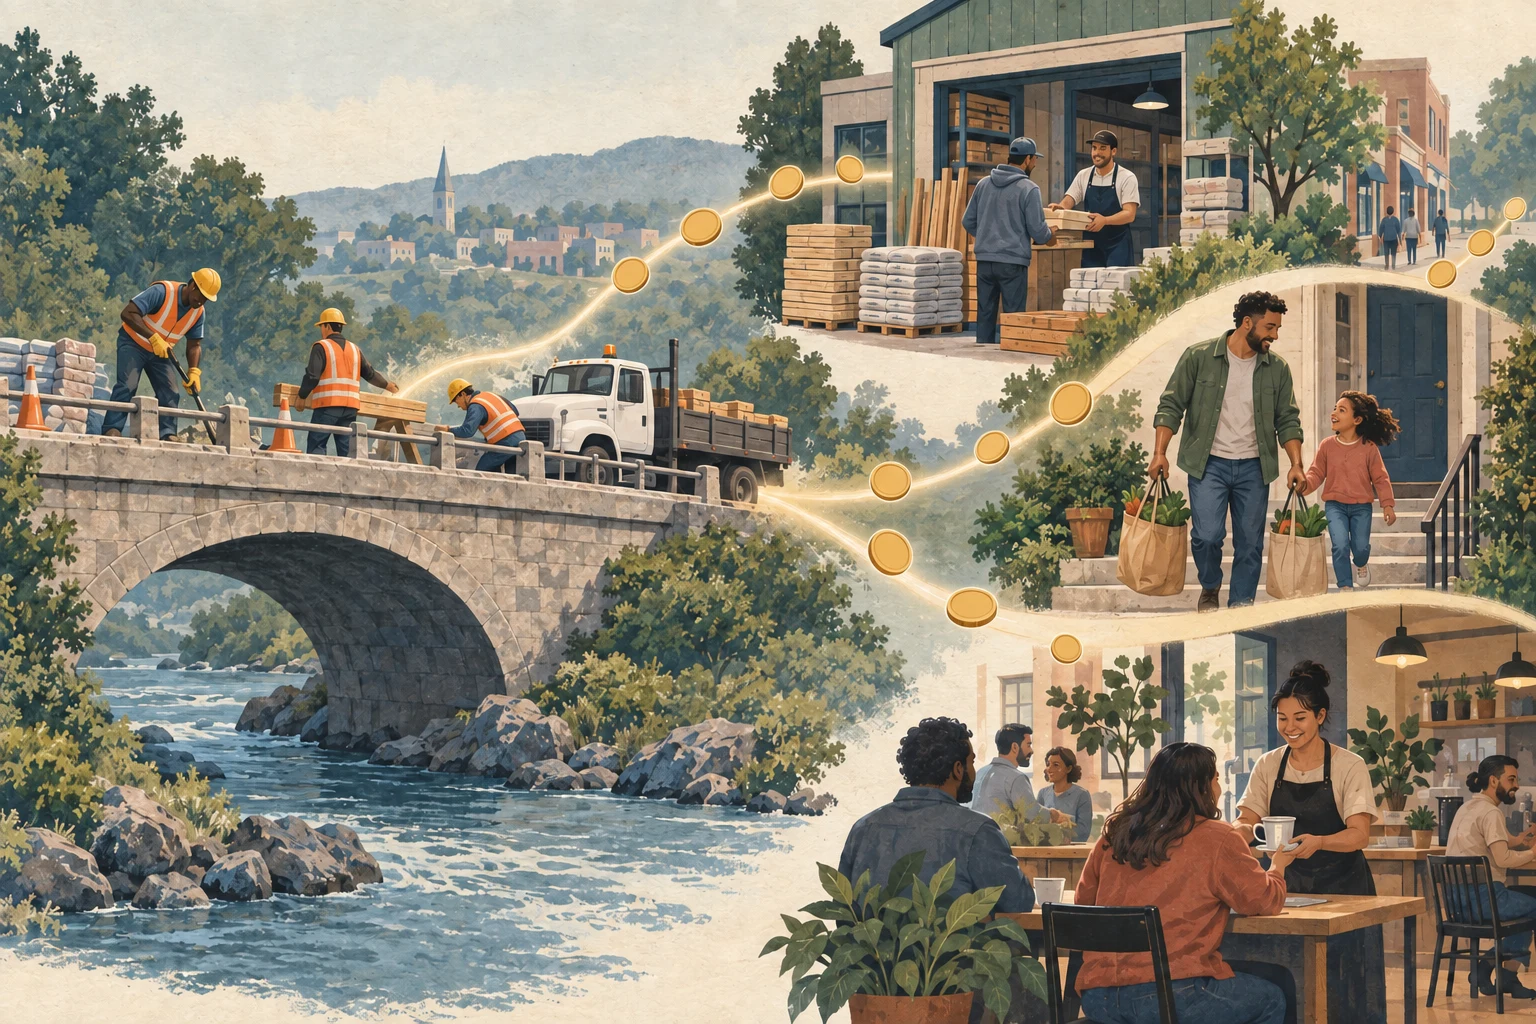
A policy first changes purchases, take-home income, or another part of private and public demand. A public agency buying construction services is a direct purchase. A household receiving a payment may spend some of it at a shop; that shop may order more stock or pay workers; those workers may then make other purchases. Such later rounds can add to output relative to the starting point.
The chain does not repeat every dollar without limit. Households and firms can save income, pay taxes, buy imports, or use the funds to repay debt. Prices, interest rates, exchange rates, and other policies can offset some of the new demand. In CBO's framework, the direct effect and these indirect effects are estimated separately before being combined. Its [short-term multiplier working paper]({source:cboFiscalMultiplierModelRanges}) describes that distinction and reviews why empirical estimates differ.
This is also why the multiplier is not simply “how many times money changes hands.” It measures a specified output response under an analytical definition. A transaction can occur without adding the same amount to domestic real GDP, and a business's sales revenue is not the same thing as economy-wide value added.
Why purchases, transfers, and tax changes can differ
Government purchases, transfers, and tax changes do not start from the same point. A purchase pays for a good or service. A transfer changes the recipient's income, and its near-term demand effect depends partly on how much of that income is spent. A tax reduction can have a different effect from a same-sized transfer because it changes after-tax income for a different set of households or firms and may be viewed as temporary or permanent.
For example, imagine two hypothetical households receive the same $1,000 tax reduction. One spends $700 during the next year and saves $300; the other spends $200 and saves $800. The immediate demand impulse differs even though the budget cost is identical. The amounts are illustrative, not a measured consumption rate. CBO notes that temporary versus permanent changes and recipients' financial circumstances affect its estimate of direct demand effects.
There is also a national-accounts distinction. Government consumption and investment are components of GDP, but a cash transfer is excluded from GDP when it is paid because the payment itself does not buy a good or service. A recipient may later spend some of the transfer on consumption, which can affect GDP. So a $1 transfer in the budget is not automatically $1 of direct government purchases in GDP. The [Bureau of Economic Analysis explains the treatment of transfers]({source:beaTransfersExcludedFromGdp}).
Authors may define a tax multiplier using a tax increase or a tax cut, so signs can look reversed across papers. One convention reports the GDP response divided by the signed tax change; another expresses the effect of a tax cut as a positive stimulus. Check how the paper defines a positive shock. CBO's [overview of multiplier models]({source:cboFiscalMultiplierMethods}) discusses the range of models and the reasons estimates can vary widely.
For instance, suppose a hypothetical $1 tax cut is followed by real GDP $0.60 above baseline over four quarters. One convention calls the response +$0.60 per dollar of tax cut. Another records the tax change as ΔT = −$1 and divides ΔGDP by signed ΔT, producing a negative ratio for the same increase in output. The sign alone does not tell you whether GDP rose or fell; check the source's convention. This invented example is arithmetic, not a typical estimate.
Why the state of the economy matters
The same policy can have different estimated effects in different conditions. When workers and equipment are underused, additional demand may lead firms to increase production. When capacity is already tight, more demand may show up more in prices, imports, or competition for workers and materials. These are mechanisms to consider, not a rule that mechanically assigns a multiplier from one slack measure.
Monetary policy can also respond. If a central bank raises rates in response to stronger demand, borrowing and spending elsewhere may be partly offset. CBO's method overview says it estimates the largest indirect demand effects when short-term rates are near zero, when the interest-rate response is more constrained. That statement describes its modeling assumptions and evidence; it does not guarantee a particular multiplier at any policy rate.
Country features matter too. An IMF working paper using a specific quarterly dataset for 44 countries reported that its estimated government-consumption effects differed with development level, trade openness, exchange-rate regime, and public debt. Those findings demonstrate why context belongs beside an estimate; they are not a universal table of multipliers for every country or program. The paper presents its authors' analysis; the views in an IMF working paper do not necessarily represent those of the IMF, its Executive Board, or IMF management. See the [IMF study and its sample description]({source:imfGovernmentSpendingMultipliers}).
How economists estimate a multiplier
GDP changes for many reasons at once: households alter spending, firms change investment, trading partners grow or contract, and policymakers respond to economic conditions. A simple before-and-after comparison cannot isolate the contribution of a tax or spending change. Analysts need a counterfactual path for what output would have been without the policy, then a method for separating the policy shock from other changes.
Policy and the economy also affect each other. Tax receipts and some benefit payments can change automatically as income and employment move, while policymakers may enact discretionary support because output has already weakened. An analyst needs to distinguish the fiscal change being studied from the downturn or recovery that led to it. Otherwise, a policy response can be mistaken for the original cause of the economic change. CBO's [fiscal impulse paper]({source:cboFiscalImpulseMeasures}) discusses measures designed to identify direct effects of federal policy changes on near-term real GDP growth.
Researchers use economic models, historical episodes, and statistical methods to build that comparison. They may ask whether a policy was unexpected, use records or forecasts to identify a policy change, or estimate how output evolved after a defined shock. Different identification choices and model structures can produce different estimates. A Federal Reserve research paper on structural vector autoregressions shows how identification assumptions can affect estimated fiscal multipliers; its estimates are specific to its model and historical U.S. sample, not a current policy score. Read the [Federal Reserve paper on multiplier identification]({source:fedFiscalMultiplierIdentification}).
The timing measure matters as much as the model. An impact multiplier measures the response at a stated point; a peak multiplier uses the largest response; a cumulative multiplier adds output responses over a period; and a present-value measure discounts responses at different dates. A multiplier above one under one definition does not imply that output permanently stays above baseline or that the government recovers the policy's full budget cost through extra revenue.
What a multiplier does not tell you
A multiplier is not a growth rate. If an estimate says that output is $12 billion above a counterfactual after a hypothetical $10 billion impulse, it describes a difference in output level over a stated window. It does not mean GDP growth is 12%, nor does it mean the economy will grow 1.2% faster every year. Many fiscal studies measure real GDP, which adjusts for price changes, but the source should still be checked.
It is also not a direct measure of a policy's long-run effect on productive capacity, its distributional consequences, or whether it is worth its budget cost. CBO treats short-term demand effects and longer-term changes to work, saving, investment, and potential output as separate parts of its analysis. A demand multiplier above one does not prove that a policy pays for itself; a multiplier below one does not by itself settle its social value.
For related terms, the guide to automatic stabilizers explains how taxes and benefits can change with the economy even without a new policy vote. The output-gap guide covers the difference between actual and estimated potential GDP, which is one measure analysts may use when discussing slack. For the related fiscal stock and flow distinction, see budget deficit versus national debt.
How to read a multiplier estimate
Before comparing two estimates, write down: the policy type; what counts as the shock; the denominator; whether the GDP response is real or nominal; the impact, peak, cumulative, or present-value horizon; the country and economic conditions; and the method used to construct the counterfactual. Also check whether the estimate is a central value or one point in a range. CBO's [2025 working paper on fiscal impulse measures]({source:cboFiscalImpulseMeasures}) distinguishes direct policy effects on growth from broader interpretations of changes in fiscal policy.
Use the estimate as one conditional input to an economic analysis, with its definition attached. If a headline quotes “the multiplier” without a policy, horizon, or source, there is not enough information to tell whether it describes spending, a tax cut, direct demand, total output, or a different response. The number is meaningful only after those choices are clear.
Common questions
Q1Is a fiscal multiplier always greater than one?
No. Estimates differ by policy, country, economic conditions, method, denominator, and time horizon. A reported value cannot be generalized without those details.
Q2Does a multiplier above one mean government spending pays for itself?
No. It measures an output response under a defined method. Whether additional tax revenue offsets the policy's budget cost requires a separate fiscal analysis with its own assumptions and time frame.
Q3Are tax multipliers and spending multipliers directly comparable?
Not automatically. A spending estimate may use government purchases or their direct demand effect as its denominator, while a tax estimate may use a tax increase or tax cut with a different sign convention. Compare the definitions, output measure, and horizon first.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What must be specified before comparing two fiscal multiplier estimates?
Choose an answer to see the explanation
Options glossary
Clear definitions of essential option terms, from calls, puts, and option chains to IV, Greeks, open interest, and max pain
Browse the options glossary