

Fiscal Multiplier Explained: Spending, Taxes, and GDP
Learn how fiscal multipliers compare a policy's budget cost with its GDP effect, why estimates vary by policy and conditions, and how to read them.
In this guideWhat does a fiscal multiplier measure?
Short summary
A fiscal multiplier compares a defined change in output with a defined spending, tax, or transfer measure. It is not one permanent number for every policy: the estimate depends on what the government changes, who is affected, the state of the economy, the monetary-policy response, and the time horizon.
What does a fiscal multiplier measure?
A fiscal multiplier is a ratio used to summarize how a fiscal-policy change relates to economic output. A broad form is:
Fiscal multiplier = change in output relative to a baseline ÷ defined fiscal action or its budgetary cost
That compact formula hides choices that matter. Output may mean real GDP at a particular date, the change in GDP over a year, or the total response over several years. The denominator may be a dollar of government purchases, a dollar of direct demand, a change in tax revenue, a transfer payment, or a policy’s budgetary cost. Tax multipliers also depend on sign convention: a tax increase and a tax cut move in opposite directions, and studies do not always express the ratio the same way. Read the source’s definition before comparing two numbers.
The Congressional Budget Office (CBO) distinguishes a demand multiplier, which summarizes indirect changes in output per dollar of direct demand, from an output multiplier, which summarizes the full short-term output effect of a policy relative to its budgetary cost. That distinction helps explain why two reports can both use the phrase “fiscal multiplier” but calculate different ratios. CBO outlines those concepts in its [short-term fiscal-policy analysis]({source:cboShortTermFiscalPolicyMultipliers}) and its [overview of how it analyzes fiscal-policy effects]({source:cboFiscalPolicyEffects}).
For a deliberately hypothetical example, suppose a one-time policy has a budgetary cost of $100 billion and a model estimates that real GDP during a stated one-year horizon is $80 billion higher than in the no-policy baseline. Under that exact definition, the ratio is $80 billion ÷ $100 billion = 0.8. The arithmetic does not say that the policy repays 80% of its cost to the Treasury, creates a guaranteed return, or would have the same effect in another year. The $80 billion is a modeled output response, not a tax-revenue estimate or a current observation.
How one fiscal action can affect later spending
The initial effect depends on what the policy changes. When a government agency purchases a domestically produced service, that purchase can add directly to demand for the service. A transfer payment is different: the payment itself is not a purchase of newly produced goods or services in GDP. It can affect output when the recipient uses some of the additional disposable income to buy goods and services. A tax reduction also changes disposable income, but its first-round demand effect depends on how much recipients spend, save, or use to repay debt.
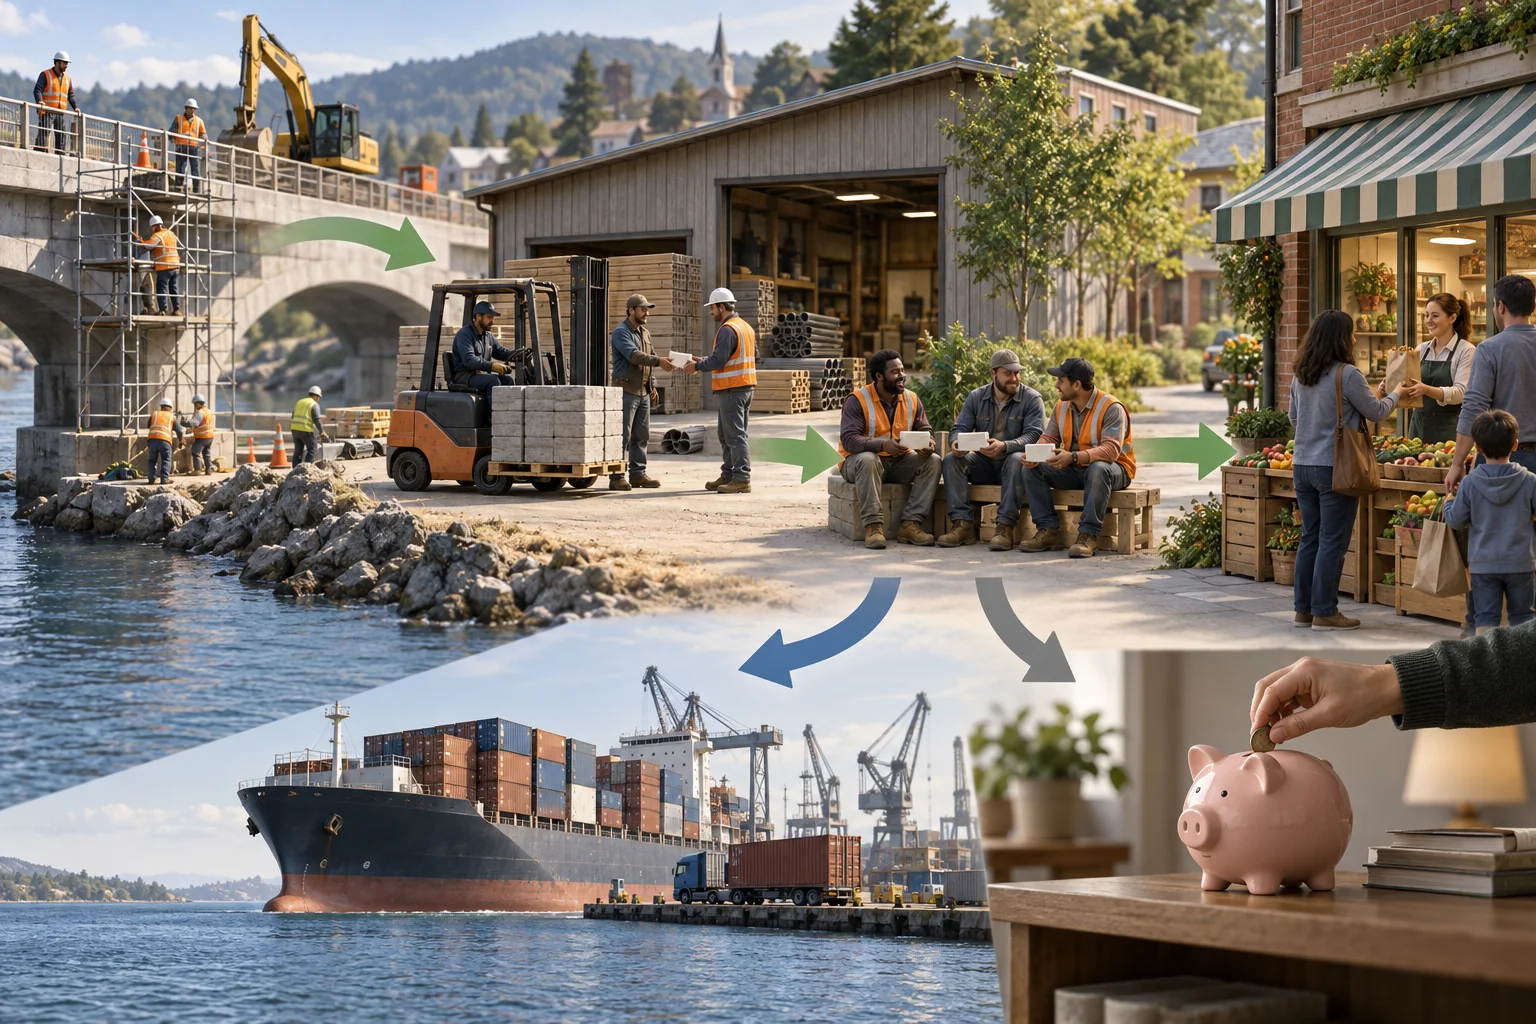
Those initial purchases become income for workers and businesses. Some recipients may then spend part of that income, creating another round of demand. Suppliers may increase hours or production, and businesses may place orders with other firms. These are indirect effects. They can amplify the initial demand change, but they can also be offset by saving, imports, higher prices, delays, or changes in interest rates. CBO describes its short-term analysis as combining direct effects with indirect effects that can either enhance or offset them.
The familiar classroom multiplier illustrates one possible chain. In a very simplified closed-economy model with spare capacity, fixed prices, no taxes or imports, and a constant fraction of each extra dollar spent on consumption, repeated spending rounds form a geometric series. That result explains the basic mechanism; it is not a ready-made estimate for a real policy. Actual economies include taxes, saving, imports, capacity limits, expectations, and monetary-policy responses. A government purchase, tax cut, and transfer can therefore have different first-round effects even when their headline budget costs are equal.
Why purchases, tax cuts, and transfers differ
A purchase order for equipment or construction can place demand directly on suppliers, but its budget cost may be paid over time and the work may take years to start. A tax cut affects demand through the people and firms that receive it. A transfer affects recipients’ income without being counted as government production itself. The same budget cost can therefore produce different amounts of immediate spending, and the timing of the spending can differ too.
Recipients’ circumstances matter. A household that cannot borrow easily may spend more of a temporary payment than a household that can smooth spending using savings or credit. A permanent tax change can affect expected lifetime resources differently from a temporary one. CBO notes that a temporary tax cut generally has a smaller effect on purchases than a permanent cut and that lower-income households are more likely to spend an increase in disposable income than higher-income households. These are tendencies used in policy analysis, not rules that predict each household’s behavior.
Design also affects whether money reaches the intended recipients promptly. Eligibility rules, application steps, procurement capacity, and construction readiness can delay an intervention. A measure enacted during a downturn may not support demand until the economy has already changed. A study that compares budget authority, cash outlays, and the timing of recipients’ spending may consequently report different effects. When evaluating a policy, ask what amount enters the denominator and when the underlying demand is expected to occur.
Why the economy’s condition changes the estimate
If businesses have idle equipment and workers are seeking jobs, additional demand may lead firms to increase production and employment. When capacity is already tight, firms may instead raise prices, compete for scarce labor and materials, or redirect resources from other buyers. A positive output gap is one possible indicator of capacity pressure, but it is an estimate rather than a directly observed ceiling; see how potential GDP and the output gap are measured. The same fiscal action can therefore have a different real-output effect at different points in the business cycle.
Monetary policy can reinforce or offset fiscal demand. If a central bank responds to stronger demand and inflation pressure by raising interest rates, borrowing and interest-sensitive spending may weaken, reducing the output response. If policy rates are near an effective lower bound and monetary policy does not offset the fiscal expansion, some research finds larger multipliers. The CBO says indirect demand effects are largest when short-term interest rates are close to zero. The IMF’s [2020 analysis of future recessions]({source:imfWEOFiscalMultipliers2020}) also estimates larger effects under labor-market slack and supportive monetary conditions. Those findings describe estimated relationships under specified conditions; they are not a forecast that any current stimulus will have a particular multiplier.
The result can differ across countries as well. Exchange-rate arrangements, the share of spending that goes to imports, access to credit, the credibility of policy, and how the central bank reacts all shape how much demand remains directed at domestic output. A multiplier from a U.S. federal-policy analysis should not automatically be applied to another economy, policy instrument, or period.
The IMF’s [technical note on fiscal-multiplier size, determinants, and use]({source:imfFiscalMultiplierDeterminants}) reviews why the estimates depend on policy and economic context. It offers a framework for interpreting estimates, not one coefficient that applies to every country.
How the horizon changes the number
An impact multiplier measures an output response at or near the start of a policy. A one-year multiplier asks about a stated output response after a year. A cumulative multiplier summarizes output responses across multiple periods relative to a defined fiscal impulse over that span. Researchers and agencies may use different formulas and time conventions, so the labels alone do not make estimates comparable.
Suppose two analyses evaluate the same $100 billion policy. One reports that GDP is $40 billion above baseline in the first year; another reports the total response over four years. Those figures answer different questions even if both are described as a multiplier. The first is tied to an early horizon; the second includes later periods, when recipients may have spent income, a central bank may have changed rates, and the original policy may have ended. A peak response, an end-of-year response, and a sum across quarters are also not interchangeable.
Check whether the output measure is real or nominal GDP, whether the result is a level difference or a growth-rate change, and whether the stated period is an annual rate or a cumulative total. These distinctions prevent a temporary lift in the level of output from being misreported as a permanently higher growth rate. For the difference between inflation-adjusted output and current-dollar output, see nominal versus real GDP.
What can leak out or offset the first-round demand?
Not every dollar of a budget measure becomes a dollar of domestic demand. A recipient can save some income, repay debt, or purchase imported goods. Imports may benefit the buyer, but production abroad is not domestic GDP. Firms may use a public contract to meet existing demand rather than expand total output. If skilled workers, materials, or transport capacity are scarce, the project may bid up prices or displace another activity.
Financing and expectations matter too. If a policy is financed by taxes that reduce other spending, the net demand impulse is smaller than the gross outlay alone suggests. Borrowing can affect interest rates and private investment, especially over longer periods; a temporary short-run multiplier does not measure that whole financing path. People and businesses may also change current spending if they expect a temporary policy to end soon or anticipate future taxes.
These are not reasons to assume that every policy has a low multiplier. They are channels an estimate must handle. For example, a timely transfer to households likely to spend it may differ from a tax incentive that is not used until a company makes a later investment. A project that can begin quickly differs from an appropriation that waits for planning and procurement. A good estimate names the policy details instead of assigning one coefficient to all government spending.
A short-run multiplier is not a long-run growth rate
Fiscal changes can affect output through more than near-term demand. Taxes can change incentives to work, save, or invest. Public investment can add useful infrastructure, education, or research that raises productive capacity if it is well selected and effectively delivered. Borrowing can reduce national saving and private investment over time. These channels can push longer-term output in different directions.
CBO analyzes short-run demand effects separately from longer-run effects on potential output, using different models and a range of estimates to reflect uncertainty. Its [2015 paper on fiscal multipliers and policy analysis]({source:cboFiscalMultiplierModels2015}) explains why economists use different models. CBO’s [2026 paper on the macroeconomic methods used for the 2025 reconciliation act]({source:cboMacroEffects2025Reconciliation}) provides a recent example of mapping particular policy provisions to economic channels and analytical models; it is a case-specific U.S. analysis, not a universal multiplier table.
Thus a short-run multiplier is not a score for whether a policy is worthwhile, self-financing, or a lasting productivity gain. Those questions require additional evidence about distribution, public value, implementation, financing, inflation, and the long-run counterfactual. A project may have a modest near-term multiplier but produce useful public assets; another may raise output briefly without improving productive capacity. Keep the time horizon and objective explicit.
How to read a multiplier estimate
Before using a multiplier, check the policy and the counterfactual. Was the change a government purchase, tax cut, tax increase, transfer, or a combination? Is the denominator the gross budget cost, the change in direct demand, or a signed change in tax receipts? Is the estimate for one country and a particular monetary-policy regime? Does it compare the economy with a plausible no-policy baseline?
Then check the output and timing. Is the outcome real GDP, employment, consumption, or another measure? Is it a response at one quarter, one year, or a cumulative total? Does the paper report an average, a range, or uncertainty intervals? Were implementation delays, imports, tax financing, monetary-policy reactions, and possible supply effects included?
Finally, identify how the estimate was produced. A macroeconomic model simulates a counterfactual under assumptions about households, firms, and policy rules. An empirical study uses historical episodes or policy shocks, but its result depends on how the shock is identified, which periods and countries enter the sample, and which other changes are controlled for. The CBO typically reports ranges because estimates of demand multipliers are uncertain. A point estimate is one conditional result, not a physical constant or a precise forecast for the next budget.
The baseline is not simply last quarter’s observed GDP. Automatic stabilizers can change taxes and benefits as the economy weakens even if lawmakers pass no new measure. Analysts must separate a new discretionary action from changes that would have happened anyway and account for other shocks. Observed GDP growth by itself is not the policy effect; the multiplier compares two specified paths, one with the measure and one without it.
For a headline or policy report, state the measure, denominator, horizon, output variable, comparison baseline, and main assumptions. That lets a reader distinguish “$1 of this specified policy is associated with this modeled GDP response over this period” from the much stronger—and usually unsupported—claim that every public dollar automatically creates the same amount of output.
For related context, compare the annual budget deficit with federal debt and potential GDP with the output gap. The deficit article explains the budget flow and debt stock; the output-gap article explains estimated capacity. Neither alone determines the multiplier of a particular policy.
Common questions
Q1Is the fiscal multiplier always greater than one?
No. It can be below, near, or above one under different definitions and conditions. A value above one is not guaranteed by the act of spending; estimates depend on the policy, recipients, spare capacity, monetary response, imports, financing, and horizon.
Q2Are government-spending and tax multipliers the same?
No. A government purchase can create direct demand for goods or services. A tax cut changes disposable income, and the amount spent depends on who receives it and whether the change is temporary or permanent. Studies may also use different sign conventions and budget-cost denominators.
Q3Does a multiplier estimate forecast next year's GDP?
Not by itself. It describes a modeled or empirically estimated response relative to a specified no-policy baseline and under stated assumptions. A forecast also needs current data, an expected policy path, a horizon, and other economic shocks.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
In a hypothetical model, a policy costs $100 billion and real GDP over the stated year is estimated to be $80 billion above the no-policy baseline. Under that definition, what is the multiplier?
Choose an answer to see the explanation
Options glossary
Clear definitions of essential option terms, from calls, puts, and option chains to IV, Greeks, open interest, and max pain
Browse the options glossary