

Time-Series vs Cross-Sectional Momentum: How the Signals Differ
Compare a trend signal based on an asset’s own past return with a strategy that ranks assets against peers, using a worked example and clear limits on historical evidence
In this guideTwo rules ask different questions about past returns
Short summary
Time-series momentum compares an asset’s own past return with zero or another predeclared threshold: positive momentum points long and negative momentum points short under a simple sign rule. Cross-sectional momentum ranks assets against one another and takes positions in relative winners and losers. When every asset has a negative lookback return, the first rule can short them all while the second still buys the least-negative assets. Neither rule guarantees a profitable strategy
Two rules ask different questions about past returns
Momentum is a family of signal rules, not one fixed trading system. Time-series momentum asks whether an asset’s own return over a defined lookback period was positive or negative. Cross-sectional momentum asks which assets performed better or worse than the rest of a chosen universe over a comparable period
That distinction changes positions even when both rules use the same return history. A time-series signal is anchored to the asset’s own direction. A cross-sectional signal is anchored to the relative ordering of peers, so an asset can be a “winner” even when its return was negative
The labels do not specify a lookback, holding period, asset universe, weighting method, or trading cost. Those choices belong to the strategy design and must be stated before interpreting results
Time-series momentum follows an asset’s own direction
Let Rᵢ,t−L:t be the chosen return for asset i over a lookback ending at decision time t. A simple directional rule is sᵢ,t = sign(Rᵢ,t−L:t): positive means long, negative means short, and zero can mean no position. Some implementations use excess returns, thresholds, or volatility-adjusted weights; those are additional design choices rather than the definition of the comparison
Because the decision is made asset by asset, all signals can point the same way. If every instrument has a negative lookback return, a sign-based time-series rule can short the whole set. If every return is positive, it can go long the whole set. The portfolio can therefore have substantial net exposure to a broad market move
Specify how returns are measured and aligned to the decision time. Futures studies may use excess returns, while a stock strategy may use a different return series. Do not treat a close-to-close return as tradable if the signal only became known after that close
Cross-sectional momentum ranks assets against their peers
At each rebalance date, cross-sectional momentum sorts the eligible assets by a defined past-return measure. A common long-short form buys assets near the top of the ranking and sells assets near the bottom. The portfolio’s direction is relative: it can hold longs and shorts even if all assets rose or all assets fell
The strategy needs a defined universe and ranking rule. State how many assets enter each side, how ties are handled, whether sector or market exposures are neutralized, and what happens to assets with missing returns. “Winner” means stronger than the chosen peers under that rule; it does not necessarily mean a positive absolute return
Cross-sectional portfolios often aim for balanced long and short exposures, but ranking alone does not make a portfolio market-neutral or risk-neutral. Weights, volatility, correlations, constraints, short availability, and execution determine the exposures actually held
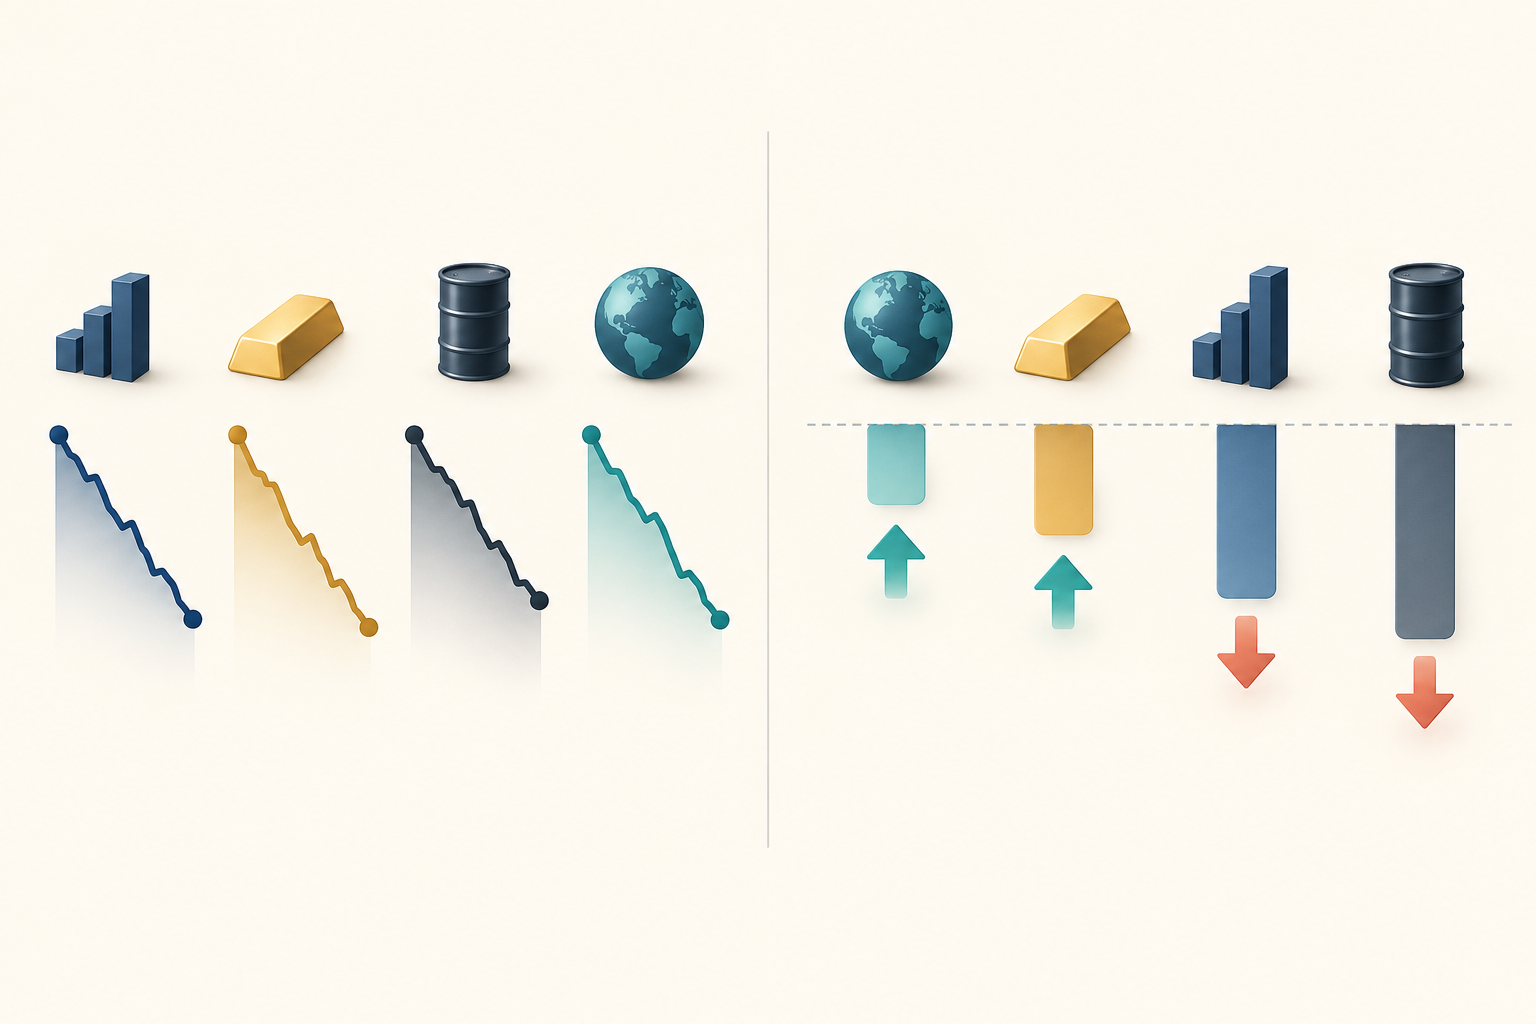
A four-asset example shows where the rules disagree
All values below are hypothetical. Suppose four assets had these returns over the previous three months: A −1%, B −3%, C −5%, and D −8%. A sign-based time-series rule points short in all four because each asset’s own lookback return is negative
A cross-sectional rule can still rank A and B as the two relative winners and C and D as the two relative losers. If it buys the top two and sells the bottom two, it is long A and B and short C and D. Asset A is the strongest relative performer despite having lost 1%; the rank does not change its negative absolute return
Now suppose the next month’s hypothetical returns are A +1%, B +1%, C +5%, and D +8%. Hold equal absolute weights of 25% from the start of that month. The time-series portfolio is short every asset, so its return before costs is −0.25(1% + 1% + 5% + 8%) = −3.75%. The cross-sectional portfolio is long A and B and short C and D, so its return is 0.25(1%) + 0.25(1%) − 0.25(5%) − 0.25(8%) = −2.75%
This one-period arithmetic illustrates different positions and different market exposure, not which method is better. Both examples have 100% gross exposure, but the all-short time-series portfolio has −100% net exposure while the long-short portfolio has zero net exposure. The values are invented, risk is not matched, and fees, financing, borrow, roll, spread, slippage, and rebalancing are excluded
A signal does not specify portfolio weights
A signal is not a holding. One simple time-series construction makes weight proportional to the direction signal divided by estimated volatility; one cross-sectional construction centers asset ranks around their cross-sectional mean. Both then need a normalization rule, risk limits, and any required neutrality constraints. These are examples, not universal formulas
Gross exposure is the sum of absolute weights; net exposure is the sum of signed weights. Matching gross exposure, as in the worked example, does not match volatility, factor exposures, liquidity, or tail risk. State how the signal is translated into positions and report the resulting exposures separately
Lookback and holding periods are separate choices
The lookback period determines which past returns enter a signal; the holding period determines how long positions remain; the rebalance schedule determines when the signal and weights are refreshed. These periods can differ. Some equity momentum designs also skip the most recent month to reduce the influence of short-term reversal, but there is no single universal setting for every market or question
Published findings illustrate particular designs rather than recommended parameters. Moskowitz, Ooi, and Pedersen report own-return predictability across 58 liquid instruments, including futures and currency forward contracts, with persistence over roughly one to 12 months and partial reversal at longer horizons (“Time Series Momentum,” 2012). Jegadeesh and Titman study buying past stock winners and selling past losers and report positive returns for their tested strategies over three- to 12-month holding periods (“Returns to Buying Winners and Selling Losers,” 1993). Neither study establishes one best parameter set for every asset, period, or investor
Frequency also affects the evidence count. If a strategy rebalances weekly but predicts a 20-trading-session return, consecutive weekly targets share about 15 daily returns. Fifty-two weekly observations are therefore not 52 independent experiments. Spacing decisions 20 trading sessions apart removes that target overlap but leaves fewer observations, and common shocks or repeated assets can still create dependence
Position sizing is another layer. Equal weights, volatility scaling, risk limits, and portfolio constraints can turn the same signal into different holdings. Report whether a result comes from signal direction, weight construction, or both
Momentum results depend on the sample and implementation
Past-return patterns are empirical findings, not guarantees that a rule will persist. Market structure, universe membership, return definitions, contract rolls, missing data, look-ahead bias, and the choice of lookback and holding periods all affect a backtest. Repeatedly trying variants and reporting only the strongest one also creates a selection problem
Cross-sectional equity momentum can suffer abrupt losses when prior losers rebound sharply. Daniel and Moskowitz analyze severe crashes in momentum portfolios, linking them to panic conditions after market declines, high volatility, and subsequent market rebounds (“Momentum Crashes,” 2016). This evidence concerns the portfolios and samples they study; it should not be generalized into a claim that every time-series strategy has the same crash pattern
Trading frictions can change results as well. A backtest should account for turnover, spread, market impact, short borrow or financing, futures roll assumptions, position capacity, and the timing at which an order could actually be placed. A profitable gross return is not the same as an investable net result
Report enough detail to reproduce the comparison
A useful report names the universe and its historical membership, return series, lookback and holding periods, rebalance calendar, signal thresholds, long and short selection rules, tie and missing-data handling, weights, risk controls, and transaction-cost assumptions. It also reports whether performance is gross or net and how validation periods were kept separate from signal selection
Keep the research record of every tested lookback, skip period, universe, ranking cutoff, risk-scaling rule, and cost assumption. Choosing the best result after trying many combinations makes the chosen performance an in-sample selection result. Use a genuinely untouched period or a walk-forward design, and account for dependence when return windows overlap
Keep the questions distinct: momentum defines how past returns form a signal; information coefficient measures how well a signal is associated with later cross-sectional returns. See the IC and Rank IC guide. If forecast periods overlap, the purged cross-validation guide explains one way to keep labels from leaking across validation splits. Annualizing performance with serially dependent returns also needs care; see the Sharpe ratio and serial correlation guide
Neither a high historical return nor a familiar momentum label establishes future performance. Compare rules on matched samples, state the exposures each actually holds, and test a fully specified strategy out of sample after realistic costs
Common questions
Q1Is time-series momentum the same as trend following?
The terms often overlap. A time-series momentum rule uses an asset’s own past return to determine direction, while “trend following” can refer to a broader family of rules with different filters, thresholds, and position-sizing methods
Q2Can cross-sectional momentum buy assets whose returns are negative?
Yes. A relative winner is one that ranks above its peers under the selected universe and return measure. If every asset fell, the least-negative assets could still be the long side of a cross-sectional portfolio
Q3Does momentum guarantee a positive return after costs?
No. Historical evidence is tied to specific samples and strategy designs. Turnover, spreads, market impact, borrow, financing, futures rolls, capacity, and abrupt reversals can reduce or reverse gross results
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What is the main difference between the two momentum rules?
Choose an answer to see the explanation
Options glossary
A model decomposing asset returns into exposure to a small set of common factors and an asset-specific residual.
Read the deeper guideHeteroskedasticityVariation in the conditional error variance across regressor values or states, invalidating an equal-variance covariance formula.
Read the deeper guide