

Tax Incidence Explained: Who Really Bears a Tax?
Learn why the person who remits a tax may not bear its full economic cost, and how supply and demand elasticities shape the split.
In this guideWhat does tax incidence measure?
Short summary
A store may send a sales tax to the government, but that fact alone does not show who bears the tax’s economic cost. Buyers may pay more, sellers may keep less, workers may receive lower compensation, or owners may earn lower returns. **Tax incidence** asks how the burden is distributed after people and firms adjust.
What does tax incidence measure?
Tax rules identify who is legally liable for a tax and who must collect or remit it. Those are related administrative roles, but neither one settles the economic question. A retailer can be responsible for collecting value-added tax from customers and paying it to the treasury while the final burden is shared through prices, wages, and returns. The OECD distinguishes legal tax liability, legal remittance responsibility, and economic incidence as separate dimensions of business taxation. {source:oecdTaxIncidence2017}
Economic incidence describes whose purchasing power or income is reduced relative to a counterfactual in which the tax was not imposed. The counterfactual matters: the question is not simply who writes a cheque today, but how prices, quantities, wages, profits, and other terms differ because of the tax. The answer depends on how consumers and producers respond and on what alternatives are available.
It is useful to keep three questions separate:
- Who is legally charged? The statute or regulation names a liable person or entity.
- Who remits the payment? A business, employer, platform, or individual may transfer the tax to the government.
- Who bears the economic cost? Buyers, workers, owners, suppliers, or a combination may end up with less purchasing power or income.
A claim that “businesses pay” a particular tax may describe the legal or remittance rule without establishing the third answer. Conversely, the person shown as the legal taxpayer may still bear some of the cost. {source:oecdTaxIncidence2017}
How a per-unit tax creates a price wedge
Consider a competitive market for one good. Before tax, buyers pay a market price P₀, sellers receive that same amount, and the quantity traded is Q₀. Add a tax of t for each unit sold. After the tax, buyers pay a gross price Pᵦ while sellers keep a net price Pₛ:
Pᵦ − Pₛ = t
That difference is the tax wedge. The government’s rule decides which side formally remits the amount, but market adjustment determines how the wedge is divided between a higher price paid by buyers and a lower net receipt for sellers. {source:cboIndirectTaxIncidence}
The market usually trades fewer units because buyers face a higher price and sellers receive less for each unit. “The seller pays the tax” is therefore not the same statement as “the seller bears all of its cost.” If the seller is the remitter but can raise the price, some burden may reach buyers. If buyers are the remitters, sellers can still be affected by lower demand and a lower price before tax. In the standard competitive model, changing which side sends the payment does not by itself change the wedge or its economic split; real administrative frictions can make legal assignment relevant.
The wedge describes prices per unit. It does not, by itself, say how much tax revenue the government collects, which households lose the most relative to their income, or how much total surplus disappears. Those are connected but distinct questions.
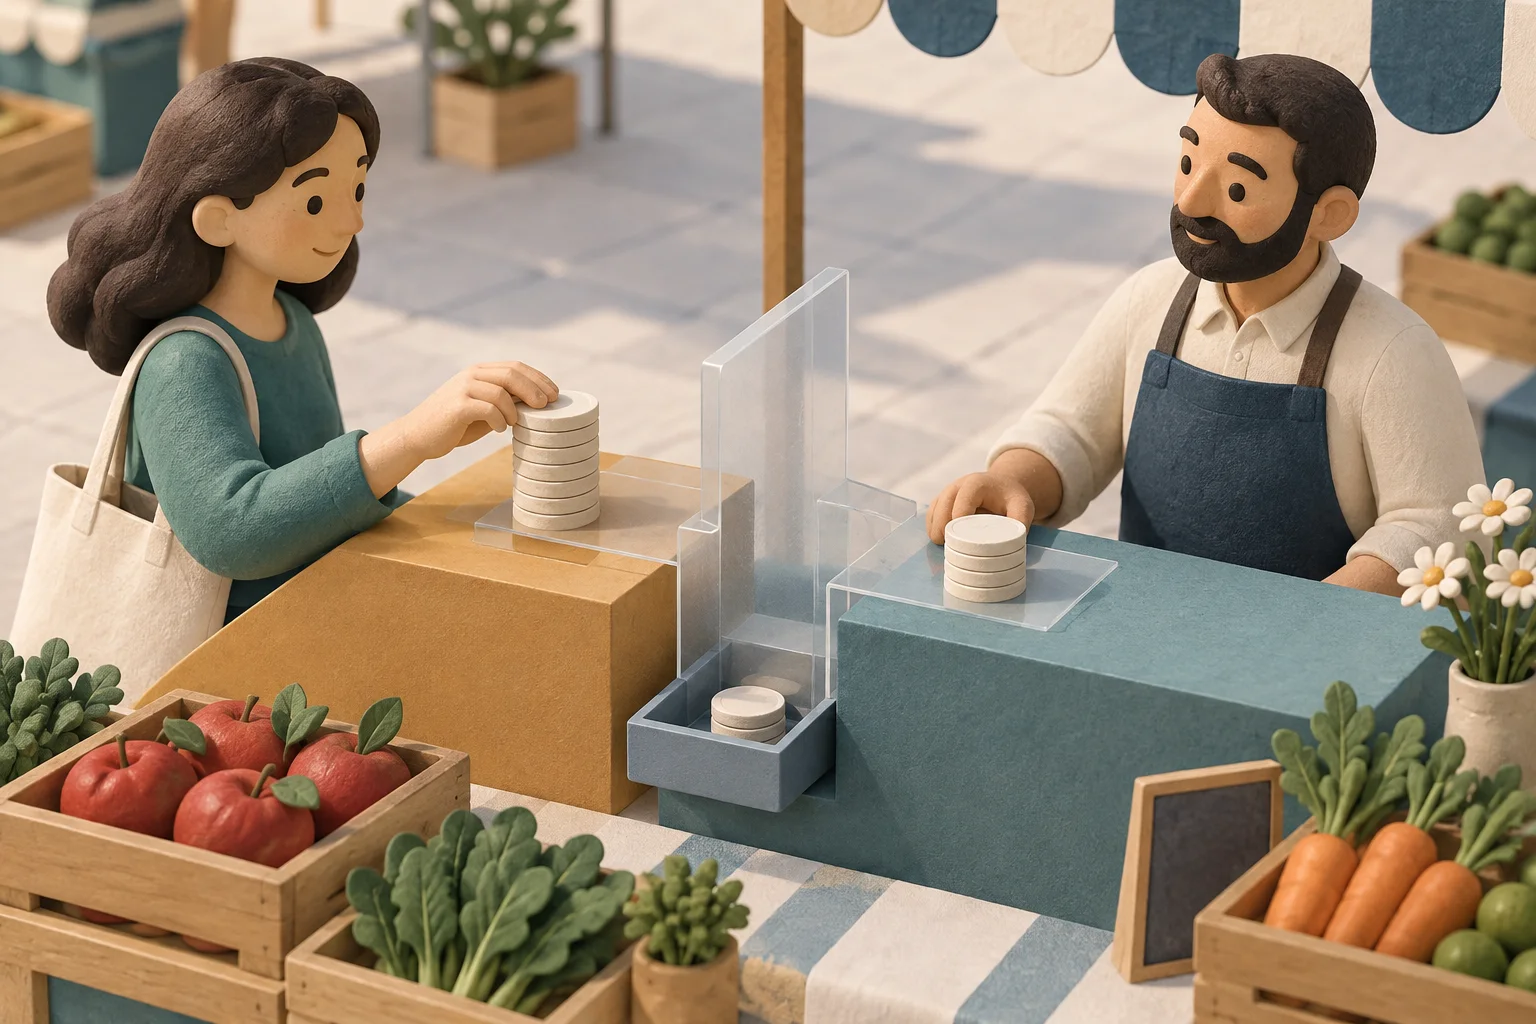
<!-- learn:illustration -->
The illustration below is conceptual: it shows a tax wedge passing through a market and the price pressure reaching both sides of a transaction. It contains no tax rates, observed prices, or country-specific rules.
Why elasticity determines the split in a competitive model
Price elasticity measures how strongly quantity responds to a price change. If buyers have few substitutes or need the good, demand may be relatively inelastic. If consumers can switch easily, demand may be more elastic. Supply is more elastic when producers can change output, enter or leave the market, or move resources to another use without a large cost.
For a small per-unit tax around a competitive market’s starting equilibrium, the standard model gives the approximate shares:
Buyer share of the tax wedge = εₛ ÷ (εₛ + |εᵈ|)
Seller share of the tax wedge = |εᵈ| ÷ (εₛ + |εᵈ|)
Here εₛ is the positive price elasticity of supply and εᵈ is the negative price elasticity of demand; the absolute value makes its size easier to compare. The buyer share is the increase in the price paid divided by the tax amount. The seller share is the fall in the price received divided by the tax amount. The two shares add to one under this model.
The direction can seem counterintuitive at first: the side that is less responsive to price changes generally bears more of the wedge. When demand is inelastic relative to supply, buyers cannot reduce purchases much, so a larger share appears as a higher buyer price. When supply is inelastic relative to demand, producers have fewer ways to redirect resources, so a larger share appears as lower net proceeds.
For example, if supply elasticity is 0.6 and the absolute demand elasticity is 0.8, the approximate buyer share is 0.6 divided by the sum of 0.6 and 0.8, or about 42.9%. The seller share is about 57.1%. These are shares of the per-unit price wedge in the model—not percentages of household income, total welfare loss, or observed tax bills. With a large tax, changing elasticities, or a different market structure, the local formula may not give the exact result.
A worked example with linear supply and demand
Suppose a hypothetical market has demand Qᵈ = 180 − 4Pᵦ and supply Qˢ = 40 + 3Pₛ. Before tax, buyers and sellers face the same price. Setting the two quantities equal gives a price of $20 and a quantity of 100 units. The local demand elasticity is −0.8 and the supply elasticity is 0.6 at that starting point.
Now impose a $7 per-unit tax and assume sellers remit it. The post-tax prices must satisfy Pᵦ − Pₛ = $7, while demand and supply must still agree on the traded quantity. The solution is:
- Buyers pay $23 per unit, which is $3 more than before.
- Sellers keep $16 per unit after remitting the tax, which is $4 less than before.
- The market trades 88 units, down from 100.
The seven-dollar wedge is split into a three-dollar increase in the buyer’s gross price and a four-dollar fall in the seller’s net receipt. Buyers account for 3 divided by 7, about 42.9% of the per-unit wedge; sellers account for 4 divided by 7, about 57.1%. The exact result matches the elasticity shares here because the example uses straight-line supply and demand curves over this range.
Tax revenue is $7 × 88 = $616. On the 88 units still sold, the buyer-side price increase accounts for $264 and the seller-side receipt decrease for $352; together they equal the $616 tax payment. The 12 units no longer traded also create a $42 deadweight-loss triangle in this particular linear model: one-half × $7 × 12. That $42 is lost surplus, not tax revenue and not an additional amount collected by the government.
Every value in this example is invented to show the mechanism. It assumes a single competitive market, constant straight-line curves, a fixed per-unit tax, no spillovers, and no change in product quality or other prices. Actual incidence requires evidence about a real tax change and a defensible no-tax comparison.
How the answer differs across tax types
For a sales tax or value-added tax, buyers may see a higher checkout price, while firms may absorb part of the wedge through smaller margins or lower payments to suppliers and workers. Pass-through varies by market conditions. CBO notes that the number of firms, the possibility of entry, and the relative price sensitivity of demand and supply can change how much of an indirect tax reaches consumers. Its budget-estimation treatment is specific to U.S. federal analysis, not a universal incidence estimate. {source:cboIndirectTaxIncidence}
For an employer payroll contribution, the statutory payer may be the employer, but the long-run economic burden can be shared through lower wages, benefits, employment, profits, or prices. The split depends on labor supply and demand, bargaining, the tax base, and the use of revenue. CBO says empirical evidence on payroll-tax incidence in the United States is limited and does not generally apply to changes in U.S. federal payroll taxes. Its own estimates rely on stylized models and vary with the specific rate, threshold, and tax base being changed. {source:cboPayrollTaxIncidence2021}
For a corporate income tax, shareholders are not necessarily the only affected group. Investment may change, capital may move across sectors or borders, and labor demand or consumer prices may respond. Theoretical and empirical results depend on assumptions about the economy, mobility, market structure, and the time horizon. A particular study’s estimate should not be turned into a universal allocation rule. {source:oecdTaxIncidence2017}
For a tariff, the importer is legally responsible for paying the customs duty, but some of the burden may be borne by foreign producers through lower export prices. CBO says the incidence of U.S. customs duties depends on the goods affected, market conditions, and the size of the duty; U.S. importers or consumers may share the burden with foreign producers. The legal payer alone does not determine that split. {source:cboIndirectTaxIncidence}
These examples concern the incidence of a tax in a defined market. The broader effect on household well-being also depends on which people buy the good, own the firms, work in affected industries, and receive benefits or public services financed by the revenue.
Why incidence changes over time and across markets
Elasticities are not permanent labels attached to a tax. In the short run, buyers may be tied to existing equipment, leases, or routines, and firms may be unable to change capacity. Over a longer period, buyers can switch products, suppliers can enter or exit, workers can move, and investors can redirect capital. If those alternatives expand, demand or supply may become more elastic and the incidence may shift.
Tax design can also affect more than one stage of production. A levy on an intermediate good changes the income available to pay capital and labor, while a tax at final sale applies to a different point in the supply chain. CBO’s U.S. budget-estimation method distinguishes taxes on intermediate-stage inputs from retail taxes when estimating the income and payroll tax revenue offset to an indirect tax. This is a federal budget-analysis method, not a universal incidence result. {source:cboIndirectTaxIncidence}
Evidence does not require the consumer price to rise by exactly the tax amount. A tax may be only partly passed through, fully passed through, or—in some settings—associated with a price increase greater than the statutory tax, sometimes called overshifting. CBO’s review notes that published evidence spans outcomes below and above full pass-through. This possibility is not the default prediction for every market; it is a reason to measure the actual price response rather than infer it from the statute. {source:cboIndirectTaxIncidence}
Payroll-tax evidence also illustrates why the time horizon and policy details matter. A change in a rate applied to all earnings is not equivalent to a surtax above a threshold. A partial-equilibrium estimate holds wider economic effects outside the model; a general-equilibrium analysis can include changes in output, labor demand, and how revenue is spent. CBO’s working paper separates these cases rather than offering one burden percentage for every payroll tax. {source:cboPayrollTaxIncidence2021}
Tax burden, tax revenue, and welfare are different measures
The tax burden may refer to the economic cost borne by one group, the distribution of costs across households, or the loss of surplus compared with a no-tax situation. The term needs a stated measure. A tax bill is an accounting payment; it is not automatically equal to the payer’s final economic burden.
Tax revenue is what the government collects. In the market example it equals the tax per unit multiplied by the quantity sold after tax. Revenue can finance transfers, services, or public investment. To assess the net fiscal effect on a household, analysts may need to consider both the tax and the spending or benefit funded by it. OECD’s cross-country wage-tax tables show formal amounts paid by employees and employers under specified household assumptions; the OECD cautions that economic incidence can differ as wages adjust. Those tables are not a complete measure of each household’s net welfare from government. {source:oecdTaxingWages2026}
The efficiency cost or deadweight loss is different again. In the standard supply-and-demand diagram, the tax prevents some trades that would have benefited both buyer and seller before the tax. The lost gains from those forgone trades are not transferred to the treasury. The amount depends on how quantities respond, the shape of the curves, and any external effects that the tax was intended to address.
Distribution also matters. A tax with the same price effect can take a larger share of a low-income household’s budget if lower-income households spend more of their income on the taxed item. Another tax may fall more heavily on owners of capital or on workers in an affected sector. Incidence analysis and a judgment about fairness are related but not identical: the first estimates who bears costs under a model or evidence; the second applies a social criterion.
How to evaluate a claim about who pays
Before accepting a statement that a tax “falls on” consumers, workers, or companies, ask:
- Is the statement about legal liability, the person who remits the payment, price pass-through, income changes, or welfare?
- Which tax base, rate change, market, country, and time period are being studied?
- What is the counterfactual: what would prices, wages, quantities, or returns have been without the tax?
- Which supply, demand, labor-market, or capital-mobility responses are included?
- Does the estimate cover only a partial-equilibrium market or wider effects, including public spending financed by the revenue?
- Is the result a theoretical prediction, an empirical estimate, or a statutory accounting table?
Tax incidence is not the same as a statutory tax rate, a household’s average or marginal tax rate, or the tax wedge between total labor costs and take-home pay. Those measures answer different questions. OECD’s *Taxing Wages* calculations, for example, standardize household and earnings assumptions to compare formal labor taxes across member countries; they do not claim that the same share of the economic cost must remain with the person listed as the payer. {source:oecdTaxingWages2026}
For related questions, see how taxes and transfers can stabilize household income during a downturn, how a fiscal multiplier measures an output response to fiscal policy, and what labor share says about income generated in production. Each guide examines a separate part of the fiscal and income picture.
Common questions
Q1If a business remits a sales tax, does it bear the tax?
It may bear part of it, but the remittance rule alone cannot show how much. The business may pass some of the tax through to buyers, absorb some in its net receipts, or affect supplier and worker payments. The result depends on the market and the period being studied.
Q2Does the less elastic side always bear more?
That is the standard prediction for a competitive supply-and-demand model with a defined tax and a specified equilibrium. Market power, adjustment costs, bargaining, changing tax bases, other policies, and wider economic responses can alter the observed result. State the model or evidence before applying the rule.
Q3Can buyers pay more than the full amount of a tax?
Some empirical studies find price increases greater than the tax amount in particular settings, a result called overshifting. It is not a universal outcome. Measure the price change against a suitable no-tax comparison and keep the finding tied to the market, period, and policy studied.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
A retailer is legally responsible for sending a sales tax to the government. What does that establish about economic incidence?
Choose an answer to see the explanation