

ETF Index Constituents vs. Holdings vs. Creation Baskets
An ETF’s benchmark constituents, published portfolio holdings, and authorized-participant basket serve different purposes and use different timestamps. Learn how to read each list without treating them as interchangeable.
In this guideAre index constituents, ETF holdings, and AP baskets the same list?
Short summary
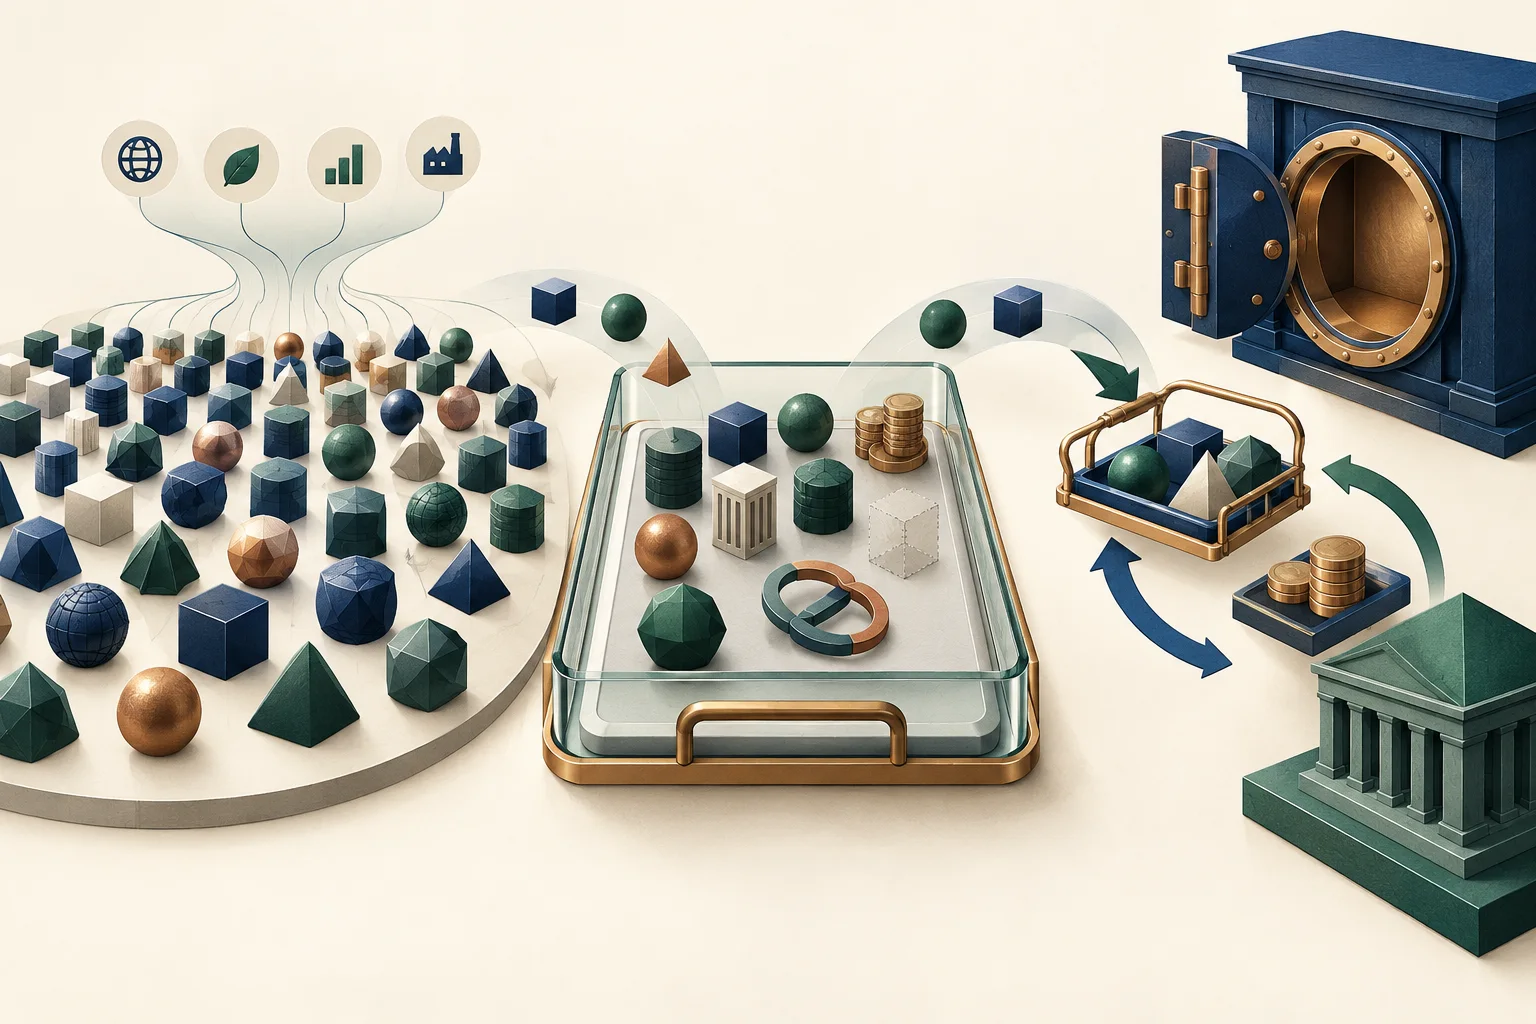
An index constituent list, an ETF holdings file, and a creation or redemption basket can overlap, but they do not answer the same question. The index describes a rules-based benchmark. The holdings file describes what the fund reports owning at a stated snapshot. The basket describes assets exchanged with an authorized participant (AP) for a large creation or redemption transaction. For U.S.-registered ETFs that rely on SEC Rule 6c-11, daily holdings disclosure and AP basket procedures have specific conditions. Other ETF structures can follow different disclosure arrangements. Always compare the definitions and timestamps shown by the index provider and fund.
Are index constituents, ETF holdings, and AP baskets the same list?
Usually not. An index constituent list identifies the securities selected under an index provider’s methodology, and may also show index weights and effective dates. An ETF’s portfolio holdings are the securities, assets, or other positions the fund actually holds at a particular time. A creation or redemption basket is a transaction set that the fund exchanges with an AP for a creation unit, sometimes with a cash balancing amount.
The lists may contain many of the same securities, especially when an index ETF closely follows its benchmark. Still, they serve different functions: a benchmark defines a measurement target, holdings report fund assets, and a basket specifies what is delivered or received in a primary-market transaction. A ticker appearing on one list does not by itself tell you whether it belongs on either of the others.
The phrase “published basket” can add to the confusion. Under Rule 6c-11, a qualifying ETF must publish daily portfolio holdings, but the SEC did not adopt a general rule requiring that each ETF publicly post a creation basket on its website. Some funds or market-data channels may make basket information available, but a public holdings page is not automatically the AP basket.
What does an index constituent list represent?
An index is a calculation built from a provider’s rules. The methodology sets its eligible universe, selection and weighting rules, treatment of multiple share classes and corporate events, and review schedule. The resulting constituent file says which securities count toward that benchmark under those rules, often with weights and dates showing when a change takes effect. You cannot buy the index itself; a fund can seek to track its results. Investor.gov’s index funds overview explains the basic role of an index fund, while S&P DJI’s U.S. Indices Methodology shows how a provider documents index scope, construction, weighting, and maintenance.
An index list can change on a scheduled rebalance or after an event covered by the methodology. Providers may publish proposed changes before their effective dates, so a file labeled “upcoming” is not necessarily the live constituent set yet. Check the file’s effective date and whether it describes current membership, a future rebalance, or a historical snapshot.
Also check what one row represents. An index may count securities or share classes separately, while a summary may report companies or issuers. A company with two eligible share classes can therefore appear as two securities in one file and one company in another. The methodology and file labels determine the right unit of comparison.
How can a fund follow the index without holding the identical list?
An index fund can use full replication or representative sampling, according to its prospectus and strategy. With full replication, a fund generally seeks to own all or substantially all index securities in roughly their benchmark weights. With representative sampling, it selects a subset intended to have similar aggregate characteristics, such as size, industry exposure, risk, yield, and liquidity. Sampling can lower practical trading burdens, but it means the holdings list may omit some constituents and can track the index differently.
An SEC-filed prospectus for one U.S.-registered index ETF describes full replication as its ordinary approach and allows representative sampling when acquiring certain constituents is impractical or restricted. It also permits some non-index investments and cash or derivative positions, subject to that fund’s own policies. That is an example of one prospectus, not a rule that every ETF follows the same approach. Read the named fund’s current prospectus to see which strategy it actually describes.
Even a fund that normally replicates an index may temporarily differ while it processes constituent additions, removals, weight changes, subscriptions, redemptions, or other portfolio activity. “Tracks the index” describes an objective and method; it does not mean every disclosed snapshot must equal the provider’s constituent file row for row.
What does a published holdings file show, and when is it dated?
For an ETF that relies on Rule 6c-11, the website must disclose each business day the portfolio holdings that form the basis of the next NAV calculation. Those holdings are as of the prior business day’s close, and the disclosure must be available before regular trading opens on the ETF’s primary listing exchange. The rule specifies identifiers, descriptions, quantities, and portfolio weights where applicable. So the file is a dated snapshot used for the next NAV—not a live feed of every intraday trade or a promise that each line still has the same weight later in the day.
“Holdings” can mean more than index stocks. The SEC’s Rule 6c-11 adopting release discusses disclosure of cash and positions such as short exposure or written options. SEC Form N-PORT also classifies investments such as cash-management vehicles and several types of derivatives. Depending on the fund and report format, a portfolio view may show cash, cash equivalents, derivatives, collateral, unsettled items, or other balance-sheet positions alongside ordinary securities.
Corporate actions can create temporary lines that are related to the portfolio but do not read like a settled index constituent. For example, an SEC-filed ETF shareholder report explains that a fund may use when-issued securities around a spin-off or reorganization before the resulting shares begin regular trading. Such entries are one reason not to treat every holdings row as an index member. Check each row’s instrument type and as-of date before interpreting it.
What is in a creation or redemption basket?
Under Rule 6c-11, a basket is the securities, assets, or other positions exchanged for creation units. An AP deposits the basket and any cash balancing amount to receive newly issued ETF shares; in a redemption, it returns a creation unit and receives the redemption basket and any balancing cash. The fund’s basket procedures specify what is acceptable. It can be built to resemble the portfolio, but it serves the primary-market exchange rather than reporting the complete portfolio.
A custom basket can be a non-representative selection of the fund’s holdings. The rule also treats a representative basket that differs from the initial basket used that same business day as a custom basket. ETFs relying on the rule must have written procedures governing baskets, with additional parameters and review roles for custom baskets. The exact permitted practice is fund-specific; do not infer it from the index methodology alone.
The SEC considered requiring a public website post of a daily published basket, but did not include that requirement in the Rule 6c-11 adopting release. The release says APs and other market participants can access basket information through channels such as the NSCC, an intermediary, or the ETF itself. The fund is required to keep records of baskets exchanged with APs. That does not make every actual AP basket a public, consumer-facing holdings file.
Why can the three lists differ on the same day?
They may have different purposes, data cutoffs, and units of measure. The index provider may show constituents and weights effective after a future rebalance. The fund’s daily holdings snapshot may reflect its prior-close portfolio before it completes the trades needed to align with that change. The AP basket may be a transaction-specific selection of assets, plus cash to balance value, rather than a pro-rata copy of the full holdings.
Consider a hypothetical benchmark with four securities at target weights of 50%, 25%, 15%, and 10%. A sampled fund might hold only three of them, add a small cash position, and use a derivative under its prospectus. Its creation basket for an AP may include a different subset plus cash. Each list can be accurate for its purpose and timestamp; they are not contradictory just because the rows do not match.
Differences can also arise from cash flows, fees, trading costs, portfolio rebalancing, securities lending, tax or regulatory constraints, corporate actions, and settlement timing. A fund can show the index’s intended exposures without matching its constituents, quantities, and weights exactly at every instant. Compare each source on its own terms before calling a difference an error.
How should you compare the files without mixing up their dates?
Start with the question you want to answer. For benchmark membership, use the index provider’s current constituent file and its effective date. For what a Rule 6c-11 ETF reports holding, use the fund’s daily website holdings file and its prior-business-day as-of date. For what an AP exchanges to create or redeem shares, use the relevant basket for that transaction and business day; it may not be posted in the public holdings section.
Then normalize the row identity. Compare security identifiers such as CUSIP or ISIN, not just company names or ticker text. Determine whether a row represents an issuer, share class, depositary receipt, derivative, cash balance, or temporary corporate-action instrument. When comparing weights, check whether they are percentages of the index, fund net assets, or a basket/creation unit, and whether shorts or cash are represented separately.
Finally, line up the times. A proposed index rebalance, a prior-close holdings file, an intraday market quote, and an AP basket for the next NAV are not simultaneous snapshots. Save the file timestamp and effective date before calculating an overlap or interpreting a difference. See ETF tracking difference versus tracking error for why fund returns can diverge from an index even when the portfolio is designed to follow it.
What can a fund website tell retail investors about baskets?
For ETFs within Rule 6c-11, public daily holdings disclosure is required, while actual creation/redemption basket disclosure is not generally required by that rule. A fund may voluntarily provide more information, and an AP may access the transaction file through the fund or market infrastructure. A retail holdings page may therefore be enough to inspect portfolio exposure, but not enough to reconstruct exactly what the AP delivered or received on a particular creation or redemption.
Not every U.S. exchange-traded fund follows the same disclosure route. In ADI 2025-15, SEC staff explains that ETFs outside Rule 6c-11 rely on separate exemptive orders with their own conditions. Some semi-transparent or non-transparent ETFs may publish a tracking basket designed to represent holdings without showing the actual portfolio. Do not label such a tracking basket as actual holdings unless the fund’s materials say that is what it is.
For any fund, its prospectus and website should identify its approach and disclosures. Check whether a listed “basket” means portfolio composition file, creation basket, redemption basket, or a tracking basket. If the terms are unclear, the fund’s AP and basket policies are more relevant than the index provider’s constituent list.
What checklist helps answer “which list am I looking at?”
Read the column heading and the document title first. Is the source an index constituent file, a daily portfolio holdings file, a monthly regulatory filing, an AP creation/redemption file, or a tracking basket? Record its provider or fund, the as-of date, the effective date, and the time it was posted. A page updated today can still contain positions measured at yesterday’s close.
Check the fund’s stated index-tracking method, including whether it uses full replication, sampling, cash, derivatives, or other investments. Then compare security identifiers and weights on a consistent basis. If a row appears only in the fund file, look for cash, derivatives, share-class differences, a corporate action, settlement balance, or a date mismatch before concluding that the benchmark changed.
For a basket, confirm whether it is for creation or redemption, which business day and creation unit it applies to, whether cash balancing is included, and whether it is identified as custom. Do not use that transaction list as a substitute for index membership or the complete holdings snapshot. For the mechanics of those AP exchanges, see how ETF creation and redemption works. For market-price gaps around portfolio value, see ETF NAV versus market price.
Common questions
Q1Why is a fund’s holdings count different from its index’s constituent count?
A fund may use sampling, hold cash or derivatives, carry temporary positions, or report rows by security rather than company. The index file and fund file may also use different as-of or effective dates. Compare the file definitions and identifiers before treating a count difference as a problem.
Q2Is the AP creation basket usually public on the ETF’s website?
Not necessarily. Rule 6c-11 requires qualifying ETFs to publish daily portfolio holdings but does not generally require public website publication of each creation or redemption basket. A fund or market-data channel may provide basket files to APs or other participants.
Q3Is a tracking basket the same as the ETF’s actual holdings?
Not always. SEC staff notes that some semi-transparent or non-transparent ETFs publish a tracking basket designed to represent the portfolio without disclosing the actual holdings. Check the fund’s own description to identify which dataset it is publishing.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What does an ETF’s daily holdings file primarily describe?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guidePut optionA contract that gives its holder the right, but not the obligation, to sell the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide