

How ETF Creation and Redemption Works
See how authorized participants exchange baskets for ETF creation units, how redemption runs in reverse, and why the process can narrow—but never guarantee away—premium and discount gaps.
In this guideU.S. registered ETFs have a primary market and a secondary market
Short summary
A U.S. registered ETF has two connected markets. Investors usually trade existing shares with one another on an exchange. Separately, an authorized participant (AP) can transact directly with the fund in large creation units: it exchanges a designated basket and any cash balancing amount for newly issued ETF shares, or returns ETF shares in a creation unit for the basket or its cash equivalent. These creations and redemptions give market participants a way to respond to price gaps around portfolio value. They can help narrow a premium or discount, but costs and risk mean there is no guaranteed price or automatic correction.
U.S. registered ETFs have a primary market and a secondary market
ETF shares trade throughout the day at market prices on an exchange or other trading venue. That is the secondary market where most retail orders are matched. In the primary market, the fund itself issues or redeems shares in large creation-unit aggregations through authorized participants under the ETF’s procedures. The SEC’s ETF compliance guide describes this structure for eligible registered open-end ETFs that issue and redeem creation units for baskets and any cash balancing amount.
This guide focuses on U.S. ETFs registered as investment companies. Commodity ETPs and ETNs fall outside that scope, and rules also vary across jurisdictions. Registered ETFs do not all rely on the same regulatory framework: some, including unit investment trusts, may operate under exemptions other than Rule 6c-11. Check the specific fund’s prospectus and website for its creation-unit size, basket process, and disclosures.
An authorized participant is an institutional counterparty to the fund
An AP is generally a financial institution, often a large broker-dealer, with an agreement that allows it to place orders directly with an ETF to create or redeem creation units. The SEC’s Investor.gov definition and ETF bulletin explain that APs are typically large institutions and that ordinary retail investors normally buy and sell ETF shares in market transactions instead.
An AP is not the ETF manager and is not a guarantor of liquidity or price. The ETF and AP follow a contractual process for basket delivery, settlement, and fees. APs may decide whether the economics justify participating in a particular creation or redemption; the mechanism does not obligate them to absorb every imbalance or keep the market price at NAV.
Creation exchanges a basket for newly issued ETF shares
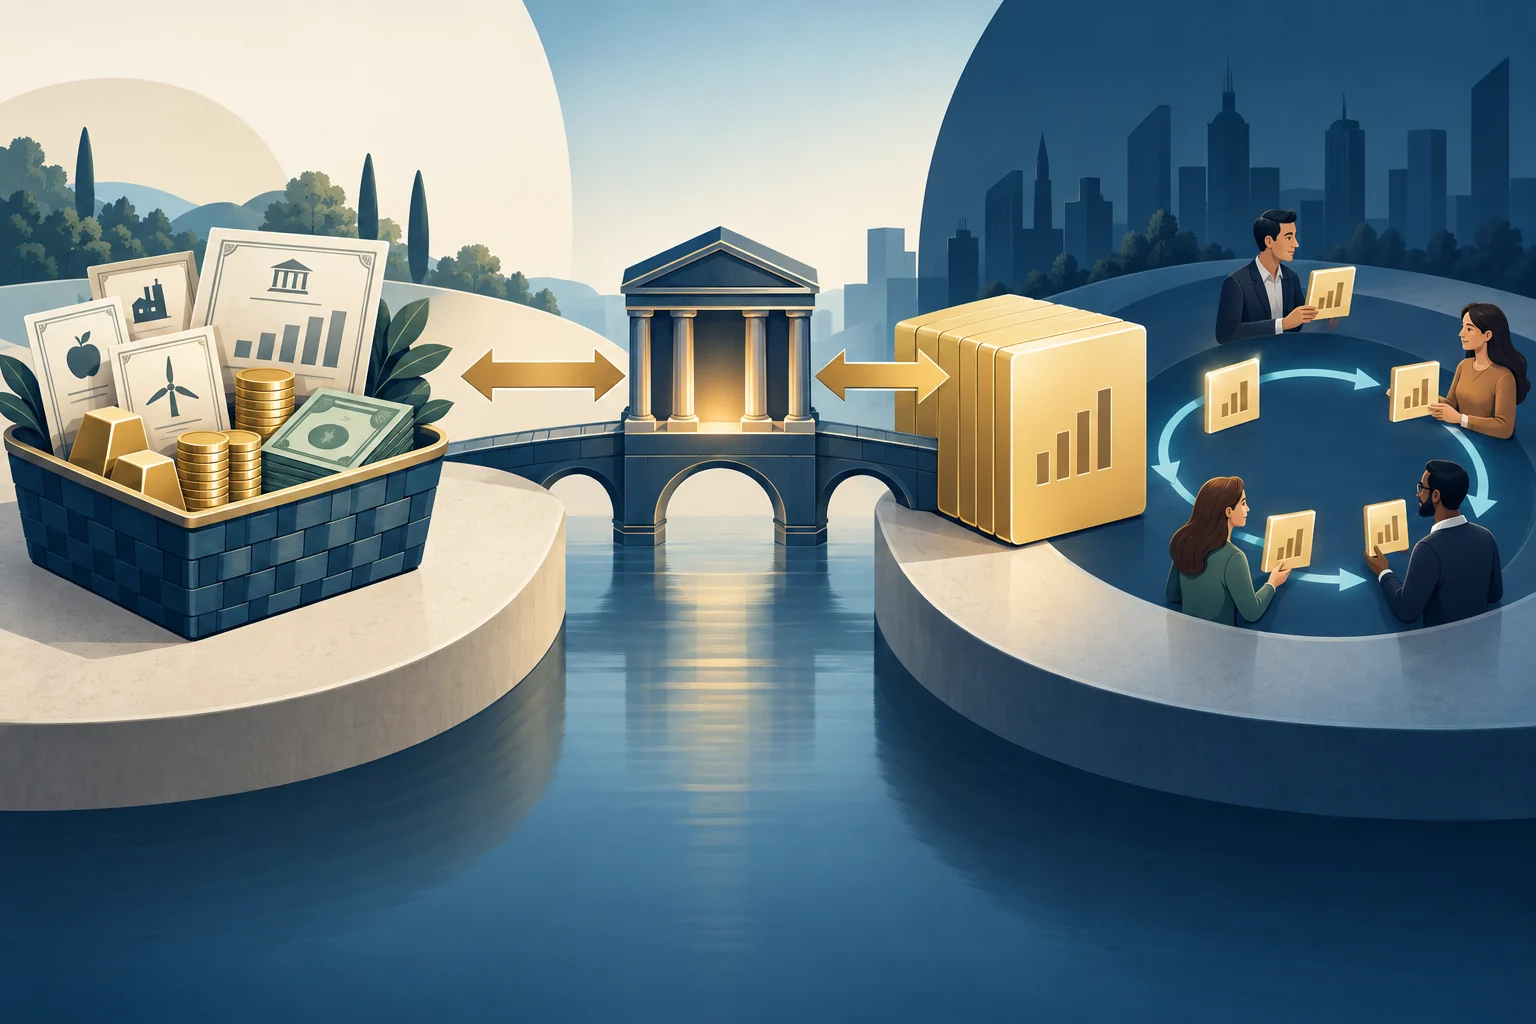
When demand for ETF shares is strong, an AP may assemble the fund’s designated basket of securities, assets, and possibly cash, then deliver it to the ETF or its service provider. The fund issues a creation unit of ETF shares in exchange. The AP can then sell those shares on an exchange or use them in other transactions. A basket generally reflects the fund’s portfolio, but its exact composition and any cash balancing amount are set under that ETF’s procedures; they need not be identical for every fund or date.
For a clearly hypothetical scale example, assume one ETF creation unit contains 20,000 shares and the reference value is $100 per share. That unit represents $2,000,000 before any cash balancing amount, transaction fees, financing, hedging, or other costs. The share count is an assumption for this arithmetic only—creation-unit sizes vary by ETF and are set by the product’s documents.
Redemption reverses the exchange
To redeem, an AP obtains a creation unit of ETF shares—often by buying shares in the secondary market—and delivers that unit to the fund. In return, it receives the pre-defined basket of securities or other assets, plus or minus a cash amount if the basket’s value needs to be balanced. The AP may sell, hold, or hedge the received assets. Investor.gov describes this as the reverse of creation: ETF shares go to the fund, and the basket or cash equivalent comes back.
The basket is not necessarily a pro-rata slice that an individual investor can request. Funds set basket procedures, and eligible ETFs may use custom baskets under written policies. Cash substitutions, transaction fees, and different settlement cycles can apply. The SEC’s Rule 6c-11 release discusses basket policies, custom baskets, and settlement complications that can arise when foreign-market holidays or local delivery cycles delay transfers.
Creation and redemption can narrow a premium or discount
Suppose an ETF share trades above a current, tradable estimate of the basket’s value. If an AP can acquire the basket, exchange it for newly issued ETF shares, and sell those shares at the higher market price, the added share supply may put downward pressure on the ETF premium. If the ETF trades below basket value, an AP may buy ETF shares, redeem a creation unit, and sell or hedge the received basket. That demand for ETF shares may reduce the discount.
This is the basic arbitrage link between the exchange price and the fund’s portfolio value. Investor.gov explains that AP arbitrage can help keep the market price close to NAV. “Can help” is the right expectation: it describes an incentive and a mechanism, not a promise that a gap disappears immediately or completely. For more on reading the gap itself, see [ETF NAV versus market price](/en/learn/etf-nav-vs-market-price-premium-discount-explained).
The arbitrage trade has costs, timing, and market risk
Basket securities may be costly or difficult to trade, borrow, hedge, or settle. APs and other market participants also face bid-ask spreads, transaction charges, financing costs, price changes during execution, and the risk that the basket will not track the ETF closely enough. The SEC’s Rule 6c-11 adopting release notes that trading costs and exposure to changing prices can lead arbitrageurs to wait until a price gap is large enough to justify the risk. Limited AP participation can also leave larger deviations.
Closed underlying markets add another complication. An international ETF can trade in the United States while foreign holdings are not, leaving less certain current prices and more difficult hedges. Local holidays, transfer schedules, and settlement rules can delay basket delivery. See [why an ETF can move while its underlying market is closed](/en/learn/etf-price-when-underlying-markets-are-closed-explained). Lower volume or a wide live spread can also raise the cost of arbitrage; [ETF trading volume versus liquidity](/en/learn/etf-trading-volume-vs-liquidity-explained) explains why past volume alone does not describe the available market now.
A retail buy or sale does not create or redeem fund shares
If you buy 10 ETF shares through a brokerage account, you usually buy existing shares from a seller or another market participant in the secondary market. The fund does not create a new block in response to that individual order. Likewise, selling your 10 shares usually transfers them to a buyer; it does not send them back to the fund for the underlying basket.
Creation and redemption happen at the institutional primary-market layer in large units. Retail investors still affect supply and demand in the secondary market, and AP activity can connect that market to the basket, but no single retail trade guarantees that an AP will step in. ETF shares may trade at a premium or discount, and your execution price can differ from NAV.
In-kind redemptions can have a limited fund-level tax benefit
When a fund redeems shares by delivering securities in kind instead of selling those holdings for cash, the fund may avoid realizing gains that a sale could create inside the portfolio. This can reduce some portfolio transaction costs and may help limit capital-gain distributions to shareholders. The SEC’s ETF bulletin says in-kind exchanges can contribute to ETF tax efficiency, and its Rule 6c-11 release explains that in-kind redemptions can avoid some taxable events and costs associated with selling securities for cash within the ETF.
That is a potential feature, not a tax-free guarantee. Cash components, portfolio sales, fund structure, account type, and an investor’s tax jurisdiction can still matter. It also does not mean an AP or an investor has no tax consequences on its own transactions. The potential benefit concerns how the fund may handle portfolio assets; it does not determine the tax result for every shareholder or ETF.
What an ETF investor can and cannot infer from the mechanism
The creation-redemption system can help connect ETF share prices with the value and tradability of a basket. It does not make every ETF equally liquid, force its market price to equal NAV, or ensure an AP will transact at the moment you want to buy or sell. Check the fund’s creation-unit and basket disclosures, compare the live bid and ask with the relevant NAV timestamp, and consider your order size and costs.
Use the mechanism as context for understanding ETF prices—not as a price guarantee. A premium or discount may persist when hedging is expensive, underlying markets are closed, settlement is difficult, or APs see too little expected profit for the risk.
Common questions
Q1Can any investor create or redeem ETF shares directly with the fund?
Usually not. In this U.S. registered ETF structure, an AP with the required agreement places primary-market orders in creation units. Retail investors generally buy and sell individual shares in the secondary market.
Q2Does arbitrage guarantee that an ETF trades at NAV?
No. Creation and redemption can make it worthwhile for APs or other market participants to trade against some price gaps, but costs, risk, basket access, and settlement can leave a premium or discount in place.
Q3Does an in-kind redemption make my ETF investment tax-free?
No. In-kind transfers may help a fund avoid realizing some gains through portfolio sales, but they do not determine the tax treatment of every fund, account, or investor. Local rules and your own transactions still matter.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
In a typical creation, what does an AP deliver to the ETF in exchange for a creation unit?
Choose an answer to see the explanation