

Do Bank Reserves Create Money? Loans, Deposits, and the Multiplier
Learn what bank reserves are, how loans create deposits, what the textbook money multiplier assumes, and why QE does not guarantee a fixed rise in broad money or inflation.
In this guideWhat is a bank reserve?
Short summary
Bank reserves are balances that eligible banks hold at their central bank. A bank loan usually creates a matching deposit for the borrower; it does not hand the borrower central-bank reserves. The textbook money multiplier is a conditional classroom model, not a reliable fixed forecast of modern lending, deposits, or inflation.
What is a bank reserve?
In the United States, a reserve balance is a deposit a depository institution holds in its account at a Federal Reserve Bank. It is an asset for that institution and a liability of the Federal Reserve. The balance can be used to settle payments between banks, manage liquidity, and meet applicable regulatory requirements. A household's checking account is a claim on its commercial bank; it is not a reserve account at the Fed. The [Federal Reserve's reserve-balance FAQ]({source:fedIorbFaq}) describes who holds reserves and why.
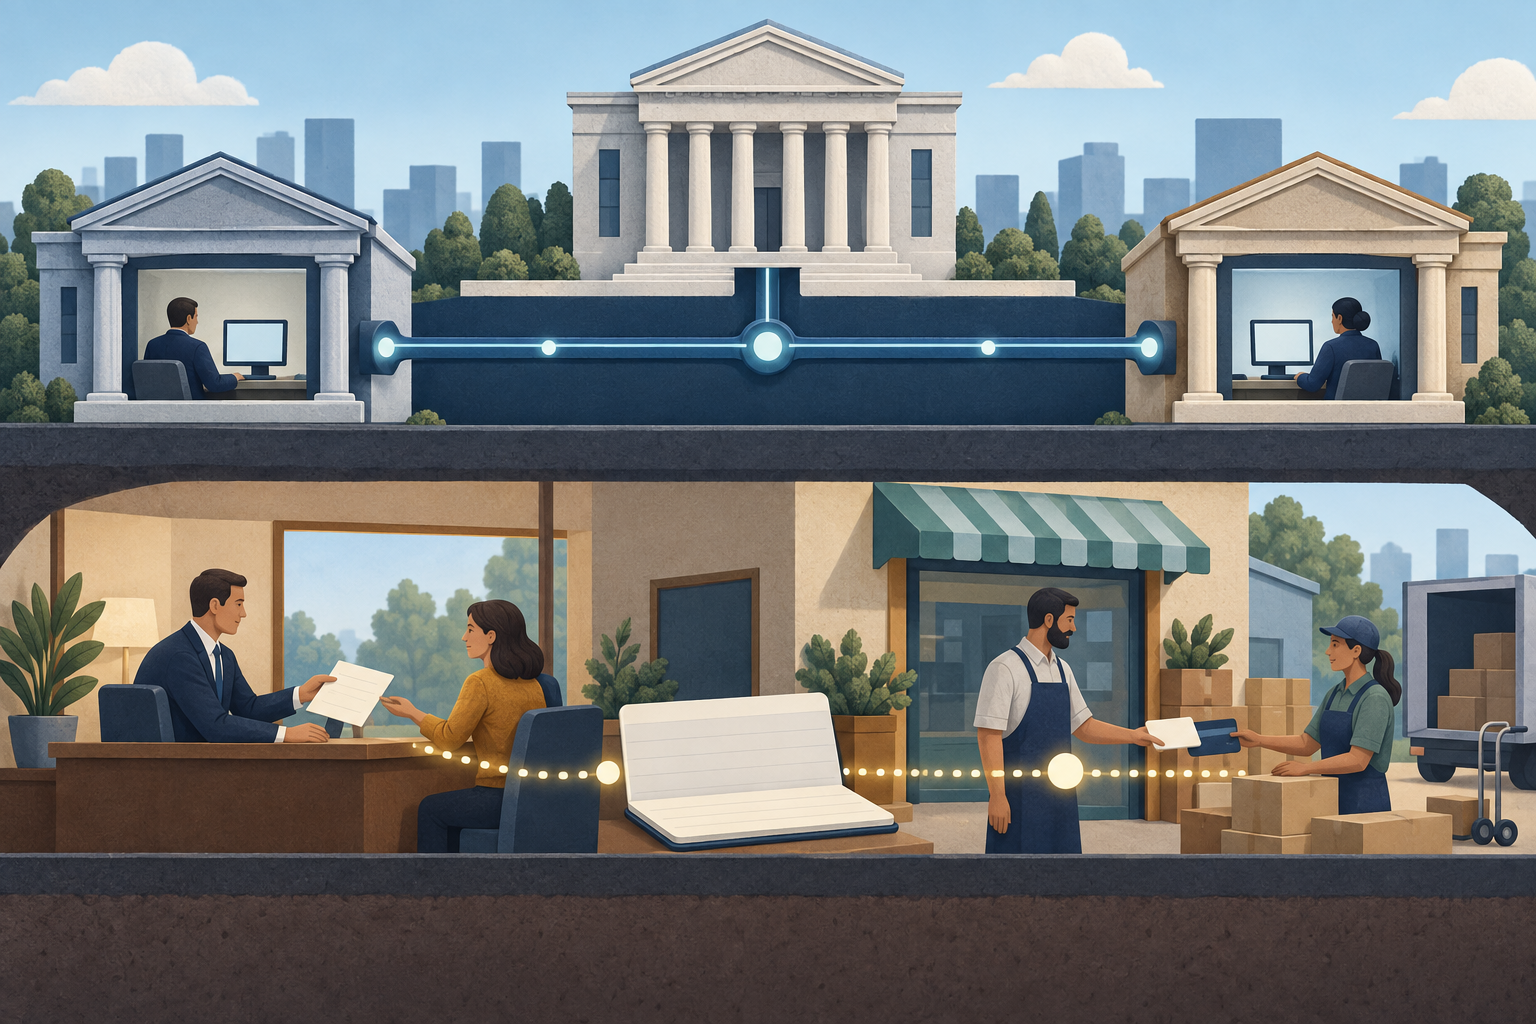
If a customer at Bank A pays someone who banks at Bank B, the banks settle the payment by adjusting their reserve balances. Bank A's customer's deposit falls and Bank A sends reserves; Bank B receives reserves and credits its customer's deposit. The reserves move between eligible institutions, while the recipient receives a commercial-bank deposit. A bank does not send a household a reserve balance as the payment.
Reserves, the monetary base, M1, and M2
These terms count different things. In current U.S. Federal Reserve statistics, the monetary base is currency in circulation plus reserve balances held by depository institutions. M1 and M2 instead describe selected money-like assets held by the public. Current U.S. M1 includes public-held currency, demand deposits, other checkable deposits, and savings deposits, subject to the release's specified exclusions and adjustments. M2 adds small-denomination time deposits and retail money-market-fund balances, with specified retirement-balance adjustments. The precise categories are statistical definitions, not universal labels. The [current H.6 release]({source:fedH6Current}) publishes the U.S. components, and the [Fed's money-supply FAQ]({source:fedMoneySupplyFaq}) summarizes the measures.
So a rise in reserve balances can raise the U.S. monetary base without mechanically adding the same amount to M1 or M2. Reserves are held by eligible institutions at the central bank; they are not the checking and savings deposits counted as public money. Other countries use their own monetary aggregates and settlement systems, so check the local central bank's definitions before comparing series across borders.
This distinction also prevents a common chart-reading mistake: reserve balances, bank deposits, and the monetary base are stocks measured at a date, while lending and payments are flows over a period. Comparing their growth rates requires the same dates, units, seasonal treatment, and definition. For the contents of U.S. M1 and M2, see M1 vs. M2; for a separate ratio involving nominal GDP, see M2 velocity.
What happens when a bank makes a loan?
Consider a bank approving a hypothetical $10,000 business loan. At origination, it records a $10,000 loan asset and credits the borrower's deposit account by $10,000, creating a matching deposit liability. The borrower can then use that deposit to pay a supplier. The bank has not taken $10,000 of reserves out of a vault and handed them to the borrower; the borrower receives a bank deposit that can be spent.
That is double-entry bookkeeping, not free wealth. The borrower owes $10,000 and must repay under the contract; the bank holds a loan claim and owes the deposit. If principal is repaid from a deposit at the lending bank, that bank reduces its loan asset and deposit liability together. If payment comes from another bank, the borrower's bank reduces the deposit while the lender receives reserves and reduces its loan asset. In either case, principal repayment reduces deposit money across the banking system. Interest payments are different: they are income to the bank and are not a repayment of loan principal.
Payments still matter for reserves. If the borrower pays a supplier at another bank, the deposit moves from the borrower's bank to the supplier's bank, and reserves settle between those banks. That settlement can create a funding or liquidity need for the lending bank. But it does not mean the bank first lends reserves to the public. The [Bank of England's explanation of modern money creation]({source:boeMoneyCreation}) lays out the loan-and-deposit entries and the separate role of settlement.
How does the textbook money multiplier work?
A simple textbook model starts with a fixed required-reserve ratio. If that ratio is 10%, the basic deposit-multiplier formula is 1 ÷ 0.10 = 10. In a stylized chain, a first $100 deposit is partly retained as required reserves; the remainder is lent and then redeposited at another bank. Repeating that process can produce up to $1,000 in total deposits in the model. The total includes the initial $100 deposit; it is not $1,000 of new lending on top of it.
That result depends on strong assumptions: the reserve ratio binds, banks do not hold excess reserves, the public does not keep cash outside banks, every loan is made and redeposited, and borrowers are willing and creditworthy. The model also needs a clearly defined starting injection and a consistent definition of deposits. Change those assumptions and the result changes. The ratio is useful for learning how a constrained, repeated-redeposit model works; it is not a promise that one extra dollar of reserves produces ten dollars of new loans.
Why is there no fixed modern multiplier?
In practice, a bank weighs the expected return on a loan against its funding cost, credit risk, capital position, liquidity needs, and regulatory requirements. It also needs a willing, creditworthy borrower. Those decisions affect how much it lends. After a loan is booked, the bank must be able to fund payments and manage liquidity; reserves help with settlement, but they are not a stock that banks mechanically pass to households.
The U.S. example makes the textbook assumption especially visible: the Federal Reserve reduced reserve-requirement ratios to zero effective March 26, 2020. That change did not remove other capital, liquidity, supervisory, or risk-management constraints, and it does not describe every country. The [Federal Reserve's reserve-requirements page]({source:fedReserveRequirements}) documents the U.S. change. Federal Reserve research and the Bank of England's account both caution against treating the simple multiplier as a mechanical account of modern money creation ({source:fedMoneyMultiplierResearch}, {source:boeMoneyCreation}).
Central banks still influence credit through monetary policy. Policy rates affect borrowing costs and demand; liquidity facilities and payment arrangements shape how banks manage settlement. A bank that expects outflows may seek funding or reserves from other institutions or the central bank, subject to the relevant framework. This is a real constraint on a bank's operations, but it is different from saying that all lending waits for a fixed pile of reserves to be multiplied first.
What does quantitative easing change?
When a central bank buys a security, it pays by crediting a bank's reserve account. If the seller is a bank, the simplified balance-sheet change is an exchange: the bank holds more reserves and fewer securities. That transaction alone does not add a customer deposit to the bank's liabilities. The Federal Reserve describes its purchases of Treasury securities as adding reserves to the banking system ({source:fedIorbFaq}).
If the seller is a nonbank, such as a pension fund, the settlement is different on the private side. The seller gives up a security and receives a deposit at its bank; that bank receives reserves and records the customer's new deposit liability. In that simplified example, both reserve balances and a nonbank deposit rise. The Bank of England describes this deposit channel in its discussion of QE purchases from nonbank financial companies ({source:boeMoneyCreation}). The exact chain depends on who sells and how the transaction settles, which is why “QE adds reserves” does not by itself tell you the change in each broad-money measure.
QE is a policy action intended to ease financial conditions through asset purchases. Its effects can depend on the assets purchased, sellers, portfolio choices, rates, credit demand, and the broader economy. A larger reserve balance does not imply a fixed multiple of bank loans, an equal increase in M2, or a guaranteed rise in consumer prices. The article on Federal Reserve rates and the prime rate covers a separate part of the policy-transmission chain.
How do reserves fit into interest-rate policy?
Reserves matter because banks use them for payments and because central banks use the terms on which reserves are held to implement monetary policy. In the United States, the Federal Reserve pays interest on reserve balances to eligible institutions. It uses the IORB rate as a tool to help keep short-term market rates in line with the Federal Open Market Committee's policy stance. This is a U.S. operating framework, not a universal template ({source:fedIorbFaq}).
The target rate, the rate on reserve balances, and a bank's customer lending rate are related through markets and institutions, but they are not the same rate. A change in a policy rate may influence loan rates and credit demand without mechanically dictating a fixed quantity of new loans. Other central banks may use different instruments, eligible counterparties, and reserve-account rules.
A checklist for claims about reserves and money growth
When a headline says reserves “surged” or QE “printed money,” first identify the series and its unit: reserve balances, the monetary base, M1, M2, or another country's measure. Check whether the statement refers to a stock at a date or a flow over a period, and note whether the data are nominal, seasonally adjusted, or revised. The latest U.S. H.6 release separates reserve balances and the monetary base from M1 and M2.
Next, ask what transaction changed the balance sheet and who sold the asset. A bank loan can create a deposit; a payment between banks changes where deposits and reserves sit; a security purchase can swap assets for reserves or add a nonbank deposit depending on the seller. None of these accounting entries alone determines future lending, spending, or inflation. To assess those outcomes, examine credit conditions, policy rates, borrower demand, bank capital and liquidity, output, and prices over the same period.
Use the money multiplier as a model with stated assumptions, not as a forecast detached from those assumptions. A careful statement names the country, aggregate, period, starting balance, and mechanism. Without them, “more reserves means ten times more money” collapses several distinct balance sheets into one claim.
Common questions
Q1Are bank reserves included in M2?
Not in the current U.S. H.6 definition. Reserve balances are held by depository institutions at Federal Reserve Banks and are included in the monetary base. U.S. M2 measures selected money-like assets held by the public. Other countries define their aggregates separately.
Q2Can banks lend reserve balances to households?
No. A household receives a commercial-bank deposit when a bank makes a loan. Reserve balances are accounts at the central bank and can be transferred between eligible institutions to settle payments. Banks can lend and borrow in ways that affect their funding and reserve positions, but a household does not receive a reserve-account balance.
Q3Does quantitative easing guarantee inflation?
No. QE changes central-bank asset holdings and reserve balances, and purchases from nonbanks can also raise bank deposits. The eventual effect on spending and prices depends on monetary conditions, portfolio choices, credit demand, supply, and other factors. Reserve growth alone is not an inflation forecast.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
When a commercial bank books a new $10,000 loan, what is the usual matching entry at origination?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide