

Why Mortgage Rates Do Not Move One-for-One With the 10-Year Treasury
See how Treasury yields, mortgage-backed securities, prepayment risk, lender costs, and borrower terms shape U.S. mortgage rates.
In this guideWhat does the 10-year Treasury yield tell you?
Short summary
A 10-year U.S. Treasury yield is an important reference for long-term borrowing, but it is not the rate a lender must charge on a 30-year mortgage. Most U.S. fixed mortgages are influenced by agency mortgage-backed securities (MBS), whose cash flows can change when borrowers refinance or move. MBS pricing, lender and servicing costs, guarantee fees, market capacity, and borrower-specific loan terms all sit between a Treasury benchmark and an individual quote. The spread between them can widen or narrow, so the two rates often move together without moving by the same number of basis points.
What does the 10-year Treasury yield tell you?
The 10-year Treasury yield is the market yield on a U.S. government security with payments extending over a long horizon. It reflects investors’ pricing of expected short-term interest rates, inflation, and compensation for holding duration, among other influences. It is useful as a broad benchmark for long-term rates because its maturity is nearer to the economic life of many fixed mortgages than overnight rates are.
The benchmark is not a direct input that determines every mortgage offer. A lender does not take the 10-year yield, add a permanent markup, and arrive at a retail mortgage rate. Borrowers can refinance, sell, or pay down a mortgage before its contractual 30-year maturity. A mortgage therefore has a changing expected cash-flow profile, while a Treasury note’s payment schedule is fixed. The two securities do not have identical duration, optionality, liquidity, or investor base.
Freddie Mac describes a positive historical relationship between the 10-year Treasury yield and the average 30-year fixed mortgage rate, but notes that they do not move in lockstep and that their spread can vary. The 10-year yield is a useful reference point, not a mortgage-rate formula or a quote for a particular household.
Why compare a 30-year mortgage with a 10-year yield?
“Thirty-year” describes a mortgage’s maximum scheduled repayment period, not the time every borrower is expected to keep it. Home sales, refinancing, extra principal payments, and defaults change how long the loan cash flows actually remain outstanding. Investors who buy mortgage securities care about that uncertain timing as well as about the contractual final maturity.
This makes a 10-year Treasury a convenient comparison, not a perfect duration match. A mortgage-backed security’s effective duration changes with interest rates and assumptions about borrower behavior. When rates fall, refinancing may return principal sooner; when rates rise, refinancing may slow and principal can remain outstanding longer. That changing timing is one reason MBS yields can diverge from Treasury yields. See the guide to MBS prepayment, extension, and convexity risk for the cash-flow mechanics.
Analysts may instead compare mortgage rates with an MBS yield, a Treasury yield of another maturity, or a swap rate. Each comparison answers a somewhat different question. Before calculating a spread, match the date, the instrument, the quoted yield convention, and the market stage being discussed.
How does the secondary MBS market enter the chain?
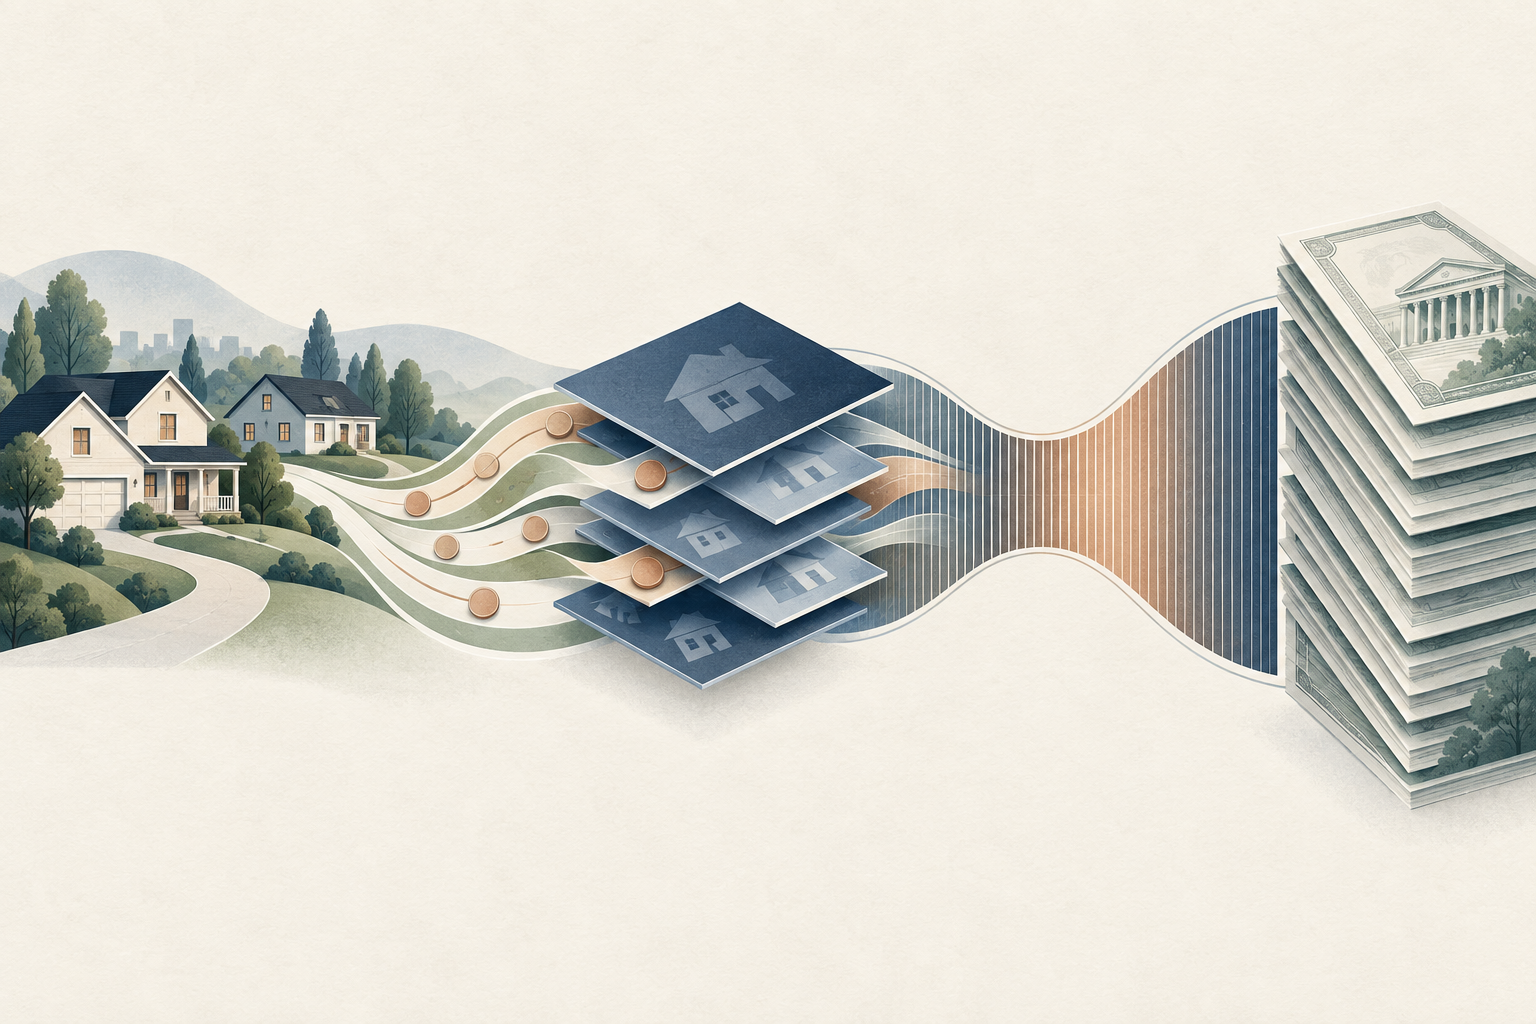
Many U.S. conforming mortgages are sold by lenders to Fannie Mae or Freddie Mac, which may place the loans into agency MBS. Investors price those securities based on the expected principal and interest they will receive, the guarantee structure, prepayment behavior, liquidity, supply, and demand. The MBS market gives lenders a way to transfer or hedge mortgage exposure and helps connect mortgage production to capital-market pricing.
A change in Treasury yields can affect MBS prices because investors compare the return and risks of mortgages with other fixed-income securities. But MBS carry embedded borrower options: homeowners can repay early, especially when refinancing becomes attractive. Investors may demand more yield to hold securities whose cash-flow timing is uncertain or whose prepayment exposure is difficult to hedge. Mortgage spreads can also respond to MBS issuance, investor demand, risk capacity, liquidity, and other conditions.
The New York Fed’s research on mortgage spreads finds that MBS yield spreads vary across securities and over time; prepayment risk is one contributor, while other factors that move with MBS supply and credit risk in fixed-income markets also matter. A wider MBS-versus-Treasury spread does not identify a single cause by itself. Nor is every observed spread a pure compensation for one risk: the compared securities have different cash flows and market conventions.
What do mortgage-Treasury and primary-secondary spreads mean?
The mortgage-Treasury spread is usually a simple yield difference between a specified mortgage-rate measure and a specified Treasury yield. It is a descriptive comparison, not a standardized fee and not a complete breakdown of the mortgage price.
The primary-secondary spread compares a retail mortgage-rate measure available to borrowers with a secondary-market measure such as an agency MBS yield. It can reflect the costs and risks of turning a loan into a security and delivering a quote to a borrower: lender operating costs, rate-lock pipelines, hedging, servicing, guarantee charges, capital use, and the lender’s margin can all be relevant. The exact measure depends on which primary rate and which secondary yield are selected.
These two spreads should not be mistaken for separately invoiced charges. Freddie Mac’s PMMS is a primary-market benchmark, while an MBS yield is a secondary-market price measure. They represent different stages and securities. Loan coupon rates, pass-through cash flows after servicing and guarantee fees, MBS yields, and PMMS rates are not identical objects. A subtraction helps frame a question, but it does not prove how much any one participant earned.
How can a mortgage rate rise while Treasury yields fall?
Consider a deliberately simplified illustration. On one date, suppose a 10-year Treasury yields 4.00%, a representative agency MBS yield is 4.60%, and a hypothetical 30-year mortgage quote is 6.25%. The MBS-versus-Treasury difference is 0.60 percentage points; the quote-versus-MBS difference is 1.65 points. Those rounded differences describe this example only. They are not live market data or an accounting identity for actual loan cash flows.
Now suppose the Treasury yield falls 0.25 percentage points to 3.75%, while the MBS-versus-Treasury spread widens by 0.40 points to 1.00%. The illustrative MBS yield would rise to 4.75%. If the quote-versus-MBS difference stayed at 1.65 points, the example mortgage quote would rise to 6.40%. Treasury yields fell, yet the mortgage quote rose, because the spread widened by more than the benchmark fell.
The reverse can happen too. Treasury yields can rise while mortgage rates move only a little if MBS spreads narrow, lenders change margins, or market conditions improve elsewhere in the chain. In practice these pieces may all change at once. Borrowers should read the example as a way to understand spread arithmetic, not a forecast or a claim that any specific rate will follow it.
What can make the spread widen or narrow?
Mortgage and Treasury yields may diverge when investors reassess the risks of owning mortgage cash flows. A sharp change in rate volatility can make prepayment and extension risk harder to hedge. Heavy MBS supply, weaker investor demand, liquidity strains, or greater balance-sheet constraints can also affect the price investors require. Conversely, strong demand for agency MBS or improved liquidity may support prices and narrow some yield spreads.
The primary market can move differently from the secondary market. Lenders may adjust rates as their capacity, funding conditions, hedging costs, lock volume, operational workload, or competitive position changes. A lender with a large pipeline of locked applications may respond differently from one with spare capacity. Costs can also be passed through at a different time than the related market move.
Guarantees reduce certain investor credit risks but do not remove all mortgage-market risk or all borrower costs. FHFA explains that Fannie Mae and Freddie Mac charge guarantee fees to lenders and that lenders commonly pass those charges through to borrowers in the interest rate or upfront pricing. Loan-level fees can depend on risk features. Treat these charges as part of the broader pricing process, not as a constant number of basis points that can simply be added to the 10-year yield.
Why can your quote differ from a national mortgage-rate average?
A national benchmark is not an offer reserved for every borrower. Credit history, loan-to-value ratio, property type, occupancy, loan size, down payment, loan purpose, points, lender fees, and the lender’s own pricing can change the quote. A borrower paying discount points may receive a lower note rate but incur more upfront cost; a rate with no points may look higher while costing less at closing. Comparing annual percentage rates, points, and fees provides more context than comparing the note rate alone.
The chosen loan type also matters. A 15-year fixed mortgage, a 30-year fixed mortgage, an adjustable-rate mortgage, a jumbo loan, a government-backed loan, and a refinance application can respond differently to market changes. Some have different investors, eligibility rules, guarantees, and cash-flow risks. A statement about a U.S. conforming purchase mortgage should not be generalized to every U.S. loan product or to mortgage markets in other countries.
To compare offers, use the same loan amount, property assumptions, down payment, credit profile, lock period, points, fees, and closing timeline. Ask whether the rate is locked, when the lock expires, and what could change it. A broad rate average can provide context; the lender’s written loan estimate describes the terms relevant to your application.
How should you use Freddie Mac’s PMMS?
Freddie Mac’s Primary Mortgage Market Survey (PMMS) is a widely followed U.S. benchmark, but its methodology and sample matter. Since the 2022 enhancement, the PMMS has used qualifying loan applications submitted to Freddie Mac’s Loan Product Advisor system rather than lender survey responses. Its published averages focus on conventional, conforming, owner-occupied home-purchase loans with a single unit, 15- or 30-year fixed terms, and high-credit, roughly 20%-down borrower characteristics.
That methodology makes the series useful for describing a defined slice of the primary market. It does not mean every application will be approved, a loan will close at that rate, or a particular borrower can obtain the average. The series can also move differently from same-day Treasury or MBS data because the instruments, observation windows, and publication schedules differ. When comparing charts, check the date, the quote basis, points, loan profile, and whether the figures are daily or weekly.
If you are trying to explain a rate move, track a matched set of observations rather than subtracting today’s mortgage average from a Treasury yield observed on another date or under a different convention. An MBS-Treasury comparison can help describe the secondary market, while PMMS or lender quotes speak to the primary market. Neither spread alone identifies the full source of a change. For a related long-rate concept, see how Treasury yields separate expected short rates from a model-estimated term premium.
Common questions
Q1If the 10-year Treasury yield falls, should mortgage rates fall too?
They may face downward pressure, but the change need not be one-for-one. MBS spreads, prepayment risk, lender pricing, and borrower or loan characteristics can change at the same time.
Q2Is the mortgage-Treasury spread a lender’s markup?
No. It is a yield difference between selected measures. It combines differences in cash flows, securities, market conditions, and the selected primary-market quote; it does not isolate a particular lender’s margin.
Q3Does Freddie Mac’s average rate guarantee the rate I can receive?
No. The PMMS is an average for a defined group of applications and does not promise approval, a lock, or a closing rate for an individual borrower. Compare written offers with the same loan assumptions, points, and fees.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
Why can a 30-year fixed mortgage be compared with a 10-year Treasury even though their contractual maturities differ?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide