

Money Market Fund 7-Day Yield: What It Measures and What It Misses
Learn how a money market fund's 7-day yield is annualized, how to convert it into a short-period dollar estimate, and how fund risk differs from bank deposits.
In this guideThe quote annualizes a recent seven-day window
Short summary
A money market fund's 7-day yield is a recent income measure annualized from seven calendar days. It is not the return you will earn over the next week, a promised annual rate, or proof that the fund is a bank deposit. This guide focuses on U.S. money market mutual funds. Product names, fund rules, tax treatment, deposit insurance, and settlement practices vary by country and provider.
The quote annualizes a recent seven-day window
A 7-day yield uses a fund's investment income over the latest seven calendar days and converts that short observation into an annualized rate. Form N-MFP contains standardized gross and net seven-day yield disclosures. The annualization makes the figure easier to compare with other annual rates; it does not mean the fund earned a full year of income in seven days. The SEC explains the reporting convention in its Form N-MFP amendments.
Treat the result as a snapshot of recent portfolio income. Short-term rates, holdings, expenses, and distributions can change. A rate shown today may be different next week, and repeating the same seven-day income for a year is an assumption rather than a forecast. The figure also says little by itself about credit exposure, access to cash, or the chance of a loss.
Convert the annualized number into a short-period estimate
For a simple illustration, suppose a fund displays a 4.20% annualized yield and you hold $10,000 for seven days. Using a 365-day year and assuming the quoted rate stays unchanged, the rough income is $10,000 × 0.042 × 7 ÷ 365, or about $8.05 before taxes. This translates an annualized simple quote back into a seven-day amount; it is not a promised distribution or a prediction of the fund's next statement.
The estimate leaves out rate changes, the fund's actual daily accrual and distribution schedule, your exact purchase and redemption timing, account-level charges, and taxes. If the quoted figure is gross, fund expenses still reduce what reaches shareholders. If it is net, it may already reflect expenses or a temporary waiver. Compare the same type of yield for the same share class and read the fund's current prospectus.
Fund type tells you what may sit in the portfolio
U.S. government money market funds generally invest in cash, government securities, and fully collateralized repurchase agreements under the rule's portfolio test. “Government” does not necessarily mean that every holding is a Treasury bill. Prime funds can hold short-term corporate and bank obligations, including commercial paper and certificates of deposit. Tax-exempt funds focus on short-term municipal securities and have different tax and credit exposures. The SEC's investor bulletin describes these fund categories and their risks.
Those labels are a starting point, not a complete risk ranking. A government fund can still face liquidity or operational issues, while a prime fund's credit exposure depends on the actual issuers and instruments. Check the portfolio schedule, concentration, maturity profile, and the fund's definition of eligible securities. Do not infer “Treasury-only,” same-day liquidity, or a government guarantee from the word “government.”
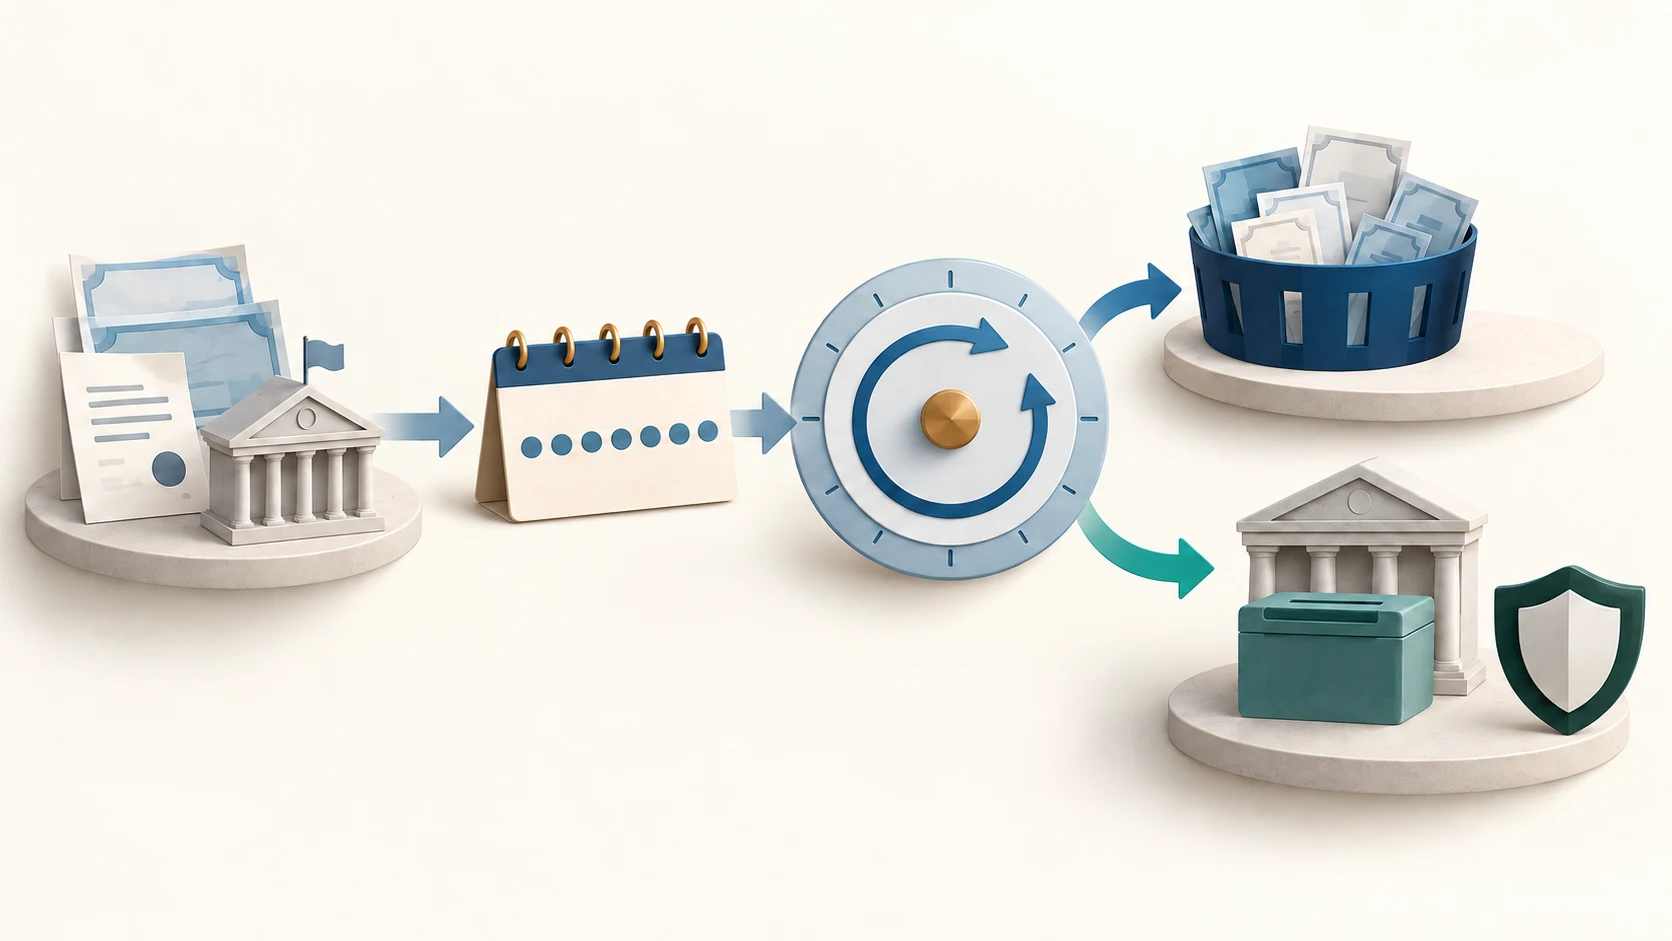
Compare gross yield, net yield, and the share class
Gross yield describes portfolio income before fund expenses; net yield reflects expenses charged to the relevant share class. A waiver can temporarily reduce expenses and raise a displayed net yield. When the waiver expires or changes, the investor's net income can fall even if market rates and the portfolio are otherwise unchanged. A fund may also show different yields for different classes because fees and eligibility differ.
Compare the same date, share class, and yield basis. Look for the expense ratio, waivers, minimum investment, purchase restrictions, and any short-term redemption fee. A headline number from one class cannot be compared fairly with another fund's net yield unless the expense treatment matches. Neither gross nor net seven-day yield is total return: it does not summarize every price movement or guarantee that a share will always be worth one dollar.
A stable target price is not a guarantee of principal
Some U.S. retail and government money market funds seek to maintain a stable net asset value, often $1 per share. Some institutional prime and tax-exempt funds use a floating share price. A stable-price objective is a fund accounting and operating convention, not FDIC insurance or a promise that losses are impossible. If portfolio losses or other pressures become large enough, a stable-price fund can fail to maintain its target, a result often called “breaking the buck.”
Money market fund shares are securities, not insured deposits, and investors can lose money. The SEC notes that funds may also use liquidity fees under applicable rules and fund policies. Its 2023 money market fund reforms changed liquidity requirements and fee frameworks; current documents and notices control for a particular fund. A high yield does not cancel these risks.
A fund, a bank deposit, and a brokerage sweep are different
A money market mutual fund pools investor money and buys short-term securities. A bank money market deposit account is a deposit liability of a bank. A brokerage cash sweep is a program that may place cash in one or more bank deposits, a money market fund, or another arrangement. Similar names do not mean the same legal claim, pricing, or insurance.
The FDIC says mutual fund shares are not insured deposits, even when purchased through a bank. A sweep balance may receive deposit-insurance treatment only when the underlying funds are actually held at an insured bank and applicable ownership and recordkeeping requirements are met. Check the sweep disclosure to see where the cash goes, which institution owes it, what insurance applies, and whether the balance instead buys fund shares. The FDIC's product guide lists investments that are not FDIC-insured.
Access to cash depends on fund and account rules
“Liquid” does not always mean immediately spendable. A fund may accept redemption orders on business days, while the broker or transfer agent applies a cutoff time, settlement process, minimum, or holding period. Bank holidays, transfer networks, and account restrictions can affect when proceeds arrive. Read the prospectus and the account's cash-management terms before relying on a specific date.
Money market fund rules also address stress periods and liquidity. Depending on the fund and circumstances, a liquidity fee can reduce redemption proceeds. The applicable prospectus, current shareholder notice, and account terms matter more than a generic description of how money market funds usually work. Keep near-term spending money in a place whose access rules fit the date you need it; a yield quote alone cannot establish that fit.
Use a like-for-like checklist before comparing quotes
Record the observation date, seven-day yield basis, share class, net expenses, waiver end date, minimum balance, redemption cutoff, settlement timing, and any liquidity fee. Then identify the portfolio type and whether it holds Treasury securities, other government obligations, corporate paper, or municipal debt. For a deposit or sweep, identify the legal institution and the actual asset behind the balance.
Compare dollars over the period you actually expect to hold the cash, and keep the calculation explicitly hypothetical. A 4.20% annualized quote will not produce $420 over a year unless the rate and balance persist under the relevant convention, which is not assured. If maturity timing matters, compare a money market fund with a Treasury bill ladder; for short-term issuer credit, see commercial paper versus Treasury bills. A bank's rate transmission is a separate question covered in deposit beta. These comparisons explain mechanics, not which product is right for a particular person.
Common questions
Q1Is a 7-day yield the amount I will earn in seven days?
No. It is an annualized rate based on recent seven-day fund income. A short-period dollar estimate requires a separate calculation and assumptions about the rate, balance, expenses, timing, and taxes.
Q2Can a money market fund lose money even if it targets $1 per share?
Yes. A stable net asset value is an objective, not a guarantee. Fund shares are not FDIC-insured, and losses or liquidity measures can affect value or redemption proceeds.
Q3Is a brokerage cash sweep the same as a money market fund?
Not necessarily. A sweep may place cash in bank deposits, buy fund shares, or use another program. Read the disclosure to identify the underlying asset, institution, insurance treatment, fees, and access rules.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What does a 7-day yield primarily represent?
Choose an answer to see the explanation