

The Impossible Trinity: Exchange Rates, Capital Mobility, and Monetary Policy
Understand why exchange-rate stability, open capital markets, and independent monetary policy create a trade-off, how the three policy pairings work, and what the framework leaves out.
In this guideWhat does the impossible trinity say?
Short summary
The impossible trinity, or monetary trilemma, describes a constraint among three policy aims: a stable exchange rate, mobile cross-border capital, and monetary policy set for domestic conditions. In the standard framework, an economy cannot fully secure all three at once. Real-world arrangements sit at different points along the trade-off, and the framework is a guide to mechanisms rather than a literal rule that every country must fit into two boxes.
What does the impossible trinity say?
The impossible trinity is a way to organize choices in open-economy macroeconomics. Its three corners are exchange-rate stability, the ability of capital to move across borders, and monetary-policy autonomy. The basic Mundell–Fleming insight is that a country cannot combine a fixed exchange rate, free capital movement, and an independent monetary policy without limit. The Bank for International Settlements describes this as the familiar constraint among those three goals. {source:bisImpossibleTrinityMundellFleming2016}
“Impossible” can sound more absolute than the practical claim. The framework does not say that every currency movement must trigger an immediate crisis, that one policy objective must be abandoned completely, or that all countries face the same constraint at every moment. It says that, under the model’s assumptions, trying to hold a tight exchange-rate commitment while allowing capital to move freely limits the room to set interest rates independently for domestic goals. An economy may soften the constraint by accepting more exchange-rate movement, using measures that affect capital flows, or tolerating less monetary independence.
The “trinity” is not a scorecard that ranks three objectives as equally valuable. Governments may value predictable trade prices, access to international financing, and a policy rate responsive to domestic inflation or output for different reasons. The framework clarifies that these aims can conflict; it does not decide which mix is best, quantify the welfare cost of each choice, or replace country-specific analysis. Its value is diagnostic: it helps explain why a policy mix can become strained when a shock pulls one of the three aims in a different direction.
What are the three policy objectives?
Exchange-rate stability means limiting how much the domestic currency’s value moves against a reference currency or basket. The commitment may be a formal fixed parity, a narrow band, or a less rigid effort to damp fluctuations. These arrangements are not identical. A hard peg promises a narrower path than a managed float, and a stated regime can differ from the way the exchange rate is actually allowed to move. The policy objective is about the desired behavior of the exchange rate, not simply whether it happened to be calm in one week.
Capital mobility is the extent to which residents and nonresidents can acquire, sell, or transfer financial claims across borders. A highly open capital account makes it easier for investors, banks, firms, and households to shift funds in response to returns and perceived risk. “Open” does not mean every transaction is costless or that capital flows instantly. Legal restrictions, settlement systems, taxes, balance-sheet limits, market depth, and changing risk perceptions can all impede or redirect flows. The trilemma abstracts from many of these details to focus on the force that cross-border portfolio choices can exert.
Monetary-policy autonomy is the ability to set monetary conditions in response to domestic objectives, such as inflation and economic activity, rather than having the policy rate largely dictated by the exchange-rate commitment or foreign financial conditions. It does not mean that a central bank is unaffected by the world economy. Even a floating currency can transmit overseas interest rates through trade, borrowing costs, and asset prices. Autonomy is a matter of degree: the question is how much the central bank can move its policy stance without undermining another commitment.
These definitions also keep the three corners distinct. Exchange-rate stability is not the same as a stable price level. Capital mobility is not the same as a large current-account surplus or deficit. Monetary autonomy is not a guarantee that policy will achieve its target. The choices concern a policy regime and its constraints; observed outcomes also depend on institutions, shocks, private balance sheets, and decisions by firms and households. The IMF’s discussion of exchange-rate arrangements treats the exchange-rate regime, monetary framework, foreign-exchange operations, and capital-flow measures as connected parts of a broader policy design. {source:imfChoiceOfExchangeRateArrangement2022}
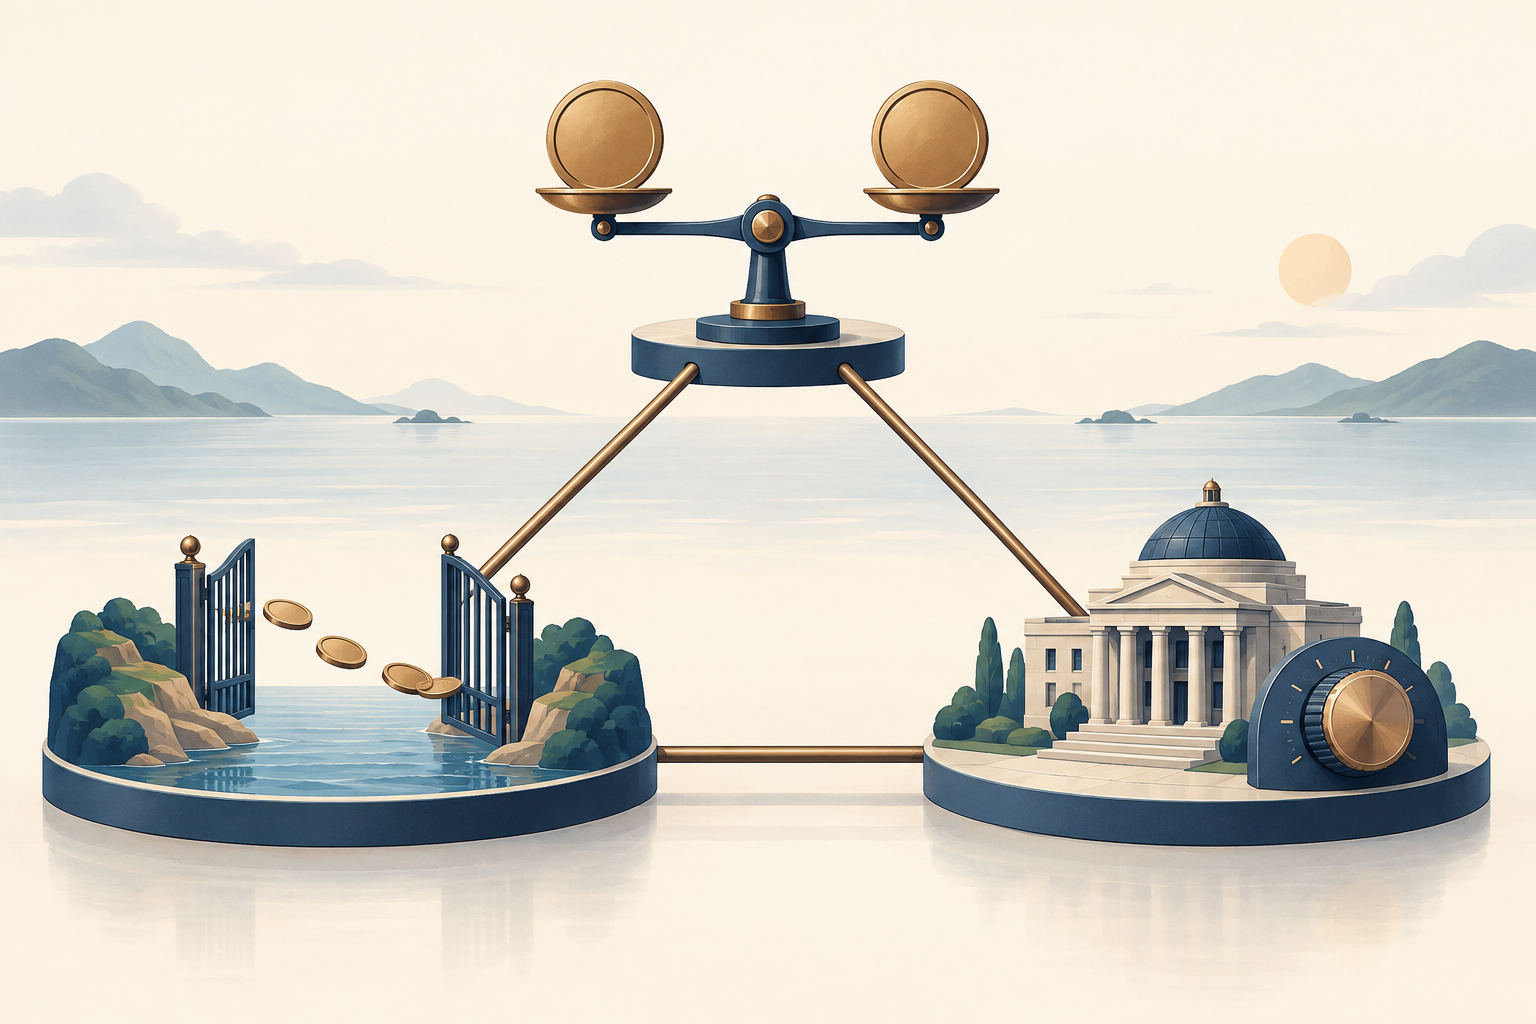
Why can capital flows constrain a central bank under a peg?
Consider an economy that keeps its currency at a credible fixed rate against an anchor currency and permits substantial cross-border investment. If investors can switch between domestic and anchor-currency assets at modest cost, a persistent gap between their expected risk-adjusted returns gives them a reason to move funds. The return comparison is not just the two posted interest rates. It also reflects expected currency changes, default and liquidity risk, taxes, transaction costs, and other frictions. With a credible peg, expected depreciation may be small, but it is not necessarily zero and the risk adjustment need not disappear.
If the domestic central bank cuts its short-term rate far below the return on comparable anchor-currency assets, some holders may prefer to move money abroad. That creates demand for the anchor currency and pressure against the peg. To defend the parity, the monetary authority can sell foreign reserves and buy its own currency. Such a transaction can withdraw domestic liquidity; if it is not offset, short-term market rates may rise, pushing conditions back toward those compatible with the exchange-rate commitment. A central bank may also adjust its policy rate directly. Either way, the peg and capital mobility constrain how far domestic rates can diverge for long.
The direction can reverse. If domestic rates are set sufficiently above comparable foreign returns, capital may flow in and create appreciation pressure. Under a peg, the authority can buy foreign currency and supply domestic currency. Unless the resulting liquidity is managed, domestic monetary conditions may ease. The precise size and timing of a flow depend on risk, expectations, instruments, and market frictions; the simplified mechanism is not a claim that every one-point rate gap causes a fixed amount of capital movement.
This is the core conflict: with open capital movement and a tightly defended exchange rate, a domestic rate decision can invite flows that force the central bank to intervene or bring market rates back toward the level consistent with the peg. The IMF’s operational guidance states that under a fixed exchange-rate arrangement with free capital mobility, monetary autonomy is limited and policy cannot be conducted independently of the exchange-rate commitment. {source:imfOperationalizePeg2026}
<!-- learn:illustration -->
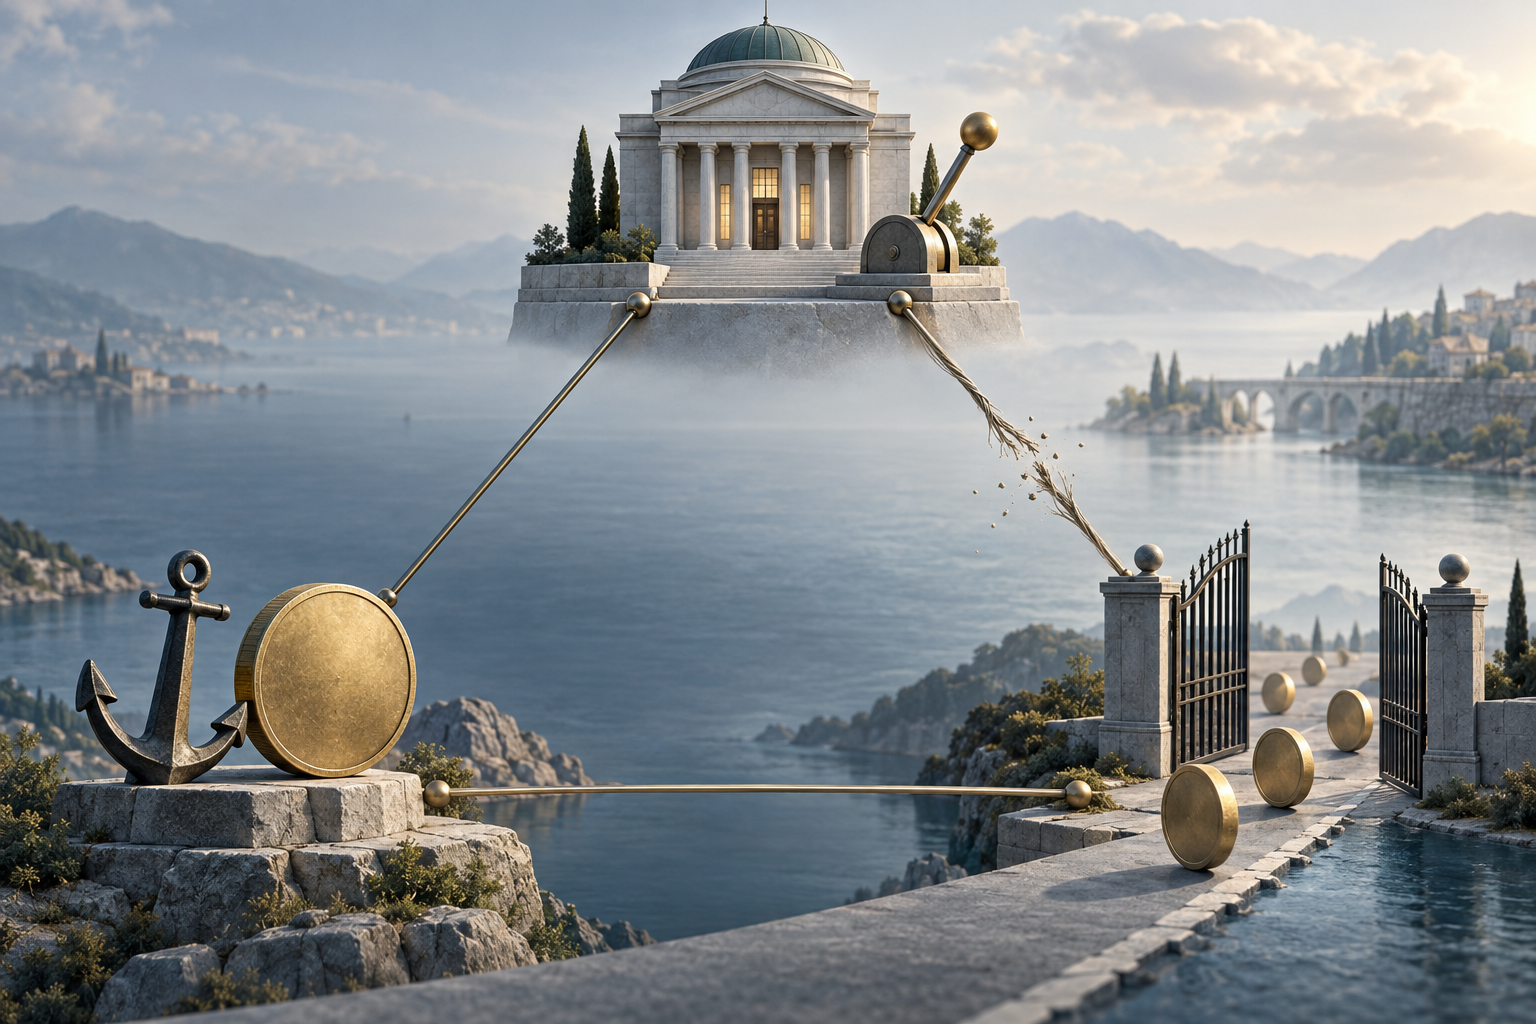
What does each pair of objectives imply?
The three possible pairings show what the framework means in practice. They describe the margin that becomes constrained, not three universal institutional templates.
Exchange-rate stability plus capital mobility: monetary autonomy is the most constrained corner. A credible peg alongside open cross-border finance leaves less room to set interest rates independently. The domestic policy rate may need to move with the anchor’s conditions, or the central bank may need to allow market rates and liquidity to adjust in response to flows. If a domestic downturn calls for a rate cut while defending the peg calls for tighter conditions, the two aims can pull against each other. The IMF’s peg guidance explicitly describes this combination as limiting monetary autonomy. {source:imfOperationalizePeg2026}
Capital mobility plus monetary autonomy: the exchange rate must generally be able to absorb more adjustment. If the central bank changes rates for domestic inflation or activity while funds can move freely, the exchange rate can respond to the resulting shifts in expected returns and portfolio demand. A floating or more flexible rate provides that adjustment margin. This does not mean that the exchange rate is irrelevant to policy: depreciation can raise local-currency import costs, affect foreign-currency borrowers, or influence inflation expectations. It means the central bank is not promising to keep the rate at a fixed parity throughout that adjustment.
Exchange-rate stability plus monetary autonomy: stronger restrictions or frictions on cross-border flows can reduce the immediate pressure on the exchange-rate commitment when domestic rates diverge from anchor rates. In the simplified framework, limiting capital mobility creates room to pursue a domestic interest-rate policy while stabilizing the exchange rate. Actual measures vary in coverage and effectiveness; restrictions can redirect transactions, create avoidance incentives, and impose costs. The pairing is therefore not simply “add controls and obtain full autonomy.” It identifies the channel that would otherwise transmit interest-rate differences into flows.
In real policy regimes, the choices are often intermediate. A currency may be allowed to move within a band; some capital transactions may face restrictions while others remain open; the central bank may react to domestic conditions but also take exchange-rate pressure into account. Those choices give partial degrees of stability, openness, and autonomy. It is more useful to ask how strong each commitment is, and which margin changes when a shock arrives, than to declare that a country has chosen exactly two corners and none of the third.
How would a hypothetical anchor-rate shock test the trade-off?
Imagine a fictional economy, Harbor, that keeps its currency within a very narrow band against an anchor currency. Harbor permits most portfolio flows. These are invented conditions and numbers, used only to make the mechanism concrete. Suppose the anchor central bank unexpectedly raises its policy rate from 3% to 5%. Harbor’s central bank had planned to cut its own rate from 4% to 2% because domestic demand had weakened.
The rate change is not a mechanical prediction of a specific flow. Still, if investors see anchor-currency assets as offering a higher risk-adjusted return and expect the peg to hold, some may switch away from Harbor-currency assets. That portfolio shift can raise demand for the anchor currency. To keep the exchange rate within its narrow band, Harbor’s authority may sell reserve assets for its own currency, let short-term liquidity tighten, or raise its policy rate toward a level more compatible with the peg. Those actions make the domestic easing plan harder to carry out in full.
Harbor has other ways the situation could resolve. It could allow its currency to weaken beyond the band, giving exchange-rate flexibility more weight and preserving more room to set rates for domestic conditions. It could tighten or otherwise alter the rules affecting particular cross-border flows, changing the degree of capital mobility. Or it could continue defending the band and accept that its rate path will be influenced more by the anchor’s rate. Each option changes a different margin; none is costless, and the trilemma by itself does not tell us which response is preferable.
Now change one assumption. Suppose investors think the peg may soon be adjusted. Expected depreciation can offset a higher domestic interest rate, so the relevant return comparison is no longer the policy-rate gap alone. Or suppose the rate increase reflects a rise in perceived credit risk: a higher quoted yield may not attract funds if investors also expect larger losses. These cases explain why the trilemma is a directional framework, not a spreadsheet that converts two policy rates into a guaranteed capital-flow amount.
Can foreign-exchange intervention and reserves remove the constraint?
Intervention can affect the timing and path of adjustment. Selling reserves to buy the domestic currency can meet demand for foreign currency during pressure on a peg. Buying foreign currency can counter appreciation pressure. Reserves can help an authority manage temporary disruptions and signal capacity to transact. They do not create an unlimited supply of foreign currency, nor do they by themselves make a persistent policy inconsistency disappear.
The balance-sheet effect matters. When a central bank sells foreign currency and receives domestic currency, domestic liquidity tends to contract unless the authority offsets that contraction through other operations. When it buys foreign currency and pays in domestic currency, liquidity tends to expand unless it is absorbed. These operations can complicate the pursuit of a separate domestic interest-rate target. A central bank may sterilize an intervention by adjusting domestic assets or liquidity operations, but repeated sterilization does not erase the underlying incentives for investors to move funds if the interest-rate and exchange-rate commitments remain inconsistent.
Intervention therefore can buy time, smooth temporary volatility, or help implement a chosen regime. Whether it can sustain a particular path depends on the credibility of the commitment, the scale and persistence of flows, reserve access, the policy framework, and the balance sheets involved. A reserve figure on its own is not enough to establish that a peg is safe or doomed. Nor does one episode of intervention prove that monetary autonomy has vanished; it is the policy pattern and the adjustment available over time that matter.
Foreign-exchange intervention is only one part of the operating framework. A peg also requires clarity about the parity or band, the currency used as an anchor, how liquidity is supplied or withdrawn, and how the authority responds to shifts in external returns and risk. The IMF’s operational guidance treats interest-rate determination and foreign-exchange and monetary operations as linked questions for a peg, rather than as a reserve-only calculation. {source:imfOperationalizePeg2026}
What does the trilemma leave out?
The classic diagram compresses a complex financial system into three policy objectives. It is most useful when its assumptions are made visible. The cleanest version imagines substantial capital mobility, assets that investors can substitute for one another, and a credible exchange-rate commitment. In real markets, assets differ in default risk, liquidity, tax treatment, legal protection, and currency exposure. Interest-rate differences can persist because investors require compensation for those differences or because transactions face frictions. A rate gap alone therefore does not establish that the country has violated a fixed mathematical equality.
There is also a debated extension. The IMF handbook notes Hélène Rey’s argument that global financial conditions may constrain monetary autonomy even when the exchange rate is flexible, sometimes described as an “impossible duality” rather than a trilemma. That is an extension of the classic result, not a claim that the original peg-and-capital-mobility mechanism disappears or that all economists treat the two frameworks as identical. It is a reason to distinguish room created by exchange-rate flexibility from insulation against every global financial shock. {source:imfChoiceOfExchangeRateArrangement2022}
The framework also simplifies how a peg is defended. A central bank’s available instruments depend on its operating system, banking structure, reserve position, access to foreign-currency funding, and the composition and maturity of private-sector liabilities. A currency mismatch can make exchange-rate movements costly for firms or banks, even when a more flexible rate would otherwise provide a policy margin. The desire to limit that balance-sheet damage can lead policymakers to respond to foreign rates or exchange pressure even under a formally flexible regime. These financial-stability effects are not captured by a three-corner illustration.
The trilemma does not tell us whether a particular exchange-rate arrangement is sustainable, whether capital-flow measures are appropriate, or whether a country should choose a peg or a float. Those judgments depend on the structure of trade and finance, the shocks an economy tends to face, institutions, credibility, available policy tools, and the objectives policymakers are accountable for. The IMF’s exchange-rate-arrangement guidance treats regime selection as a broader design problem involving the monetary framework and other policies; its later operational work discusses additional institutional conditions around maintaining a peg. {source:imfChoiceOfExchangeRateArrangement2022} {source:imfOperationalizePeg2026}
Finally, the trilemma is not a theory of every exchange-rate movement or capital flow. It does not explain current-account accounting, calculate how much a currency move changes consumer prices, or measure a real exchange rate. Use the concept to frame the policy constraint, then consult the relevant evidence for the separate question. Current account vs. trade balance distinguishes cross-border goods, services, income, and transfers. Real effective exchange rates explains a weighted measure of currency competitiveness, while exchange-rate pass-through to inflation follows one route from currency changes to domestic prices.
How should you read a country’s policy mix?
Start by naming the three objectives separately. What exchange-rate path does the authority say it wants, and what path does the currency actually follow? Which cross-border transactions can move freely, and which face meaningful restrictions or costs? How does the central bank describe its domestic objectives, and how does its policy rate respond when domestic conditions and anchor-country conditions point in different directions? A regime label alone may not answer all three questions.
Then look at adjustment when pressure occurs. If foreign rates rise, does the local rate tend to follow, does the exchange rate move, do capital-flow rules change, or does the central bank rely on reserve transactions? Observe what happens to market interest rates and domestic liquidity as well as the announced policy rate. A stated peg can coexist with some market movement inside a band; an announced preference for stability can coexist with exchange-rate flexibility. No single day or intervention settles the classification.
The return comparison needs context too. Compare rates with similar maturities and instruments where possible, then consider expected currency changes, credit and liquidity risk, restrictions, and transaction costs. A low domestic policy rate alongside a higher anchor rate is not, by itself, proof of imminent outflows. It is a reason to ask how investors assess the risks, how elastic flows are, and what adjustment the authorities have committed to make. Conversely, a stable observed exchange rate does not prove that the regime will remain stable under a different shock.
This reading method turns the trilemma into a useful set of questions rather than a label. It helps distinguish a strong peg from a flexible arrangement, broad capital openness from a restricted channel, and formal monetary autonomy from the practical ability to use policy independently. It also keeps separate the diagnosis of a policy constraint from a recommendation about what a country should choose.
Common questions
Q1Does the impossible trinity mean every country can choose exactly two goals?
No. The two-of-three shorthand describes the basic model under simplified assumptions. Countries often combine partial exchange-rate stability, partial capital restrictions, and some monetary-policy autonomy. The useful question is how much of each objective a regime pursues and which margin adjusts under pressure.
Q2Do interest rates have to be identical under a fixed exchange rate?
Not necessarily. Even with a peg, rates can differ because investors account for expected exchange-rate changes, credit and liquidity risks, taxes, market segmentation, and transaction costs. The framework says that open capital flows and a credible peg constrain sustained independent rate setting; it does not reduce every market yield to one identical number.
Q3Can reserves permanently protect a peg while the central bank sets any interest rate it wants?
Reserves and intervention can help manage pressure and affect the timing of adjustment. They do not automatically remove a persistent conflict between a peg, open capital flows, and a domestic rate path. The outcome depends on the commitment, flows, reserve access, institutions, and the way liquidity and interest rates respond.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
In the standard impossible-trinity framework, what is the main constraint when a country combines a credible fixed exchange rate with substantial capital mobility?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guidePut optionA contract that gives its holder the right, but not the obligation, to sell the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide