

Household Debt Service Ratio vs. DTI: What the Fed Measure Means
Compare the Federal Reserve's household debt service ratio with borrower-level debt-to-income (DTI), including the denominator, credit-bureau method, and limits.
In this guideThe Fed's DSR is an aggregate ratio
Short summary
The Federal Reserve's household debt service ratio (DSR) compares estimated required debt payments across U.S. households with aggregate disposable personal income. A borrower's debt-to-income ratio (DTI) compares that person's monthly debt payments with their gross monthly income. The names sound similar, but the two measures have different populations, denominators, and uses.
The Fed's DSR is an aggregate ratio
The household debt service ratio asks how large scheduled household debt payments are relative to disposable personal income across the U.S. economy. In compact form:
Household DSR = aggregate required household debt payments ÷ aggregate disposable personal income
It is a macroeconomic ratio of totals. It is not the average of every borrower's DTI, a median household's budget, or the share of income that a typical family actually paid to lenders. The Federal Reserve publishes a total DSR along with mortgage and consumer components. Each component uses the same aggregate disposable-income denominator, so the component ratios add to the total before rounding. {source:fedHouseholdDebtServiceRatioMethodology}
The word “service” refers to payments due on debt during a period, not the outstanding debt balance itself. A DSR is therefore a payment-flow measure. It can change when scheduled payments change, when aggregate disposable income changes, or when both move. The debt stock and its payment burden are related, but they answer different questions.
What goes into the current DSR
The Federal Reserve's current method estimates required payments on mortgages, consumer loans such as student and automobile loans, and lines of credit. It uses monthly scheduled-payment information reported in credit-bureau records, then scales the sample to estimate obligations across the U.S. population represented by the data. The Consumer Credit Panel is an anonymized sample of adults with a credit record; it is not a census of every person's bills or cash payments. {source:fedHouseholdDebtServiceRatioMethodology} {source:fedHouseholdDebtServiceMethodologyNote}
The current measure includes scheduled payments reported for both delinquent and performing accounts. For credit cards, the reported scheduled payment is the minimum required payment, not every cardholder's full balance or the amount they choose to pay. Joint tradelines can appear on more than one borrower's report, so the method adjusts those records to avoid counting the same obligation twice. Because the source records scheduled obligations, DSR should not be read as a direct total of payments that households successfully made in cash. {source:fedHouseholdDebtServiceMethodologyNote}
The denominator is disposable personal income (DPI) from the U.S. National Income and Product Accounts. BEA defines DPI as personal income less personal current taxes: income available to persons for spending or saving. It is an economy-wide national-accounts measure, not the take-home pay of only the people who have debt in the credit-bureau sample. {source:beaDisposablePersonalIncome} {source:fedHouseholdDebtServiceRatioMethodology}
The mortgage component can include property taxes, homeowners' insurance, and mortgage insurance when the servicer collects them through an escrow account and reports them as part of the scheduled mortgage payment. That is a feature of the current credit-bureau method. It means the current series does not measure exactly the same payment concept as the older estimate, which was designed around principal and interest. {source:fedHouseholdDebtServiceMethodologyNote}
A hypothetical example shows what the percentage means
Suppose that in one quarter, the estimated required payments covered by the measure total $18 billion and U.S. disposable personal income totals $450 billion. The illustrative DSR is:
$18 billion ÷ $450 billion = 0.04 = 4%
This calculation says that covered scheduled debt payments equal 4% of aggregate DPI for that quarter under the stated assumptions. It does not say that each household spends 4% of its own income on debt. One family may have no reported debt, another may have a large mortgage payment, and other households may be between those outcomes. A ratio of aggregate totals preserves the scale of the whole economy; it does not describe the distribution across families.
The components can be read in the same way. If hypothetical mortgage payments were $12 billion and consumer-debt payments were $6 billion, their ratios to the same $450 billion denominator would be about 2.67% and 1.33%. Together they equal 4% before rounding. The figures are invented to explain the arithmetic, not a reported Federal Reserve observation. The published series is quarterly and seasonally adjusted, so use the release's own units and notes when working with actual observations. {source:fedHouseholdDebtServiceRatioMethodology}
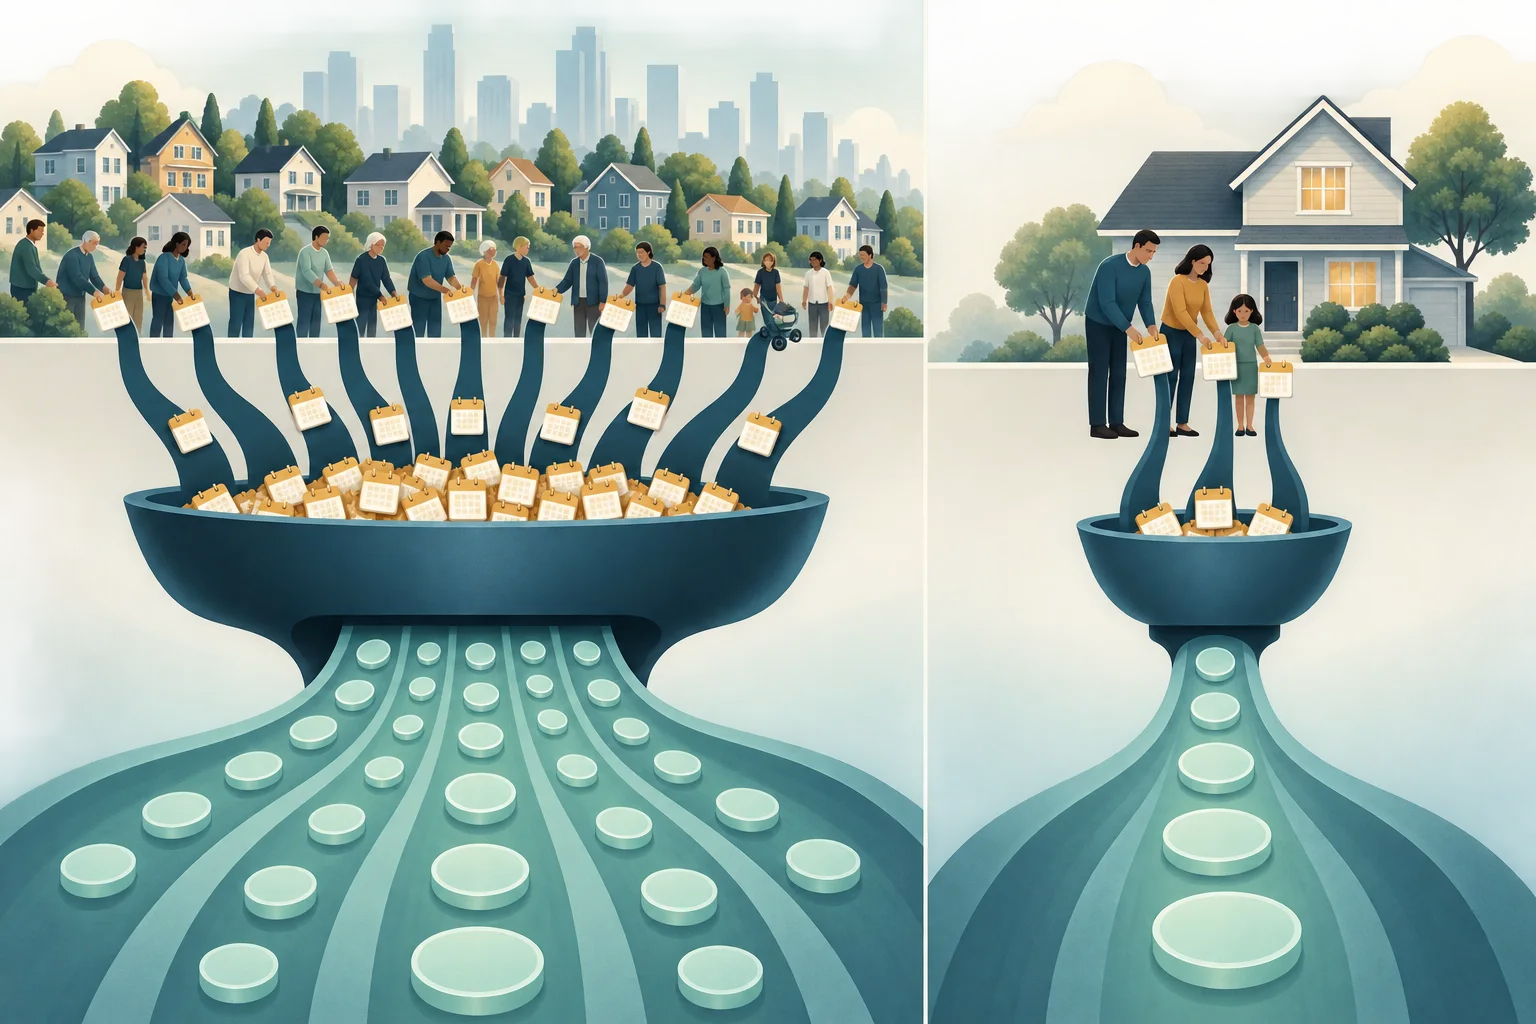
Borrower DTI answers a different question
A debt-to-income ratio is usually calculated for an individual borrower or loan application. CFPB describes it as monthly debt payments divided by gross monthly income. Lenders use it as one way to assess a borrower's ability to manage the proposed payments, and DTI limits can differ by lender and loan product. {source:cfpbDebtToIncomeRatio}
Borrower DTI = that borrower's monthly debt payments ÷ that borrower's gross monthly income
For example, suppose an applicant has $2,000 of monthly debt payments and $6,000 of gross monthly income. The DTI is about 33.3%. The numerator and denominator both refer to that applicant and month. A lender may apply its own rules about which debts and proposed housing costs to include, so the number should be calculated using the lender's instructions for the specific application. The example is a calculation, not a borrowing recommendation or a universal approval threshold.
The Federal Reserve's DSR is different in several ways:
- Its numerator is an estimate of required payments aggregated across the U.S. population represented by the data, rather than the obligations of one applicant.
- Its denominator is aggregate disposable personal income after personal current taxes, rather than one borrower's gross monthly income.
- It is a quarterly macroeconomic statistic, whereas DTI is commonly calculated from monthly figures during loan underwriting.
- It tracks a national payment burden, not a lender's decision about whether a particular borrower qualifies.
An analyst should not compare a 4% aggregate DSR with a 33.3% borrower DTI as if one borrower were being compared with the national average on the same scale. The different scopes and denominators are part of what each measure is designed to capture.
The 2024 method change creates a series break
Starting with its 2024:Q2 release, the Federal Reserve switched to the credit-bureau-based DSR methodology. Under the older method, the Board estimated payments from outstanding balances, average interest rates, and assumed times to maturity across several data sources. The current method uses scheduled-payment records from the credit-bureau sample. It also includes certain mortgage escrow items when they are bundled into a reported payment. {source:fedHouseholdDebtServiceRatioMethodology} {source:fedHouseholdDebtServiceMethodologyNote}
The current-method series begins in 2005, when the credit-bureau data cover the needed tradeline types. The previous-method series runs from 1980 through 2024 and remains available as an archive, but it is no longer updated. The two series can tell similar broad stories while differing in level or movement because they estimate payments in different ways and cover slightly different payment concepts. Their overlap is useful for understanding the transition; it is not a warrant to join them into one seamless series. {source:fedHouseholdDebtServiceRatioMethodology} {source:fedFinancialObligationsRatioDiscontinuation}
When charting a long history, label which method each observation uses. For a comparison that crosses 2024:Q2, consider showing the transition explicitly or keeping the methods in separate lines. If a chart begins in 1980 and then quietly switches to the new method in 2005 or 2024, the apparent change may partly reflect measurement rather than household behavior. Check the date, units, seasonal-adjustment convention, and methodology note attached to the downloaded vintage.
DSR is narrower than every household obligation
The DSR covers specified debt payments; it is not a full household budget. Regular costs such as rent, utilities, groceries, childcare, and medical expenses are not all debt-service payments in the DSR numerator. Some mortgage-related taxes or insurance may be included when escrowed with the reported mortgage payment, but that does not turn the series into a complete measure of housing or living costs. {source:fedHouseholdDebtServiceMethodologyNote}
Readers may encounter the Federal Reserve's Financial Obligations Ratio (FOR), a separate, broader series that historically adjusted DSR for additional recurring obligations. The Fed stopped publishing the FOR after 2023:Q3 because it did not have high-quality data for homeowners' insurance and property-tax payments. The historical FOR can provide context, but it is not a currently updated substitute for DSR. {source:fedFinancialObligationsRatioDiscontinuation}
This distinction also explains why a lower DSR does not automatically mean that every household has more money for discretionary spending. The aggregate numerator and DPI denominator omit many differences in rent, savings, taxes not included in DPI's personal-current-tax definition, and other household expenses. They also do not identify which households carry the obligations.
What a DSR move can and cannot tell you
A rising DSR means estimated required debt payments have increased relative to aggregate DPI. The ratio can rise because scheduled payments increase, because aggregate disposable income falls, or because both happen. A falling ratio can reflect lower required payments, stronger aggregate income, or both. To explain a movement, inspect the mortgage and consumer components and compare their numerator and denominator rather than assigning the change to interest rates alone.
The ratio is useful for describing a broad payment burden and how it changes over time. It does not reveal the median household's DTI, the share of borrowers who are delinquent, who is close to default, whether a new loan is affordable for a particular person, or whether households feel financially secure. Those questions need borrower-level distributions, delinquency or balance data, and information about expenses and assets. The method includes scheduled payments on delinquent as well as performing accounts, so it should not be treated as a measure of successful repayment. {source:fedHouseholdDebtServiceMethodologyNote}
The relationship between debt and the economy can run in both directions. More borrowing can increase future scheduled payments; income growth can make a given payment flow smaller relative to DPI; and changes in loan terms or the composition of borrowing can alter payments without a matching change in total debt. These are possible channels, not explanations that can be inferred from the DSR alone. Use the ratio to describe the payment-to-income relationship, then consult additional data before making a causal claim.
Interest-rate changes can also reach scheduled payments at different times. A fixed-rate loan may keep the same required payment until it is refinanced or its contract changes; a new loan or a variable-rate reset may affect payments sooner. A policy-rate move therefore does not tell you by itself which DSR component will change or when. Compare the mortgage and consumer series with loan-rate, credit, and income data before attributing a movement to monetary policy.
How to read a published DSR observation
Start with the release date and quarter. The Federal Reserve's DSR page provides the current series, its mortgage and consumer components, and a methodology description. Confirm that the observation uses the credit-bureau method and note whether a chart also includes the archived older series. If the article or chart cites one value, preserve its vintage because statistical estimates can be revised. {source:fedHouseholdDebtServiceRatioMethodology}
Next, ask what question you are trying to answer. For the national scheduled-payment burden, DSR is relevant. For an applicant's debt load relative to earnings, calculate that borrower's DTI using the lender's definitions. For the level of outstanding household borrowing relative to the economy, use a debt-stock measure such as debt to GDP. The BEA's definition cited above explains the income denominator behind DSR.
The names are close, but the interpretation is not interchangeable: DSR describes aggregate required payments relative to aggregate after-tax personal income; DTI describes an individual borrower's monthly debt payments relative to gross income. State the population, denominator, period, and method whenever you report either figure.
Common questions
Q1Does a low DSR mean a typical household has little debt pressure?
Not by itself. DSR is a ratio of national totals, so it does not show how payments are distributed across households. Some families can face heavy burdens even when the aggregate ratio is low.
Q2Is the current Federal Reserve DSR directly comparable with the older series?
Use caution. The current method uses reported scheduled payments in credit-bureau records and begins in 2005; the old method estimated payments from balances, interest rates, and maturities and is now archived. Mark the methodology change when comparing across it.
Q3Does the DSR include rent and all household bills?
No. Its numerator covers specified debt payments. The broader Financial Obligations Ratio was a separate historical series and is no longer updated; ordinary living costs are not all part of DSR.
Q4Can I use the Fed's DSR to calculate my mortgage eligibility?
No. A lender evaluates an applicant using its own underwriting rules and borrower-level information. DSR is a national macroeconomic statistic; it is not a personal affordability test or loan-approval threshold.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What is the denominator in the Federal Reserve's household DSR?
Choose an answer to see the explanation
Options glossary
The process that requires an option writer to fulfill the contract after an exercise notice is allocated; it can create or remove an underlying position.
Read the deeper guideBid-ask spreadThe gap between the best displayed bid and ask, which is a practical trading cost and a signal of how uncertain an immediate fill may be.
Read the deeper guide