

Gross Output vs. GDP: What Counts Intermediate Production?
Learn why BEA gross output includes sales between industries while GDP avoids counting intermediate inputs twice, how value added connects them, and which measure fits your question.
In this guideWhat do gross output and GDP measure?
Short summary
Gross output follows the value of production as it moves through industries, including sales from one business to another. GDP avoids counting the same intermediate goods and services again at every stage: it measures final output, equivalently the sum of value added across industries. The measures answer different questions. A larger gross-output total is not a larger economy by another definition; it includes business-to-business transactions that GDP deliberately excludes from its final total.
What do gross output and GDP measure?
The U.S. Bureau of Economic Analysis (BEA) describes gross output by industry principally as a measure of an industry's sales or receipts. It includes goods and services sold to final users and goods and services sold to other industries as intermediate inputs. Those business-to-business purchases are part of the production chain even though they are not counted as final output in GDP. BEA's [gross-output overview]({source:beaGrossOutputByIndustry}) and [gross-output FAQ]({source:beaGrossOutputVsGdpFaq}) explain this distinction.
GDP measures final goods and services produced within the economy during a period. In BEA's industry accounts, GDP by industry is also called value added by industry. The value added of all industries sums to GDP. This approach avoids adding the value of a component once when it is sold to another producer and again when that producer sells the finished product. BEA's [industry-account guide]({source:beaGdpIndustryAccountsGuide}) sets out how gross output, intermediate inputs, and value added fit together.
The phrase “gross output” can sound like a count of everything an economy produces, but the useful distinction is about the accounting stage. Gross output records production at industry stages; GDP records final production after subtracting intermediate inputs. Neither label by itself tells you whether an industry is profitable, whether households are better off, or whether its output is growing in real terms.
Why does gross output include sales between businesses?
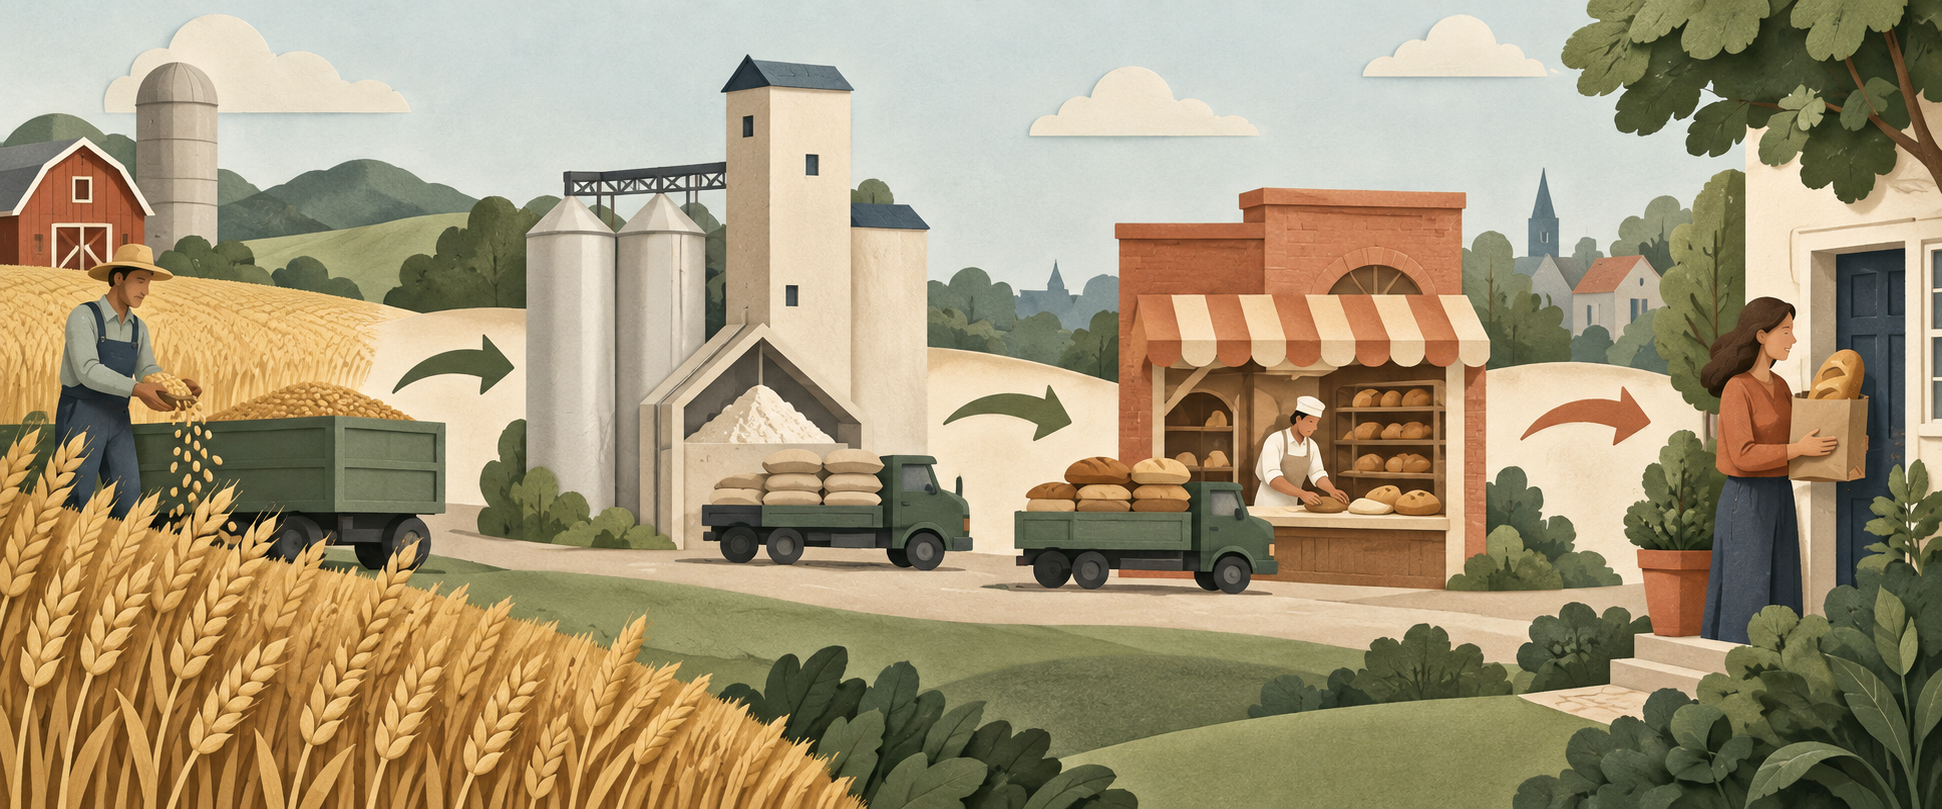
Production commonly happens in stages. A farm sells grain to a mill, the mill sells flour to a bakery, and the bakery sells bread to a household. Each sale is meaningful to the producer and to its suppliers. Gross output can show the value of production at each industry stage, including those intermediate sales. BEA describes the measure as covering both sales to final users and sales to other industries in its [overview of gross output by industry]({source:beaGrossOutputByIndustry}).
GDP asks a different question: what final goods and services were produced for use, investment, government, or export during the period? The value of grain and flour used to produce bread is embedded in the final bread sale. If GDP added the grain sale, the flour sale, and the full bread sale, it would count some of the same production more than once. GDP can instead be calculated as final expenditures or as the sum of value added at each domestic production stage.
This is not a claim that intermediate sales are unimportant or that GDP “misses” them. The value added created by the farm, mill, and bakery appears in GDP. The intermediate transactions help explain how that final production depended on suppliers; they are simply not added on top of the final output as if each sale were a separate final product.
How do gross output, intermediate inputs, and value added fit together?
For an industry, BEA's central relationship is:
Value added = gross output − intermediate inputs
Intermediate inputs are goods and services an industry uses up to produce its output. BEA includes energy, materials, semifinished goods, and purchased services, which can come from U.S. industries or from abroad. For the economy as a whole, value added across industries equals GDP. The [BEA industry-account guide]({source:beaGdpIndustryAccountsGuide}) describes the components and distinguishes intermediate inputs from labor and capital returns.
Value added is not simply a firm's accounting profit. In the BEA industry accounts, it is distributed across compensation of employees, taxes on production and imports less subsidies, and gross operating surplus. The value-added concept captures the income and production costs generated at that stage, after intermediate purchases are removed. The [BEA industry learning center]({source:beaIndustriesLearningCenter}) explains the distinction with its own producer examples.
There are also measurement conventions to keep in view. Gross output is principally sales or receipts for most industries, but in margin industries such as wholesale and retail trade, BEA generally measures output as sales revenue less the cost of goods sold. That treatment focuses on the trade service rather than counting the full resale price of merchandise as new retail output. For any industry comparison, check the BEA series definition and its valuation basis.
A hypothetical supply-chain calculation
Consider an invented domestic supply chain with three stages. A farm sells grain for $100, a mill turns it into flour and sells the flour for $160, and a bakery uses the flour to sell bread to final customers for $300. Assume, only to keep the arithmetic simple, that there are no other intermediate inputs, imports, taxes, inventory changes, or price differences in the example.
| Hypothetical stage | Gross output | Intermediate input used | Value added |
|---|---|---|---|
| Farm | $100 | $0 | $100 |
| Mill | $160 | $100 | $60 |
| Bakery | $300 | $160 | $140 |
| Total across industries | $560 | $260 | $300 |
Summing gross output across the three industries gives $100 + $160 + $300 = $560. That total includes the grain and flour sales again as they move through the chain. Summing value added gives $100 + $60 + $140 = $300, the value of the final bread sale in this simplified example. GDP is $300, not because the earlier sales did not happen, but because their value is already embodied in the final product.
The numbers are entirely hypothetical teaching inputs. They are not BEA observations, an estimate of food production, or a forecast. Real production accounts cover many industries, imported and domestic inputs, inventories, taxes, margins, and changing prices; their published estimates use detailed source data and methods rather than this three-step classroom calculation.
What does gross output add to supply-chain analysis?
Gross output can help show how much business activity occurs at each stage of production and how industries buy from one another. It is useful when a question concerns supplier relationships, intermediate-input dependence, or changes in the composition of production. BEA's industry tables distinguish gross output from value added and provide detail on intermediate-input categories such as energy, materials, and purchased services in the [guide to its industry accounts]({source:beaGdpIndustryAccountsGuide}).
For example, two industries could contribute the same amount of value added to GDP while having very different amounts of intermediate purchases. One may rely heavily on energy, materials, and specialist services; another may generate more of its output from labor and capital within the industry. Gross output and input details can make those production structures more visible. They can also support analysis of how supply disruptions or final-demand changes might pass across linked industries, subject to the model and data used.
Gross output alone does not identify the cause of a change. A higher current-dollar value can reflect higher prices, more production, a shift in product mix, inventory changes, or other components of the industry measure. Nor does a large gross-output number mean that an industry created the same amount of new domestic value. For that question, inspect value added and its components alongside gross output.
<!-- learn:illustration -->
How should you compare current-dollar and real measures?
Current-dollar gross output values production using prices in the period being measured. It can change because quantities, prices, or both change. A real gross-output measure uses price indexes to separate changes in production volume from price changes. BEA publishes chain-type quantity indexes for gross output by industry and explains their construction in the [industry-account guide]({source:beaGdpIndustryAccountsGuide}).
Match the concept before comparing growth. A nominal gross-output level should not be compared directly with real GDP, and a gross-output growth rate should not be described as GDP growth. For real measures, match the industry coverage, period, seasonal treatment, and release vintage. BEA's chain-type dollar levels are generally not additive across detailed components away from their reference year; use published indexes or contribution measures when the question is about real growth rather than adding chained-dollar pieces yourself.
The distinction from final sales also matters. Gross output includes production sold to other businesses, while final-sales measures focus on output purchased by final users. Inventory investment can affect GDP when goods are produced but not yet sold. That separate stock-flow question should not be confused with the intermediate-input subtraction that connects gross output to value added.
What can gross output not tell you by itself?
Gross output is not an alternative GDP total that can be read as a larger measure of final production. Summing output across industries counts some intermediate goods and services at multiple production stages. BEA explicitly notes that this aggregation reflects double counting and exceeds GDP in its [guide to the GDP-by-industry tables]({source:beaGdpIndustryAccountsGuide}). The repeated counts are intentional for studying supply chains; they are not an error in the accounts.
The total does not tell you how much value each industry added, how much went to wages, taxes, or operating surplus, or how much final output households consumed. It is not a direct measure of productivity, jobs, profitability, or living standards. Gross output may include imported intermediate inputs in an industry's production process, so it does not mean that every dollar in the measure is newly created domestic value. BEA's [definition of intermediate inputs]({source:beaIntermediateInputsFaq}) includes goods and services sourced domestically and from abroad.
Avoid turning the ratio between gross output and GDP into a fixed multiplier or a claim about “hidden” activity. The ratio changes with industry composition, supply-chain depth, outsourcing, prices, and measurement boundaries. State which output measure you are using and why before interpreting a trend.
Which measure should you use for your question?
Use GDP or value added when you want to describe final domestic production, compare the economy's output over time, or measure an industry's contribution to GDP. Use gross output when you want to examine production at successive industry stages, sales to other businesses, or how intermediate inputs connect suppliers to final producers. These are complementary views of production, not competing answers to the same question.
Before quoting a number, identify whether it is industry-level or economy-wide, current-dollar or real, and whether it counts gross output, intermediate inputs, value added, or final sales. Check whether a retail or wholesale industry's output is measured using a margin convention. Keep the period and data vintage aligned when comparing revisions or growth rates.
For context on price adjustment, see nominal versus real GDP. For the difference between household, business, government, and export demand within GDP, see inventory investment versus final sales. For domestic production versus income accruing to residents, see GDP, GNI, and GNP. Each guide addresses a different accounting question.
Common questions
Q1Does GDP leave intermediate production out of the economy?
No. The value added at each domestic production stage is included in GDP. GDP avoids adding the full intermediate sale on top of the final product because that value is already reflected in the later-stage output.
Q2Is gross output just a company's total sales?
It is principally an industry-level measure of sales or receipts, but BEA's accounting conventions matter. For margin industries such as retail and wholesale trade, output is generally measured as sales revenue less the cost of goods sold. Check the definition for the industry and series you are using.
Q3Does a higher gross-output total mean the economy is producing more final value?
Not necessarily. A change can reflect prices, intermediate transactions, industry mix, or inventory changes. To assess final domestic production, examine real GDP or value added alongside gross output and match the data period and price basis. ---
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
Why can the sum of gross output across industries exceed GDP?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide