

FX Settlement Risk: What Payment-versus-Payment Actually Protects
Understand FX principal risk, the cancellation-to-receipt exposure window, and how PvP differs from netting, hedging and a guarantee of timely payment.
In this guideA fixed exchange rate does not complete a currency exchange
Short summary
In a deliverable FX trade, principal settlement risk arises when a party pays the currency it sold but may not receive the currency it bought. The exposure window starts when that outgoing payment can no longer be cancelled unilaterally with certainty and ends when the purchased currency is received with finality. Payment-versus-payment (PvP) links the two final transfers, but does not guarantee timely settlement or remove every other financial risk.
A fixed exchange rate does not complete a currency exchange
Suppose a business agrees to buy EUR 1 million for USD 1.10 per euro on a specified value date. It has agreed to pay USD 1.1 million and receive EUR 1 million. The price is fixed, but the parties still need to deliver the currencies. A trade confirmation records the agreement; it is not evidence that both payments are final.
The BIS settlement-risk analysis distinguishes settlement arrangements for deliverable FX. The relevant question is whether the outgoing payment can become final independently of the incoming one. Sending both payment messages together does not necessarily answer it: the messages may enter different payment systems with different operating hours and legal rules.
A deliverable FX forward can fix the exchange rate while leaving currency-payment obligations at maturity. The FX forward-points guide explains the price of that future exchange. Settlement risk asks whether the currencies actually arrive under the agreed arrangements. These are different stages of the same transaction.
Principal risk is different from replacing a failed trade
All numbers here are hypothetical, exclude fees and interest, and assume one unnetted trade. If the business has irrevocably paid USD 1.1 million but receives no euros, its payment of principal is exposed. The exposure is not merely the spread or a small exchange-rate change. A later insolvency recovery could reduce the eventual loss, so the exposed amount is not an estimate of the final loss.
Now change the facts: the counterparty fails before either currency has been paid, and the business can cancel its outgoing instruction with certainty. The business still needs EUR 1 million. If replacement euros cost USD 1.12 each, a new purchase requires 1,000,000 × 1.12 = USD 1,120,000. Compared with the original USD 1,100,000 price, that is USD 20,000 more. This is a simplified replacement-cost example, not a USD 1.1 million principal loss.
The two scenarios are alternatives, not two losses to add automatically. The BCBS foreign-exchange risk guidance separates principal, replacement-cost and liquidity risks. Even without principal loss, the business may need euros before a replacement trade can settle. Raising euros urgently creates a funding problem whose cost depends on available credit, timing and market conditions.
The exposure window starts before a debit may appear
For non-PvP settlement, identify the last point when the outgoing payment can be cancelled unilaterally with certainty. The principal-risk window begins when that ability ends and runs until the purchased currency is received with finality. The BCBS guidance also emphasizes reconciliation: an institution should not assume receipt merely because the expected arrival time has passed.
Consider a hypothetical operational timeline using one common time zone. A cancellation guarantee ends at 09:00, the account is debited at 10:00, the incoming currency becomes final at 15:00, and reconciliation confirms it at 15:30. The economic principal-risk interval is six hours, from 09:00 to 15:00. Starting the clock at the visible debit would miss the first hour. For operational exposure monitoring, the institution also needs to address the uncertainty until reconciliation at 15:30.
These times are illustrative, not CLS deadlines or universal bank cutoffs. A value date alone does not specify this window. Payment-system hours, holidays in either currency, correspondent-bank arrangements and cancellation rules can change it. An unmatched expected receipt calls for reconciliation and escalation; it is not proof that the money is permanently lost.
PvP makes the final transfers conditional on each other
PvP means that the final transfer of one currency occurs if and only if the final transfer of the other occurs. This condition is stronger than a promise that both parties will pay or a dashboard showing two submitted instructions. The defining feature is the linkage of settlement finality, not identical timestamps on two screens.
In the EUR/USD example, a covered PvP arrangement prevents one currency's final settlement from proceeding independently of the reciprocal final settlement. If the conditions for settlement are not met, the intended exchange may fail to complete. The business may retain protection against the one-sided principal transfer while still lacking the euros needed to pay its supplier.
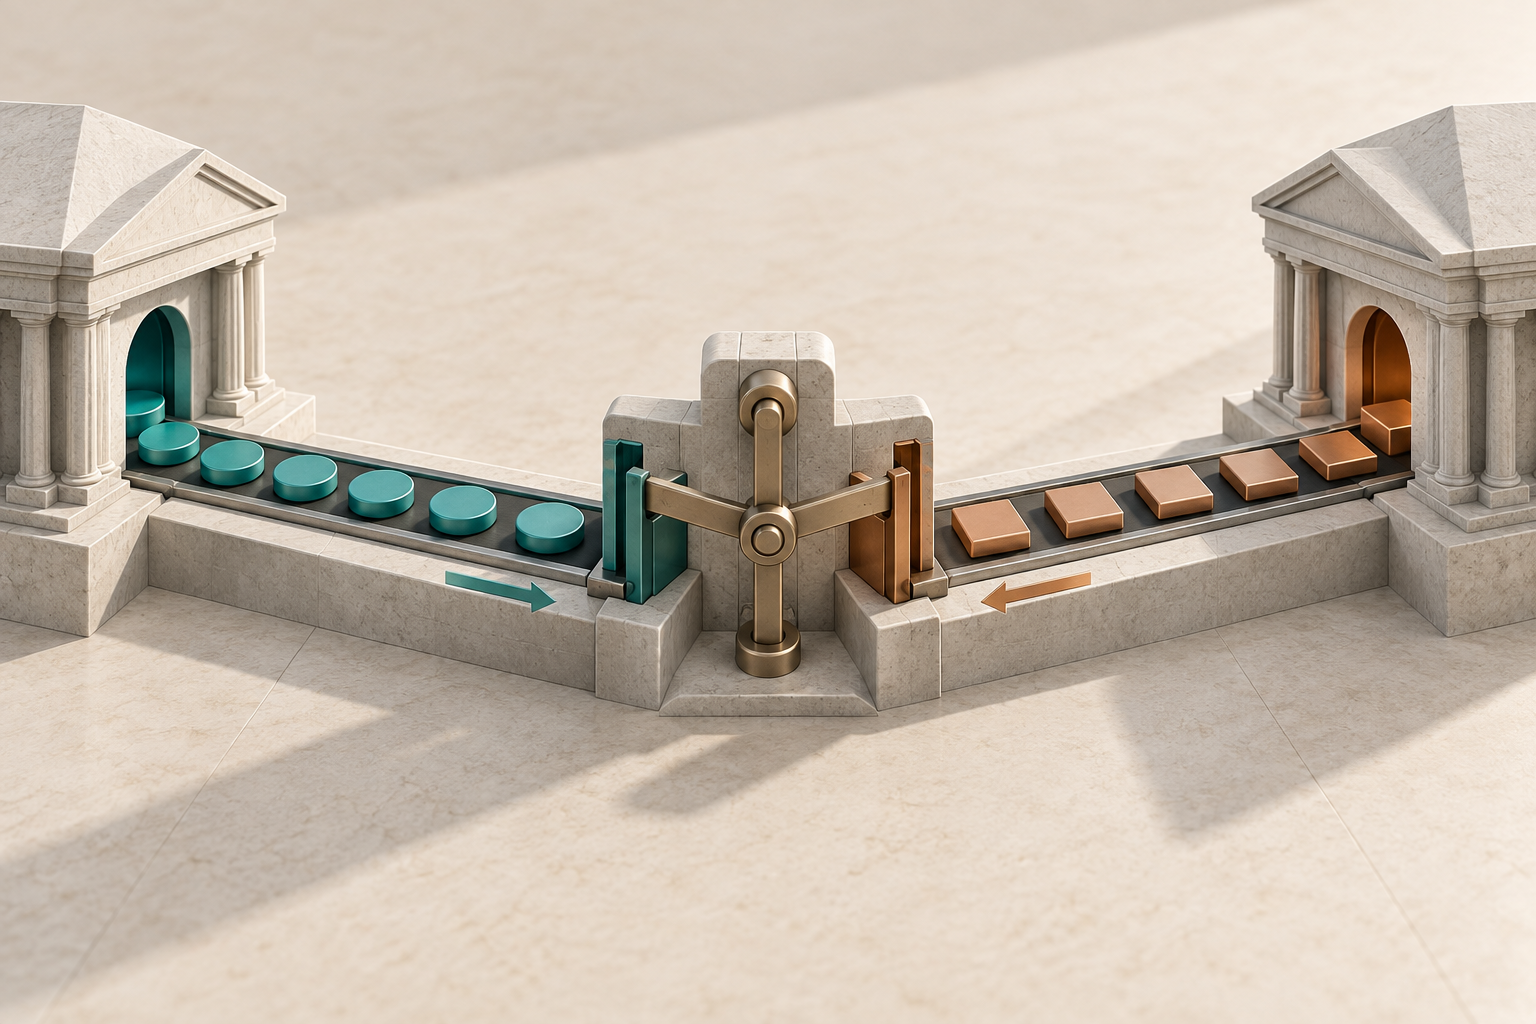
The CPMI report on PvP adoption discusses both the benefit and the obstacles to wider use. A conceptual illustration of linked gates helps explain conditional exchange; it is not a diagram of a particular system's funding accounts, default procedures or payment schedule. Prefunding and claims on a service provider need to be examined separately from the protection on the actual FX settlement instructions.
PvP is also distinct from central clearing. A central counterparty interposes itself between trading parties and assumes obligations under its rules; PvP describes how the currency transfers are linked. An arrangement may combine functions, but the PvP label alone does not mean a CCP has guaranteed the trade.
Netting reduces amounts; PvP links currencies
Netting and PvP answer different questions. Suppose two eligible, enforceable obligations in the same currency, with the same counterparty and settlement date, require A to pay USD 1.1 million and B to pay A USD 0.9 million. If the applicable agreement permits obligation netting, the remaining obligation is 1.1 million − 0.9 million = USD 0.2 million from A to B.
The USD 0.2 million is a remaining payment, not a profit or a saving in trading losses. It also does not establish that a euro payment is conditional on that dollar payment. Netting can reduce the principal that needs to move; PvP provides the cross-currency settlement linkage. Do not subtract dollars from euros as if the units were interchangeable.
Nor should an internal spreadsheet be confused with legal netting. A net funding requirement can coexist with gross underlying settlement instructions. Close-out netting after a default, obligation netting before payment, and operational funding calculations serve different purposes. Their effectiveness depends on the agreements and applicable law, not just the displayed net balance.
CLS is a service with eligibility and access conditions
CLS describes CLSSettlement as a PvP service with multilateral netting. Its public description, checked on September 26, 2026, identifies 18 eligible currencies. That count describes the service's stated scope on the review date; it does not mean every transaction in those currencies automatically uses it.
Participants need an eligible, correctly instructed settlement path. A business using a service through a bank should distinguish the bank's participation from the treatment of its specific transaction. Ask which instructions are included, how settlement status is reported, what funding obligations remain, and what happens to an instruction that cannot settle through the intended path.
A service provider's description of principal-risk protection is not a deposit guarantee, a guarantee against all provider failures or proof that a retail broker balance is covered. This article concerns deliverable currency payments. An NDF, a cash-settled CFD and a listed futures contract have different payment and clearing arrangements; the futures-versus-forex guide provides context without treating those arrangements as identical.
What remains when principal risk is addressed?
A linked settlement mechanism does not fix the exchange rate after a trade fails. Replacement currency can cost more. A missing expected receipt can require temporary funding. Incorrect instructions, system outages and disputed legal terms can still disrupt operations. Reducing one risk is useful precisely because it lets the remaining risks be identified more clearly.
Imagine the supplier requires the euros at noon, but the FX exchange cannot complete until later. Even if neither principal is lost, the business can miss its commercial deadline. It needs a plan for access to the correct currency, not merely an assurance that final transfers are linked. Funding in dollars does not automatically provide euros at the required location and time.
Conversely, ordinary exchange-rate movement is not itself a settlement failure. If both contractual payments arrive finally as agreed, the FX trade can settle successfully even when a subsequent market rate looks unfavorable. Price risk, settlement performance and business-payment timing should be recorded separately.
What evidence should a treasury team request?
Start with the particular transaction: currencies, amounts, legal counterparty, value date and payment destination. Then identify the outgoing cancellation deadline, the expected incoming finality, and the confirmation used to establish receipt. Record the time zone for every cutoff. A bank's general marketing statement is less useful than the settlement path assigned to that trade.
If PvP is intended, confirm eligibility, instruction matching, funding deadlines and exception handling. If netting is intended, establish which obligations are covered and whether the arrangement changes legal obligations or only funding amounts. Keep procedures for failed receipts, replacement purchases and temporary currency funding. These are questions for understanding a service, not a universal legal checklist.
The aim is a precise statement: which principal transfers are linked, when the business can use the purchased currency, and which exposures remain outside that linkage. A competitive FX quote, an agreed forward rate or a small net funding figure cannot answer those questions by itself.
Common questions
Q1Does a forward contract remove FX settlement risk?
It can fix the contracted exchange rate, but a deliverable forward still requires currency payments. Settlement arrangements determine how the principal transfers are protected.
Q2Does PvP mean there is no remaining risk?
No. It addresses principal risk on covered settlement instructions. Delayed settlement, replacement costs, funding needs and operational or legal problems remain separate questions.
Q3Does a CLS-member bank settle all my trades through CLS?
Membership alone does not establish the path of your transaction. Eligibility, instructions, service terms and the bank's arrangements determine whether that trade uses the service.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
When does the non-PvP principal-risk window begin?
Choose an answer to see the explanation