

Market-Cap-Weighted vs. Equal-Weight ETFs: What Changes?
Compare how market-cap and equal-weight ETFs allocate to the same stocks, rebalance, and create different concentration, turnover, cost, and return exposures.
In this guideWhat does weighting change?
Short summary
Two ETFs can hold the same companies and still behave differently if one weights them by market size and the other gives each one an equal starting share. Market-cap weighting gives larger companies more influence. Equal weighting gives each constituent the same target weight at a specified rebalance, then lets the weights drift as prices move. This guide explains U.S. equity index methods using a four-stock hypothetical. It compares exposure, rebalancing, concentration, costs, and return drivers; it does not claim that equal weight is always safer or more profitable.
What does weighting change?
An index is a set of rules for selecting securities and measuring their combined performance. Its weighting method determines how much each constituent contributes to the index return. An ETF that tracks the index generally tries to hold securities in proportions that reflect those rules, though fees, cash, sampling, trading, and timing can create differences.
The same group of stocks can produce different benchmark weights. A market-cap-weighted index assigns a larger share to companies with larger eligible market values. An equal-weighted index assigns the same target share to each company at its rebalance reference point, whatever the companies’ sizes.
Weighting is separate from the fund wrapper. An ETF can be market-cap weighted, equal weighted, or use another method. A mutual fund can also follow either weighting approach. First compare the index universe and rules, then compare the fund that tracks them.
How does market-cap weighting work?
In a simple market-cap-weighted index, a company’s weight is its market value divided by the total market value of all index constituents. Many U.S. equity indexes use float-adjusted market capitalization: the calculation excludes some closely held shares that are not generally available for public trading. The exact float and share-count rules depend on the index provider’s methodology. S&P DJI’s index mathematics methodology describes how index weights and calculations are applied.
If one company’s eligible market value is 10% of the index total, a roughly 10% portfolio weight gives it about one-tenth of the portfolio’s exposure before costs and implementation differences. A larger eligible market value means a larger weight, so a price move in the biggest constituents has more influence on the index result.
The S&P 500 is one example of a float-adjusted market-cap-weighted index. It is not a promise to keep each constituent at a fixed dollar amount: weights move as market values change, and index rules can also adjust for additions, deletions, share counts, and corporate events. Read the provider’s U.S. index methodology for the exact scope and calculation rules.
How does equal weighting work?
For an equal-weighted index with N constituents, the target weight at the rebalance is 1 ÷ N for each constituent. With 500 companies, that is approximately 0.20% per company at the reset. With four hypothetical companies, it is 25% apiece.
The target is a point-in-time rule, not a promise that weights stay equal every day. Prices keep moving after the rebalance, so a stock that rises faster becomes a larger share of the portfolio until the next reset. Index providers choose different rebalance dates, reference prices, buffers, and corporate-action procedures; the rules for one equal-weight index do not apply to all of them.
For a concrete U.S. example, the S&P 500 Equal Weight Index uses the same constituents as the S&P 500 and resets them to equal weights quarterly, according to the provider’s April 2026 FAQ. That schedule describes this index, not a universal ETF rule.
A four-stock example shows the difference
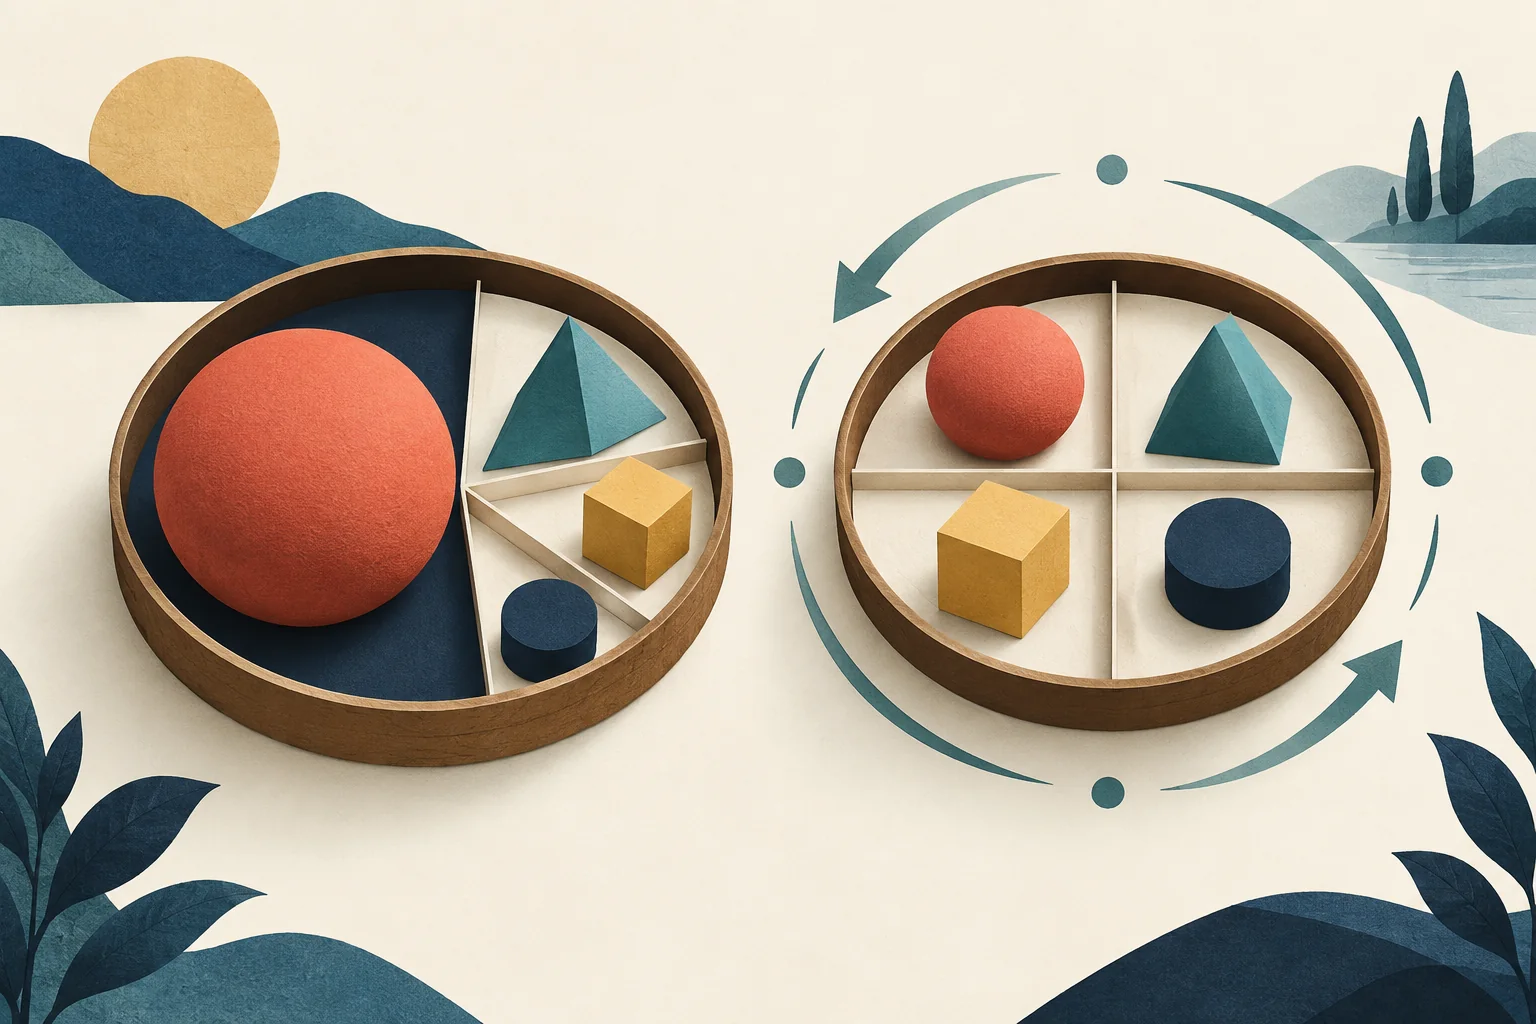
Imagine four hypothetical companies with float-adjusted market values in the ratio 40:30:20:10. A $10,000 market-cap-weighted portfolio using those proportions would allocate $4,000, $3,000, $2,000, and $1,000. A $10,000 equal-weighted portfolio would allocate $2,500 to each company.
The equal-weight portfolio therefore puts more money in the smallest company and less in the largest one than the market-cap version. It owns the same four names in this example, but it does not have the same exposure. Equal weight changes the influence of each holding; it does not change the companies’ underlying businesses.
Now consider the equal-weight portfolio alone using simpler $100 starting values: each company begins at 25% of the $400 total. If Company A doubles while the other three remain unchanged, the portfolio becomes $200 + $100 + $100 + $100 = $500. Before any rebalance, A is 40% and each other company is 20%.
To restore equal weights, the portfolio would move each holding to $125: sell $75 of A and buy $25 of each other company. These are illustrative arithmetic amounts, not a forecast, an actual ETF’s trade, or a statement about taxes or fees.
Why do equal weights drift and trigger trades?
Equal-weight targets drift because companies’ prices change at different rates. A scheduled reset moves the portfolio back toward the method’s target. In the S&P 500 Equal Weight Index, the quarterly process trims companies whose weights have grown and adds to those whose weights have fallen relative to the target. Other indexes may use different schedules or rules.
That process creates trading. It can reduce the influence of recent relative winners and increase the influence of relative laggards at the reset, but it does not know whether a laggard will recover or a winner will keep rising. The trade is a mechanical consequence of the target weights, not a forecast that prices will revert.
A market-cap-weighted fund also trades when its index adds or removes a company, adjusts public-float shares, or responds to corporate actions. But it does not need to reset every holding to the same percentage simply because one constituent’s price rose more than another’s. Turnover depends on the specific index rules and the fund’s implementation, not only on the label in its name.
Does equal weighting mean more diversification?
Equal weighting can reduce single-company concentration at a rebalance when compared with a market-cap version of the same universe. In the four-stock example, no one company begins with more than 25% of the equal-weight portfolio, while the largest company starts at 40% of the market-cap version.
That is one kind of concentration, not a complete risk score. Equal weighting can still leave an investor concentrated in one country, sector, industry, or shared economic risk. In a broad market index, it also gives relatively more weight to smaller constituents than market-cap weighting does. If the fund tracks a narrow or thematic index, giving its few names equal weights does not turn it into a broad-market portfolio.
Investor.gov explains in its index-fund overview that an index fund follows a securities index, while its asset-allocation guide notes that diversification spreads money among investments but cannot eliminate market risk or guarantee against loss. Review the actual holdings and exposures instead of inferring broad diversification from the words “equal weight.”
Why can returns differ without either method being better?
A weighting rule changes which companies drive returns. When the largest companies outperform the rest, a market-cap-weighted version of the same index will generally receive more of that contribution. When smaller constituents outperform, an equal-weight version may receive more benefit because it began with larger relative weights in those names.
For the S&P 500 Equal Weight Index, S&P DJI describes a tilt toward smaller constituents and a mechanical tendency to rebalance away from relative winners and toward relative laggards. Those exposures can help in some market periods and hurt in others. They are not guaranteed premiums, timing signals, or forecasts of which index will lead next.
When comparing historical results, match the index universe, dates, dividend treatment, and fees. A price-return index and a total-return index answer different questions. Past performance of one weighting method does not establish how it will perform over your holding period.
What costs and fund details should you compare?
Start with the expense ratio, then look beyond it. Rebalancing and changes in an index can create portfolio trading costs. An ETF investor may also face a bid-ask spread, commissions, market impact, and premiums or discounts to NAV. The size and effect of each cost depend on the fund, order, broker, and market conditions; equal weighting does not make every fund more expensive by definition.
The SEC’s mutual fund and ETF fee bulletin explains that some transaction costs are outside a fund’s prospectus expense ratio. Compare the prospectus, shareholder reports, index methodology, reported turnover, trading spreads, and tracking difference for the specific fund. For a broader cost checklist, see ETF expense ratio versus total cost and ETF tracking difference versus tracking error.
Also check whether the funds truly follow the same universe and investment objective. Two funds called “equal weight” may differ in constituents, sector rules, rebalancing cadence, or implementation. Two market-cap funds can use different float adjustments or inclusion rules. The name is only a starting point; the methodology and holdings show what you actually own.
How do you decide which index rules fit your comparison?
Use the exposure you want to evaluate as the starting point, not a past-return leaderboard. Check the index universe, weighting formula, rebalance schedule, current single-name and sector weights, turnover, expense ratio, and tracking history. Then consider whether the added weight to smaller companies, the lower initial weight in the largest companies, or the extra rebalancing trades fit your broader portfolio and tolerance for different return paths.
A market-cap-weighted fund may be a more direct choice when you want constituent weights to follow company size within the index. An equal-weighted fund may be relevant when you deliberately want each constituent to start at a similar weight. Neither method guarantees lower losses, better diversification across asset classes, or higher future returns.
For examples of how index rules shape actual ETF baskets, compare QQQ and VOO holdings overlap. Before drawing a conclusion, check that both funds use comparable dates and return definitions and that the difference you care about comes from weighting rather than different holdings or fund costs.
Common questions
Q1Are equal-weight ETFs safer than market-cap-weighted ETFs?
Not automatically. Equal weighting can reduce the largest stock’s starting weight within a given universe, but it may raise exposure to smaller companies and still leave sector, market, and other risks. Compare the actual holdings and index rules.
Q2Does an equal-weight ETF rebalance every day?
Not necessarily. Each index sets its own schedule and rules. The S&P 500 Equal Weight Index resets quarterly, but other products may use different intervals or methods. Check the fund’s current prospectus and index methodology.
Q3Do equal-weight ETFs always outperform when big stocks fall?
No. Equal-weight funds have different exposures and may benefit when smaller constituents do better, but they can lag when the largest companies lead. A past period does not predict which method will outperform next.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
At a rebalance, how does a four-stock equal-weight index generally set its target weights?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide