

Do Bond ETFs Mature? Traditional vs. Target-Maturity ETFs
Learn why most bond ETFs keep operating as holdings mature, how target-maturity ETFs transition to cash and distribute net assets, and why a target year does not guarantee principal.
In this guideDoes a bond ETF have a maturity date?
Short summary
A bond can have a contractual maturity date. An ETF share usually does not mature just because bonds inside the portfolio do. Most bond ETFs maintain continuing exposure by replacing or adjusting holdings. Some target-maturity ETFs are designed to wind down in a named year, move maturing proceeds into cash or cash equivalents, and distribute the fund's remaining net assets. A target year is a planned fund life cycle, not a promise to return your original investment. This guide focuses on U.S.-listed bond ETFs; each fund's prospectus controls its actual dates and terms.
Does a bond ETF have a maturity date?
Usually, the bonds in a fund have maturity dates; the ETF share itself does not. FINRA's ETF overview says most bond ETFs provide continuous exposure to bond investments, while some hold portfolios with a targeted maturity date. That distinction is a useful starting point: a bond's due date and a fund's planned termination date are different things.
For an individual bond, the issuer owes the scheduled payments under the bond's terms. If the issuer meets its obligation, it pays the final interest and face value at maturity. FINRA notes that selling before maturity instead means accepting the bond's then-current secondary-market price, which may be below or above the amount due at maturity. See FINRA's bond overview for the individual-bond mechanics.
An ETF shareholder owns fund shares, not direct claims on each bond's principal repayment. When a holding matures, the cash belongs to the fund. What happens next depends on the ETF's stated strategy and documents.
What happens when a bond in a traditional bond ETF matures?
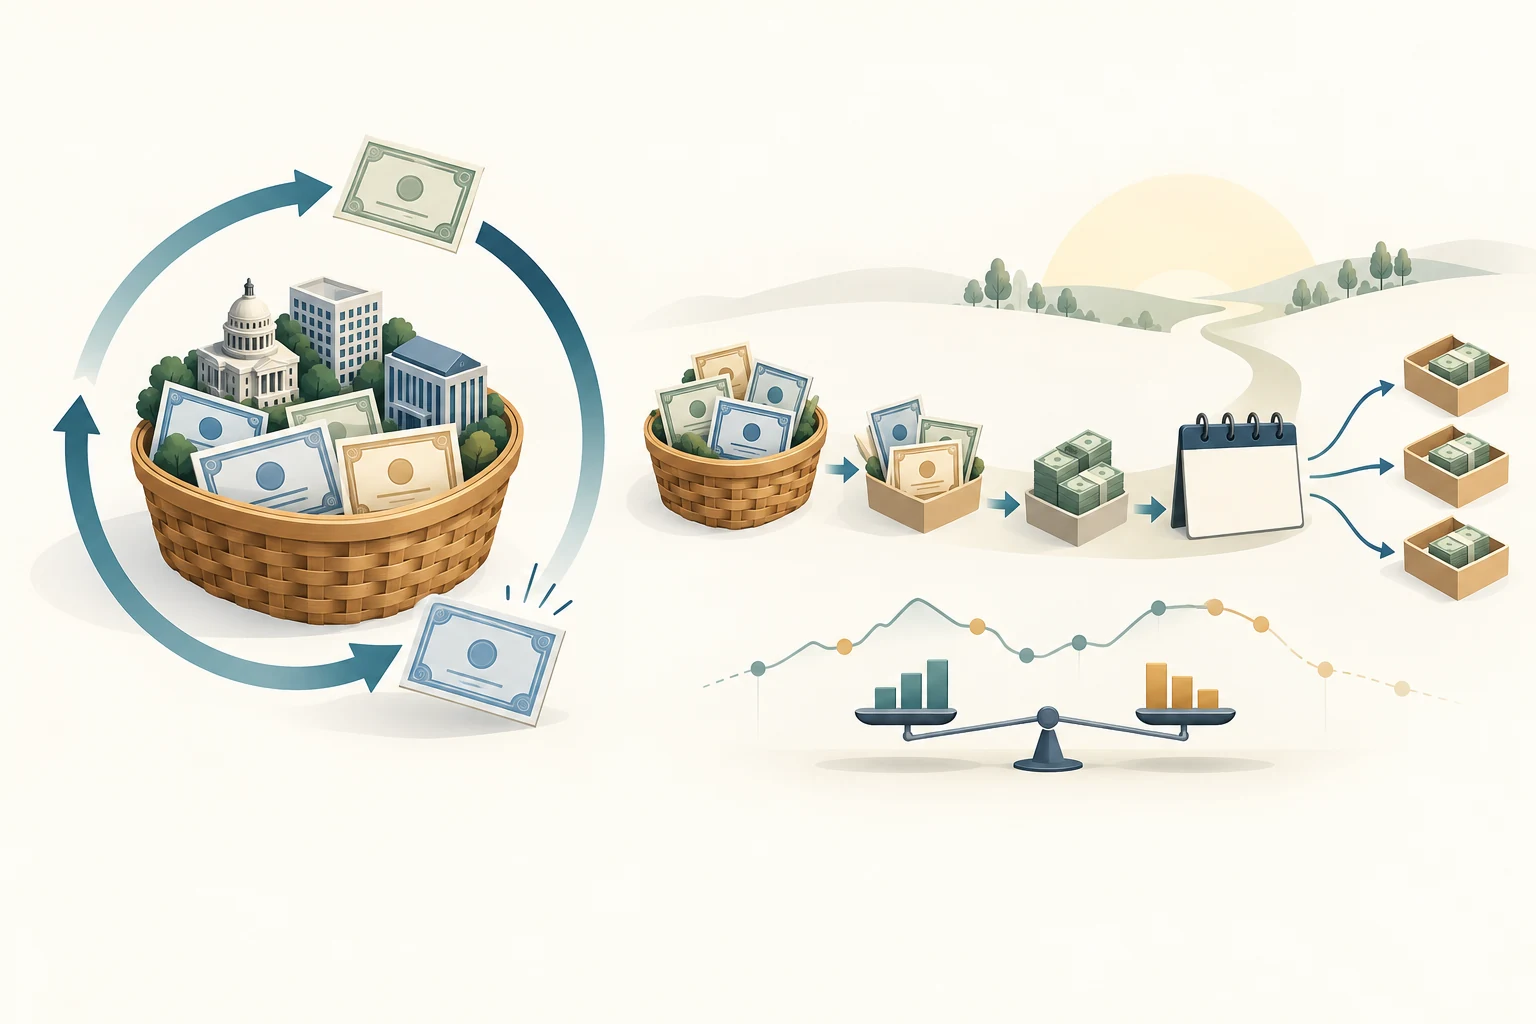
A traditional bond ETF generally aims to keep its investment exposure going rather than terminate when one portfolio bond comes due. The fund receives cash from maturities, sales, coupon payments, or calls; it may use proceeds to buy other bonds or adjust the portfolio to keep following its index or mandate. The maturity profile changes over time, but the ETF share remains outstanding unless the fund separately takes action to close or reorganize.
This is why a bond ETF's average maturity is not a date when every shareholder gets principal back. A portfolio can contain thousands of bonds with different payment schedules, and its holdings can change. FINRA describes most bond ETFs as offering continuous exposure, while some are built around a specified maturity date in the portfolio.
For a conventional bond fund, the investor's result comes from distributions and changes in the fund share's market value. Maturing bonds can add cash to the fund, but they do not trigger a pro-rata repayment of the ETF shareholder's original purchase price.
What does target maturity mean for an ETF?
A target-maturity, defined-maturity, or bullet-style bond ETF is designed around bonds scheduled to mature in a particular calendar year and a planned end to the fund. The year in its name generally identifies the intended maturity window, but the exact bond eligibility rules, termination date, and distribution process are fund-specific. Read the prospectus rather than treating the ticker or year label as a contractual payment date.
Do not confuse a target-maturity ETF with a target-date retirement fund. A target-date fund usually changes its asset allocation over time for a retirement horizon. In its SEC-filed prospectus for Vanguard Target Maturity 2027 Corporate Bond ETF, Vanguard explicitly distinguishes its defined-maturity ETF from a target-date fund. The filing describes a fund that holds bonds tied to a target year and is planned to liquidate around a stated date.
The structure can be used as one rung in a bond ladder: separate funds target different calendar years. This can package a diversified group of bonds in an exchange-traded share, but it does not make each fund equivalent to one bond or guarantee a fixed payment on the year shown.
What happens as a target-maturity ETF approaches its target year?
As portfolio bonds mature or are called, the fund may move the proceeds into cash or cash equivalents instead of buying replacement bonds with later maturities. The portfolio's interest-rate sensitivity can decline as its end date approaches, and its income can change as holdings are replaced by cash-like investments. These details depend on the fund's prospectus and the bonds it owns.
For example, the iShares iBonds investor guide describes its series transitioning to cash and cash equivalents as bonds mature, then delisting and distributing remaining net assets after the portfolio's bonds mature. The guide says iBonds funds terminate in October or December of the year in the fund name, depending on the specific product. Invesco describes its BulletShares funds as designed to terminate in December of the designated year; it says proceeds from bonds that mature or are called during the final six months may be held in cash or cash equivalents. These are issuer-specific examples, not a universal schedule.
The expected end date and the dates for the final exchange trade, final NAV, record date, and payment may not be identical. The Vanguard filing describes a planned liquidation on or around the specified date, after which remaining net assets are distributed after liabilities. Check the current prospectus and fund notices for the exact sequence.
Does the final distribution return my original investment?
No. At termination, the fund distributes its remaining net assets under its liquidation process; that amount is based on the fund's value after expenses and liabilities, not a promise to repay each shareholder's purchase price or a predetermined dollar amount. A share's market price may also have differed from NAV when the investor bought or sold it.
The SEC-filed Vanguard prospectus says distributions and the liquidation amount cannot be predicted when investing. It notes that the liquidation proceeds may be higher or lower than the investor's initial amount and that this can result in a tax gain or loss. iShares similarly says its iBonds funds are not guaranteed and do not seek to return a predetermined amount. Invesco also discloses that its BulletShares distribution and liquidation proceeds are not predictable at purchase and that an investor may receive more or less than the original investment.
To evaluate what happened, consider all cash flows: the price paid for the ETF share, distributions received, any proceeds at liquidation, and transaction costs and taxes that apply to the account. A final distribution by itself is not the fund's total return. The fund can finish above or below its starting NAV, and an investor's result also depends on purchase price and timing.
What can change the fund's value or final payout?
Target-maturity ETFs still carry bond-fund risks while they operate. Interest rates and investors' assessments of an issuer's ability to pay can change the market value of holdings. An issuer can default, a callable bond can be repaid earlier than expected, and the proceeds may need to be reinvested at a different yield. The fund may also face liquidity constraints, expenses, trading costs, and index-tracking or sampling differences. A planned end date does not remove these risks.
The Vanguard filing discusses interest-rate, credit, liquidity, call, and tracking risks for its own fund. It also states that ETF shares trade at market prices and may be above or below NAV. Invesco's BulletShares disclosure likewise notes expenses, possible loss, variable distributions, and the possibility that liquidation proceeds differ from the original investment. Treat these statements as product-specific risk disclosures and review the documents for the ETF you are considering.
The target year also does not freeze the ETF's value. If bonds are sold before maturity, if issuers repay debt early, or if fund costs accumulate, the resulting cash and net assets can differ from an investor's expectation. For a fuller explanation of rate sensitivity, see bond ETF duration and rate risk. For income measures that are not promised payouts, see ETF SEC yield, distribution yield, and portfolio YTM.
How do distributions, taxes, and brokerage dates fit in?
Monthly or periodic fund distributions are not the same as a bond's final principal payment. A target-maturity fund's distribution rate and tax classification can vary. The iShares guide and the Vanguard filing warn that distributions and liquidation proceeds can affect the tax characterization of an investor's return; a taxable gain or loss may depend on the shareholder's basis and account. Tax treatment is personal, so use the fund's final tax documents and consult a qualified tax professional for individual questions.
The fund's planned termination date also does not tell you exactly when cash will appear in a brokerage account. Review the fund's notice for its last trading day, valuation date, shareholder-of-record details, expected liquidation or distribution date, and any timing caveats. Ask the broker how it will process the final distribution and whether an open order or a share purchased near the cutoff could affect eligibility. Do not assume every platform posts proceeds on the same day.
If you sell before termination, you receive the exchange-market price for your shares, which can differ from NAV, less any applicable trading costs. If you hold through liquidation, you receive the distribution through the fund and brokerage process rather than an individual bond's face-value repayment. For ordinary ETF closure and merger steps, see what happens when an ETF closes.
Can target-maturity ETFs serve as bond-ladder rungs?
They can be designed for that role. A bond ladder staggers maturities across years so that bonds or fund holdings are scheduled to mature at different times. A target-maturity ETF can group multiple bonds into one exchange-traded fund and provide a planned end year; proceeds may then be spent or reinvested in another rung. Invesco describes its BulletShares as tools for building bond ladders, and iShares describes iBonds as a way to assemble bond ladders with funds targeting different years.
The trade-off is that a fund's end-date distribution is variable. Diversification across bonds does not remove credit or market risk, and the ETF's expenses, distributions, cash transition, and liquidation amount differ from holding a single bond directly. A ladder built from ETFs can help organize time horizons, but it cannot promise a particular amount will be available on a specific day.
What should you check before matching a target year to a cash need?
Start with the fund's current prospectus and termination notice, not only its name. Confirm the target maturity year, planned termination date, bonds eligible for the portfolio, whether holdings may be called, when proceeds begin moving to cash, and how the final net-asset distribution is calculated. Check the as-of dates for holdings, NAV, duration, and yield figures. Compare the expense ratio and other fund costs, credit quality, yield measures, current NAV and market price, and any tracking or sampling approach.
Then check the investor-level details: your purchase price and cost basis, distribution treatment, account type, possible tax consequences, last trading and record dates, and your broker's estimate for posting the final cash distribution. If the money is needed on a fixed date, allow for the fund and brokerage timetable and recognize that the amount may be uncertain.
The useful comparison is not simply “bond ETF or individual bond.” Ask whether you want continuous bond-market exposure or a portfolio built around a planned end year, then compare the specific cash flows, risks, costs, and disclosures. Treat the target year as a planning feature with conditions, not as a guarantee of principal or exact payment timing.
Common questions
Q1Does a bond ETF return my principal when its holdings mature?
Not as a direct repayment to each ETF shareholder. A traditional bond ETF receives proceeds inside the fund and generally keeps managing the portfolio. A target-maturity ETF may make a final fund-level distribution around its planned termination, but the amount is not guaranteed to equal your purchase price.
Q2Is a target-maturity ETF the same as a target-date fund?
No. A target-maturity bond ETF is organized around bonds maturing in a stated year and a planned fund termination. A target-date fund typically changes its asset allocation over time for a goal such as retirement. Read the prospectus because names can sound similar while describing different structures.
Q3When will my broker deposit a target-maturity ETF's final distribution?
It depends on the fund's liquidation schedule and the broker's processing. Check the current fund notice for the last trading, valuation, record, and expected distribution dates, then confirm timing with your brokerage. The planned maturity year alone is not an exact cash-availability date.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What usually happens when a bond matures inside a traditional bond ETF?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide