

G-Spread vs. I-Spread vs. Z-Spread vs. OAS
Compare bond G-spread, I-spread, Z-spread, and option-adjusted spread with formulas, a worked example, and model limits
In this guideWhy are there several bond spread measures?
Short summary
Bond spreads all describe a yield or pricing difference, but they do not use the same reference curve or cash-flow assumptions. G-spread and I-spread compare a bond's yield with one benchmark yield; Z-spread uses the full spot curve; OAS adds a model-based adjustment for embedded options.
Why are there several bond spread measures?
A bond spread is a difference between a bond's yield or modeled discount rate and a reference measure. Investors use spreads to compare bonds, describe compensation for risk, and separate some interest-rate movement from issuer-specific or market effects. The result depends on the benchmark and calculation, so two spread figures can differ without either being an arithmetic mistake.
The CFA Institute lists benchmark, G-spread, I-spread, Z-spread, and option-adjusted spread as distinct measures and notes that each has advantages and disadvantages. The useful question is not which acronym is always best. Ask what curve the number references, whether it uses one yield or every cash flow, and whether it accounts for an embedded option.
Spreads are normally reported in basis points. One basis point is 0.01 percentage point, so a 1.25 percentage-point difference equals 125 basis points. A spread is not a coupon, a guaranteed extra return, or a direct probability of default. It is a market comparison under stated conventions.
A simple benchmark spread and the G-spread
A simple or nominal spread subtracts a chosen government-bond yield from the risky bond's yield to maturity. For a meaningful comparison, the government reference should be in the same currency and close to the risky bond's maturity. A mismatch can make the spread reflect different points on the yield curve rather than only a difference between issuers.
The G-spread, or government spread, commonly compares the bond's yield to maturity with an interpolated government yield for the same maturity. If a seven-year corporate bond yields 5.20% and the matched government benchmark is 4.55%, the G-spread is 0.65 percentage point, or 65 basis points. Interpolation estimates a curve point between observed government securities; the exact benchmark construction is a market convention.
Because both yields are reduced to one maturity point, the G-spread is easy to explain and compare. It does not discount each coupon using its own point on the curve. It also does not remove liquidity, credit, tax, or option effects from the difference.
The I-spread uses a swap reference
The I-spread is the difference between a bond's yield to maturity and the interest-rate swap rate for a comparable maturity. “I” refers to the interbank or swap reference convention used by the relevant market. In practice, the curve, swap tenor, currency, compounding, and quote source need to be identified; conventions can differ across currencies and data providers.
For example, if the same bond yields 5.20% and the selected seven-year swap rate is 4.70%, the I-spread is 50 basis points. That is 15 basis points below the 65-basis-point G-spread above because the two calculations use different benchmark rates. It does not mean the bond's underlying credit risk changed when the reference curve changed.
The swap curve is a market reference, not a universal risk-free curve or a cash government bond. Swap spreads and funding conditions can move independently of government yields. When comparing I-spreads, make sure both observations use the same swap-curve convention and timestamp.
The Z-spread uses every scheduled cash flow
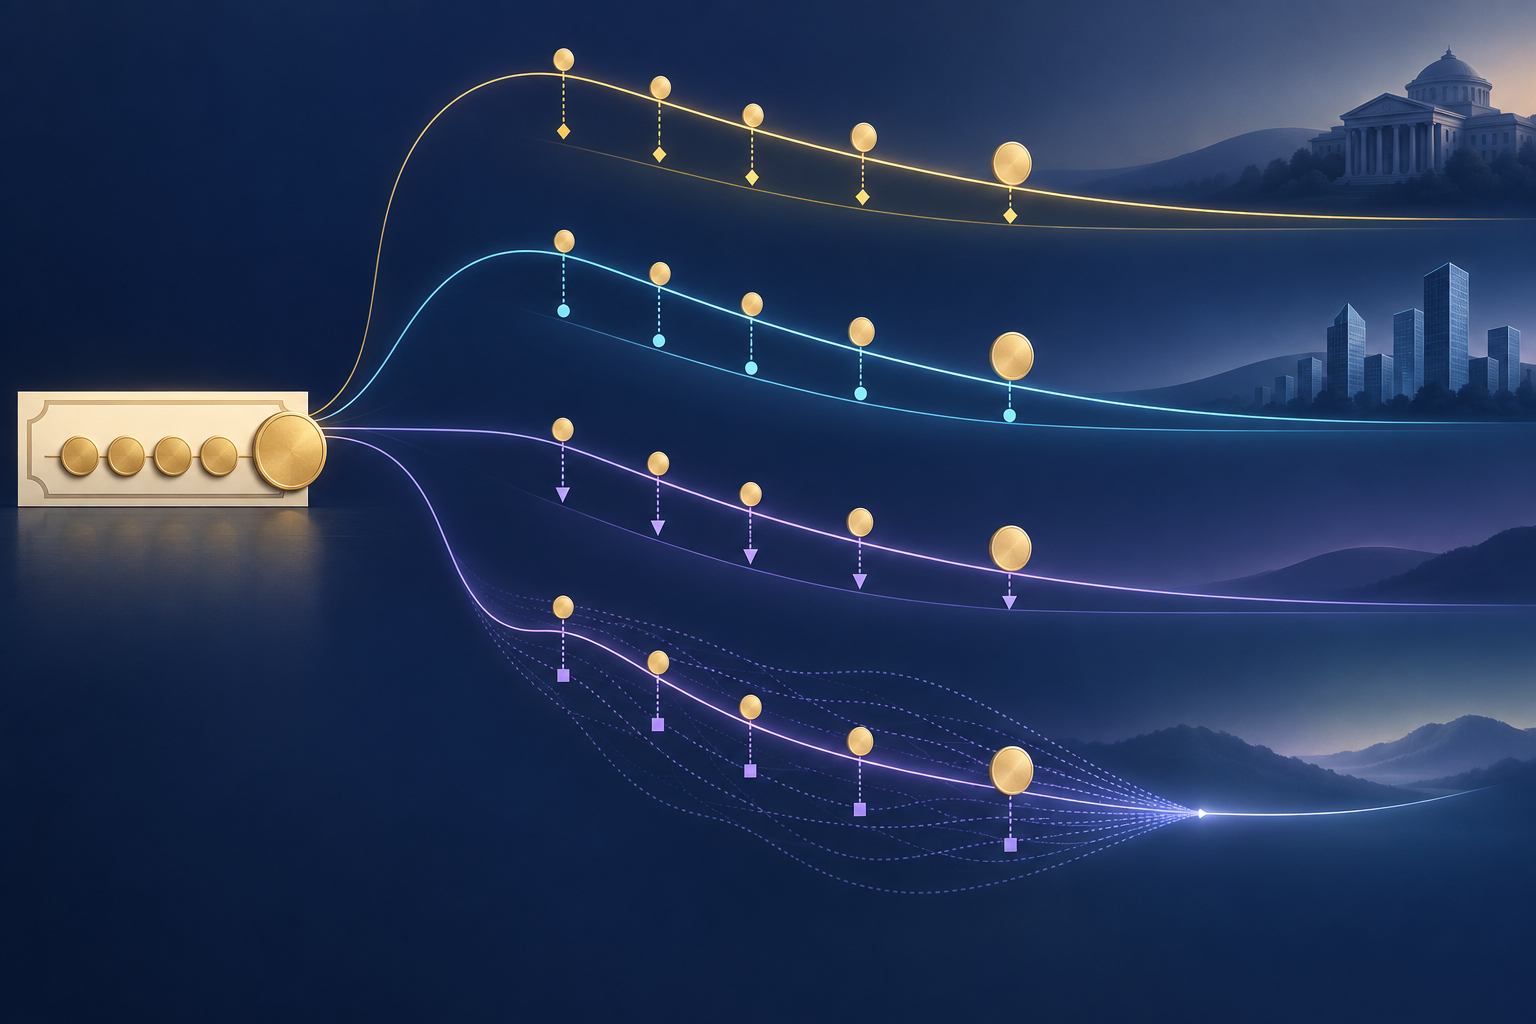
The zero-volatility spread, usually called the Z-spread, is the constant spread added to each point on a zero-coupon spot curve so the discounted value of the bond's scheduled cash flows equals its market price. A spot curve has a rate for each payment date, rather than one yield for the bond's final maturity.
With annual compounding and fixed annual cash flows, the simplified pricing equation is: price = sum of CF(t) divided by (1 + spot rate(t) + Z-spread)^t. In an actual calculation, the payment calendar, settlement date, accrued interest, day count, compounding, curve construction, and price convention must also match.
Using a spot rate for each coupon date recognizes that the first coupon and final principal are discounted over different horizons. That is the key distinction from subtracting one interpolated yield as in a G-spread. The Z-spread remains a single parallel addition to the curve; it does not model a range of future interest-rate paths.
This is most straightforward for a bond whose cash flows are fixed. If a call, put, prepayment feature, or other option can change the timing or amount of payments, treating every future cash flow as known can distort the comparison.
OAS adds an embedded-option model
An option-adjusted spread, or OAS, is calculated within a bond-pricing model that accounts for an embedded option. For a callable bond, the issuer may repay the bond early under stated terms; for a mortgage security, borrowers may repay principal earlier than scheduled. Those choices make future cash flows depend on how rates and other conditions evolve.
The model projects possible cash flows, discounts them along modeled rate paths, and solves for the spread that makes the model value match the observed price. ICE's published index methodology describes its OAS as a shift to a government spot curve, and uses a short-rate model for securities with embedded options. Other vendors may use different curves, models, volatility inputs, and cash-flow assumptions.
OAS aims to separate the option's modeled value from the remaining spread, but the result is not model-free. A change in assumed volatility or prepayment behavior can change projected cash flows and OAS even if the observed bond price is unchanged. The difference between Z-spread and OAS is a model-based option adjustment, not a directly quoted fee or guaranteed yield.
For an option-free bond, OAS under the same curve and cash-flow conventions will generally be close to, or coincide with, Z-spread. That relationship should not be carried over automatically to callable bonds, mortgage-backed securities, or comparisons using different vendor methods.
One hypothetical bond, three spread calculations
Consider a hypothetical three-year, noncallable bond with $100 face value, a 5% annual coupon, and a clean price of $98. It pays $5 after year one, $5 after year two, and $105 after year three. Assume annual compounding and ignore accrued interest and transaction costs.
Solving 98 = 5/(1+y) + 5/(1+y)^2 + 105/(1+y)^3 gives a yield to maturity of about 5.7447%. Suppose the interpolated three-year government yield is 4.30% and the selected three-year swap rate is 4.45%. The G-spread is 5.7447% − 4.30% = 1.4447%, or about 144.5 basis points. The I-spread is 5.7447% − 4.45% = 1.2947%, or about 129.5 basis points.
Now assume the illustrative government zero rates are 4.00% for year one, 4.20% for year two, and 4.40% for year three. Solving 98 = 5/(1+4.00%+z) + 5/(1+4.20%+z)^2 + 105/(1+4.40%+z)^3 gives z of about 1.3579%, or 135.8 basis points. The G-, I-, and Z-spreads differ because their reference curves and calculation methods differ, not because the example changes bonds.
These are hypothetical inputs chosen to demonstrate the calculations, not market quotes. The example is deliberately option-free, so it does not generate a separate modeled OAS result. A real OAS calculation would need the bond's terms, settlement and price conventions, a selected curve, and—where relevant—option, volatility, and cash-flow assumptions.
What a spread can and cannot tell you
A wider spread can reflect compensation for expected credit losses, downgrade risk, liquidity, uncertainty, taxes, market risk premiums, or technical supply and demand. FINRA notes that bond spreads can change with credit risk, supply and demand, and economic conditions. A spread number alone cannot identify which factor caused a move.
Nor is a spread a default probability. Expected loss depends on both the chance of default and the amount recovered after default; a market spread can also include liquidity and risk premiums. A spread can widen while the issuer's reported financial condition is unchanged, or tighten while important risks remain.
An index OAS is an aggregate built from constituent bonds and a weighting method. It is not the spread on every bond in the index, and it may move when the composition or weights change. The corporate-bond and Treasury-yield guide explains why a benchmark yield and a corporate spread can move in opposite directions.
How to compare spread figures fairly
Start with the bond and the observation: identify the security, price side, timestamp, settlement date, currency, seniority, maturity, and embedded options. A dealer bid, an evaluated mid-price, and a last trade can imply different yields and spreads even before any curve choice changes.
Then name the measure and the reference curve. For G-spread, check the government curve and interpolation. For I-spread, record the swap curve and tenor. For Z-spread, check the zero curve, cash-flow schedule, and compounding. For OAS, record the pricing model, rate volatility, prepayment or exercise assumptions, and whether the spread is measured against a government or other curve.
Finally, compare bonds with similar currency, structure, rating, seniority, and liquidity. A 150-basis-point OAS on a callable security is not automatically “richer” or “cheaper” than a 140-basis-point G-spread on a bullet bond. The bond convexity guide explains how bond features affect price sensitivity; the mortgage prepayment guide shows why modeled cash flows matter for mortgage securities.
Common questions
Q1Is a higher OAS always a better value?
No. A higher OAS can reflect greater credit, liquidity, or other risk, as well as a valuation difference under a model. Compare the same measure, curve, timestamp, and bond features before drawing a conclusion.
Q2Can I use a G-spread for a mortgage-backed security?
You can calculate a simple yield difference if you label it clearly, but it does not account for rate-sensitive prepayments. OAS is designed to include a model of changing cash flows, though it remains sensitive to model assumptions.
Q3Is a bond spread the same as its default probability?
No. A spread is a yield or pricing difference. It can include expected credit loss and risk premiums, but it is not a direct probability that the issuer will default.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
What does a G-spread commonly compare?
Choose an answer to see the explanation
Options glossary
A call or put whose strike is near the underlying price; it has little intrinsic value and often substantial sensitivity to time and volatility.
Read the deeper guideCall optionA contract that gives its holder the right, but not the obligation, to buy the underlying at the strike before or at expiration under the contract terms.
Read the deeper guide