

Agency Securities vs. U.S. Treasuries: Guarantees, Yield, and Risk
Compare U.S. agency securities with Treasury debt by issuer, legal guarantee, yield spread, liquidity, taxes, and market risk.
In this guideWhat counts as an agency security?
Short summary
“Government-backed” can describe very different promises. To compare an agency security with a U.S. Treasury, identify who owes the payment, who guarantees it, and which risks remain even when a guarantee applies.
What counts as an agency security?
Agency securities are debt securities issued or guaranteed by U.S. federal agencies other than the Treasury, or by government-sponsored enterprises (GSEs). The label describes a broad family, not one uniform federal promise. A Fannie Mae or Freddie Mac debenture is an obligation of that enterprise. A Ginnie Mae mortgage-backed security is a different instrument: approved issuers pool mortgages and Ginnie Mae guarantees defined payments on the securities.
That distinction matters because a bond’s name, housing mission, or federal charter does not by itself establish who must pay you. Start with the exact security, issuer, guarantor, and offering documents. FINRA’s agency-securities overview explains the category and warns that GSE status is not the same as being a federal agency.
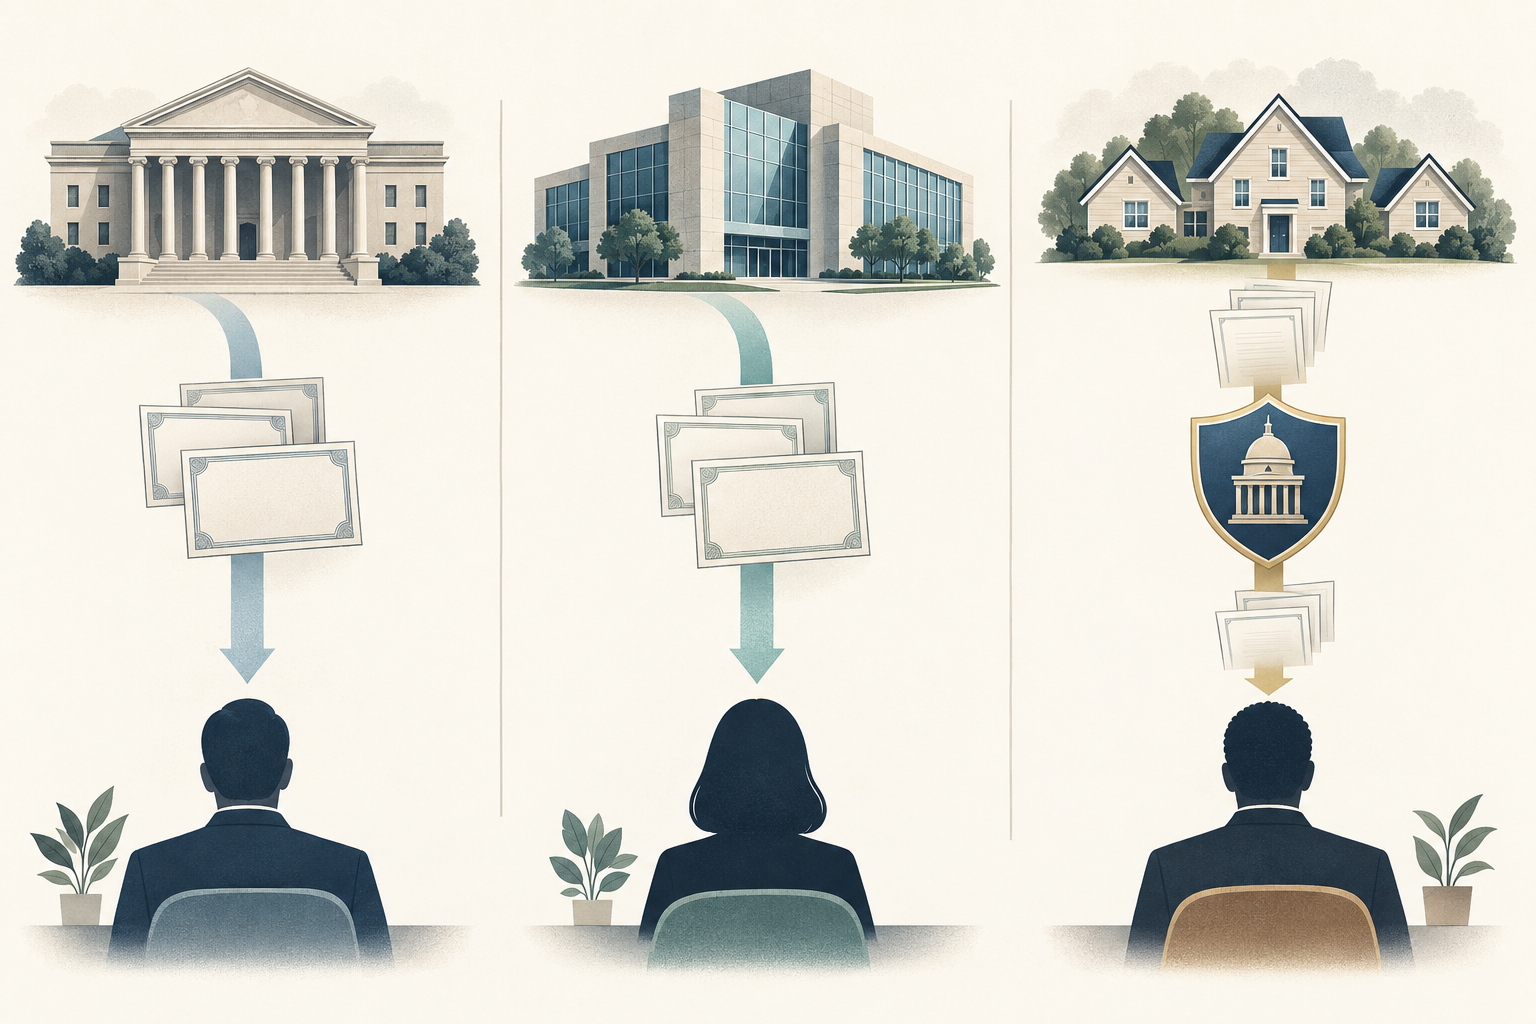
Three different payment promises
A marketable Treasury is issued by the U.S. Department of the Treasury and is backed by the full faith and credit of the United States. For a qualifying Ginnie Mae MBS, Ginnie Mae guarantees timely payment of scheduled principal and interest under its program rules; its guide describes the guarantee and the role of the issuer. By contrast, ordinary Fannie Mae, Freddie Mac, or Federal Home Loan Bank debt is generally an obligation of the named enterprise or bank, not a Treasury security.
Do not transfer one guarantee from one security type to another. Ginnie Mae’s guarantee applies to the covered security cash flows described in the governing documents; it does not turn the underlying mortgages into Treasury debt or guarantee every feature, market price, prepayment penalty, or resale value. Read the guarantee language for the CUSIP or pool you are considering.
Chapter 1 of the Ginnie Mae MBS Guide describes the issuer’s role and the scope of its guarantee.
What Fannie Mae and Freddie Mac support does—and does not—mean
Fannie Mae and Freddie Mac have operated under FHFA conservatorship since September 2008. FHFA says Treasury provides financial support to the enterprises through the Senior Preferred Stock Purchase Agreements. That is important background about the enterprises’ current structure, but it is not the same wording as an explicit full-faith-and-credit guarantee of every Fannie Mae or Freddie Mac bond.
The practical question is still the legal obligation in the particular offering circular or pricing supplement. Separate the issuer’s own promise, any contractual or statutory guarantee, and broader government support or policy expectations. A rating, federal oversight, conservatorship, or past intervention may affect market views; none should be substituted for the actual security terms. See FHFA’s conservatorship overview and the issuer’s offering materials.
Why an agency yield can differ from a Treasury yield
Investors often compare an agency yield with a Treasury yield of similar maturity. The difference is sometimes called an agency spread, but it is not a pure default-risk meter. It can reflect the specific issuer and guarantee, cash-flow timing, call or prepayment options, liquidity, supply and demand, financing conditions, tax treatment, and how the two yields are calculated.
Suppose a hypothetical five-year agency note yields 4.40% and a Treasury benchmark yields 4.00%. The arithmetic difference is 0.40 percentage point, or 40 basis points. It does not mean the agency security will reliably deliver 40 basis points more cash income. The comparison may be distorted if one issue is callable, has different duration, trades at a different price, or has less predictable principal payments. These are illustrative rates, not current quotes.
Match cash flows and embedded options
A stated maturity is not always the date an investor should expect to receive every dollar. Some agency debt can be callable or have step-up coupons. Agency MBS pass through principal and interest from mortgage pools, so borrowers can repay or refinance early. When rates fall, faster prepayments can return principal sooner and force reinvestment at lower yields; when rates rise, slower prepayments can extend the expected life of the security.
A payment guarantee and a predictable maturity are separate questions. For a callable note, compare yield to call and yield to worst, and inspect the call dates and prices. For MBS, examine effective duration, prepayment assumptions, pool characteristics, and whether the quotation is for a pass-through or a more complex tranche. The TBA versus specified-pool guide covers delivery and pool differences.
Guarantees do not remove market-price risk
A guarantee addresses the payment obligation it names; it does not hold a security’s market price steady. If market yields rise, the price of a fixed-rate note can fall. A buyer who sells before maturity may realize a loss even if the issuer later pays as promised. Duration is a useful first estimate of rate sensitivity, but it is not a guarantee and does not capture every embedded option or spread movement.
Agency spreads can widen or narrow as investors reassess credit, liquidity, funding, or supply. Even a strong guaranty does not make those market risks disappear. MBS investors also bear the effects of changing prepayment speeds and cash-flow timing. Review the issuer, guarantor, collateral, priority, and optionality separately rather than compressing all risks into a single “government-backed” label.
Liquidity, access, and quoted prices
Treasury securities are widely used as benchmark instruments, while agency debt and MBS trade across different issues, structures, and market channels. Liquidity varies by CUSIP, issue size, age, and market conditions; the word “agency” does not promise a narrow bid-ask spread or an immediate buyer. A dealer quote can also include compensation in the price.
Before comparing offers, check the security identifier, minimum denomination, settlement amount, accrued interest, bid and ask, markup or commission, and recent trading information where available. Compare yields on a consistent basis and use duration or expected cash flows where stated maturity is a poor match. For MBS, compare the same pool or tranche characteristics. A high headline yield is not enough to establish better value.
Tax treatment and investment wrappers
TreasuryDirect says income from Treasury marketable securities is subject to federal tax and exempt from state and local income taxes. Do not automatically apply that rule to every agency obligation. Tax treatment can depend on the issuer, security type, state law, and how a fund distributes income. The offering documents and applicable tax guidance are more reliable than a generic “agency” label.
A bond fund or ETF adds another layer: you own fund shares, not a direct claim on each underlying issuer, and the fund’s distributions and market price follow its own rules. If tax treatment matters to a comparison, confirm it for the exact issue and account jurisdiction. This article is general education, not tax advice.
TreasuryDirect’s pages on marketable securities and tax forms and withholding provide the applicable details.
A checklist before interpreting the label
For each security, write down: (1) the legal issuer; (2) any guarantor and the exact payments covered; (3) the instrument type—agency note, debenture, pass-through MBS, or tranche; (4) maturity, call terms, coupon, and expected cash-flow dates; (5) price, accrued interest, yield convention, and fees; (6) duration, spread, liquidity, and reinvestment risks; and (7) tax treatment for the account and jurisdiction.
Then compare like with like. The Treasury reopening guide explains why the same Treasury CUSIP can have a new auction price, while the MBS prepayment-risk guide explains why mortgage cash flows change. The covered-bond comparison covers another structure with a different legal claim. No single yield spread replaces this document-by-document check.
Common questions
Q1Are Fannie Mae and Freddie Mac bonds backed by the full faith and credit of the U.S. government?
Do not assume so. Their bonds are obligations of the named enterprise unless the specific security documents state an applicable guarantee. Conservatorship and Treasury support are distinct from an explicit guarantee; check the offering documents.
Q2Is a Ginnie Mae MBS the same as a Treasury bond?
No. Ginnie Mae guarantees specified payments on covered mortgage-backed securities under its program. The security still has mortgage cash flows and MBS market risks, and it is not a Treasury issuance.
Q3Do agency bonds always yield more than Treasuries?
No. Any yield difference depends on the exact issue, price, options, cash-flow timing, liquidity, supply and demand, tax treatment, and market conditions. A spread is not a promised return.
Sources and further reading
Report an issue
We’ll prepare an email with this article link. Mark receives the report only after you send it
Quick check
Read the guide? Check yourself with 3 questions
Question 01
Which statement best describes the phrase agency security?
Choose an answer to see the explanation